Business accounts aren't what most people think they are
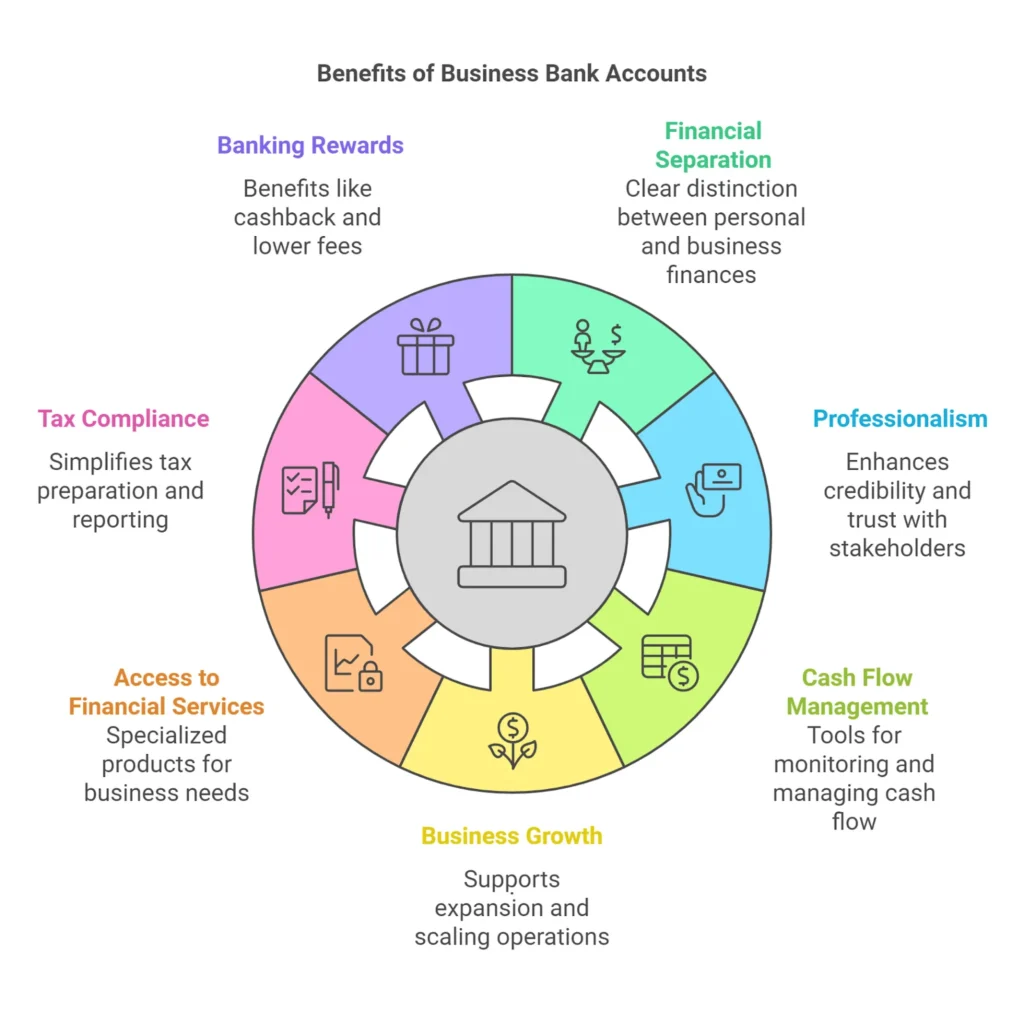
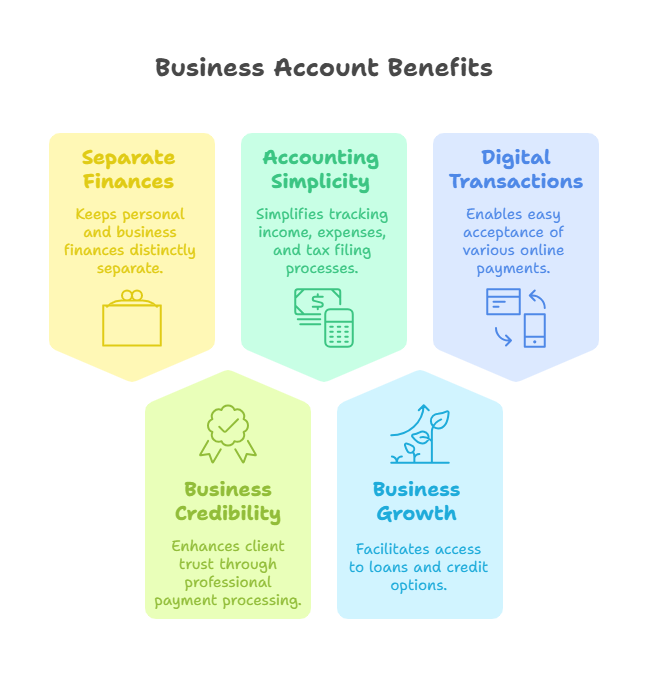
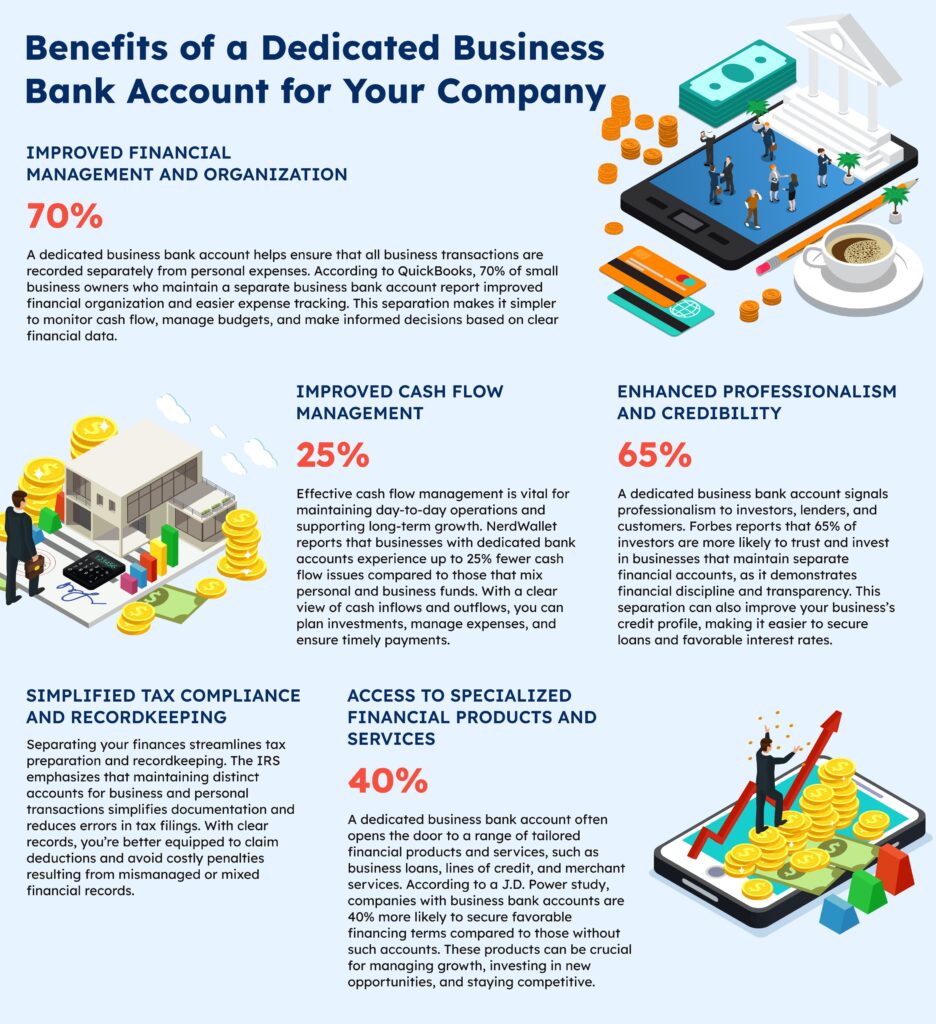
I've watched way too many small business owners open a checking account with no real plan, then spend three weeks untangling a mess that should've been obvious on day one. A business account does exactly what it says. It separates your personal money from your company's money. That's the surface-level thing everyone talks about. The actual value shows up later, when you're filing taxes, getting audited, or trying to get a loan and your bank actually takes you seriously. The first real advantage is liability protection. If you're operating as an LLC or corporation, your personal assets stay personal. Mixing funds voids that protection. I learned this the hard way when a client of mine had a lawsuit come through during a pandemic slump. Because he'd been writing restaurant checks from the business account, the judge pierced the corporate veil. He lost a car. Not a great outcome. It takes maybe two minutes to transfer your deposit from personal to business, but not doing it has consequences that stick around for years. Credit building is another practical advantage most people ignore until they need it. When you run expenses through a business account and pay it off consistently, you start building a trade line. That matters when you need a line of credit or equipment financing. Banks look at your business banking history as part of the underwriting. Some lenders won't even touch the application without six months of account activity. There's no shortcut around that requirement.
Tax time becomes significantly less painful. Everything is categorized and accessible. You export a CSV, send it to your CPA, and they spend twenty minutes instead of two days reconciling. I've done the alternative. It's not fun. You pull receipts from a shoebox, dig through personal statements looking for deductions you thought you recorded, and wonder why your deductions don't match your actual spend. Having everything in one place cuts that process down to about fifteen minutes of review on your end. Professionalism matters more than you'd expect. A vendor who receives payment from a business account rather than a personal name tends to take the relationship differently. There's something about seeing your company name on a check or invoice that changes how people treat you. Not always consciously, but it's there. I've seen contract negotiations shift just because the other party could see the business was legitimate on paper. Access to business lending is probably the biggest advantage, and it's the one that bites people who skip this step. Personal credit scores and business credit scores are different things. With a business account and the right setup, you can build a separate credit profile. Eventually, the business can qualify for financing on its own merits without your personal guarantee. That's a significant exit ramp if things go south. Most people don't know this exists until they're already in debt and looking for options.
There are downsides you should know about. Monthly fees are real. A lot of business checking accounts charge between ten and twenty-five dollars a month unless you maintain a minimum balance or meet transaction thresholds. Some require a minimum opening deposit of five hundred to a thousand dollars. If your business is seasonal or cash-flow irregular, those minimums can be annoying. I've had accounts where I paid fees for three months straight because revenue dipped below the threshold. Worth it long-term, but it stings in the short term. Some banks make it difficult to switch from personal to business after you've already opened accounts with them. I ran into this with one regional bank where the online portal wouldn't let me convert my account. Had to visit a branch, fill out paperwork in triplicate, and wait five business days for the switch. The teller was helpful but the system clearly wasn't designed for that flow. Budget extra time if you're doing this conversion rather than opening fresh. Another practical gotcha: not all business accounts integrate cleanly with accounting software. QuickBooks and Xero support most major banks, but smaller regional banks sometimes lag on API updates. I had a situation where my reconciliation uploads were failing for two weeks because the bank had updated their feed format and the software hadn't caught up. Had to manually import transactions during that window. Before you commit to a bank, check the integration compatibility list for whatever tools you plan to use. Saves a headache.
Get the Full Details
Ownership structure changes matter too. If you open a business account as a sole proprietorship and later form an LLC, you usually can't just convert the account. You'll need to close the old one and open a new one under the LLC with an EIN. That's standard procedure. Don't assume the bank will do it automatically. Call ahead and ask what the transition looks like so you're not stuck mid-month with no access to operating funds. The basic steps to get started are straightforward. Pick a bank that offers business checking with no or low monthly fees, or fees you can realistically meet. Bring your formation documents, EIN verification, and valid ID. Some banks require all owners to be present or provide notarized signatures depending on the entity type. Open the account, set up online banking immediately, and link it to your accounting software before you process your first business transaction. Don't skip that last part. Once transactions start flowing, the reconnection process is more friction. I've found that the people who benefit most from business accounts are the ones who treat the separation seriously from the start. The ones who bounce personal payments through the business account "just this once" tend to create their own problems later. Set the habit early and the rest follows naturally.