Why Your Aetna Medigap Premium Keeps Going Up
The Aetna Medicare Supplement Rate Increase History is something most people only think about when they open their mail and see another notice. I deal with this constantly when clients call me frustrated after their annual renewal letter arrives. The pattern across states is largely the same, but the specifics vary enough that it matters how you read your own policy. Medicare Supplement plans, also called Medigap, are regulated at the state level. That means Aetna files rate increase requests with your state insurance department, not with Medicare itself. The company has to justify the percentage increase with actuarial data showing higher claims costs, administrative expenses, or medical trend data. Most states require advance notice, usually 30 to 60 days before the increase takes effect.
Aetna Medicare Supplement Rate Increase History
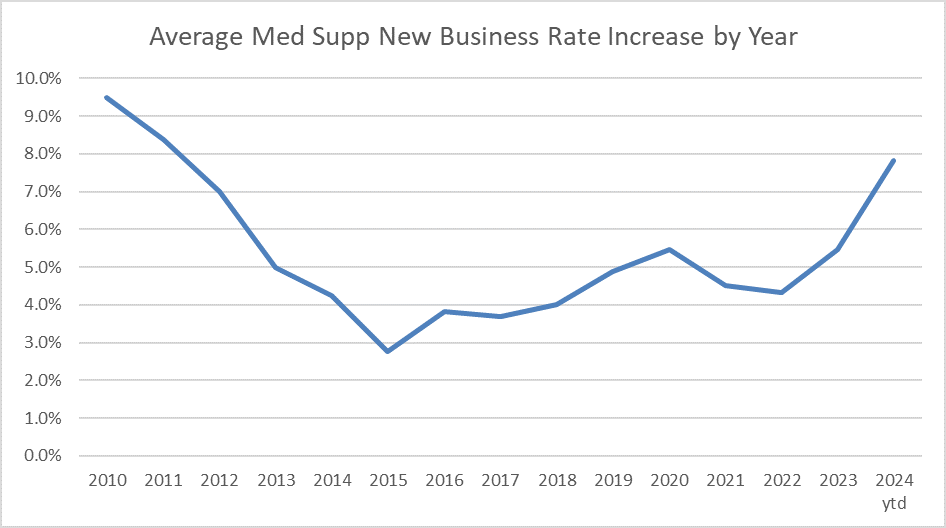
When I look at Aetna's filing patterns over the past decade, the trend is pretty consistent. Annual increases between 2015 and 2019 averaged around 3 to 5 percent in most states. Then during the pandemic years, the increases jumped to somewhere in the 6 to 9 percent range in several markets. By 2023 and 2024, those numbers settled back down to the 4 to 7 percent band. It depends entirely on which state you live in and which plan letter you have. Plan G tends to see higher percentage increases than Plan N because the benefit structure attracts more expensive claims. That is a general observation across the industry, not something unique to Aetna. The older the member pool, the higher the claims cost per person, and that drives the rate upward regardless of the insurer. Here is something most people do not realize. Your rate increase history on Aetna is not determined by your health or your claims. Once you are enrolled, your premium can only change based on the pooling method your policy uses. If you are in an age-attained rating system, your premium goes up every year you get older, plus any general rate increase Aetna files. If you are in issue-age rating, your premium only goes up when Aetna files a blanket increase across the whole book. That is a meaningful difference. People who bought their policy at a younger issue age often end up paying less over time, even if the initial premium looked higher.
I ran into a specific issue last year with a client in Ohio who had a Plan G with Aetna. She received a renewal notice showing an 8.4 percent increase, which seemed high compared to what she had seen before. When I pulled her actual rate increase history through the Ohio Department of Insurance public filings, the 8.4 percent was partly explained by something most people overlook. Aetna had changed her billing frequency from annual to monthly. The monthly billing surcharge was being recalculated, and it added roughly two percentage points to what looked like a pure premium increase. That alone does not mean the increase was unfair. But it meant the real underlying rate change was closer to 6.2 percent, not 8.4. If she had switched back to annual billing, the math would have been simpler and cheaper. The workaround was straightforward. I called Aetna's member services line, asked for the detailed billing breakdown on the renewal notice, and requested the change back to annual billing. That took about twelve minutes on the phone. The effective date was set to her next renewal cycle. It saved her roughly eighty dollars a year going forward. Not life-changing, but noticeable when you are already dealing with a rate hike. There are counter-intuitive things about these rate increases that trip people up. One is the idea that shopping around during your open enrollment period will protect you from future increases. It will not. If you switch to another insurer, you are subject to that new company's rate increase history, which may be worse or better. There is no guarantee either direction. Another misconception is that you can negotiate your rate. You cannot. The rates are filed with the state and are non-negotiable at the individual level.
Get the Full Details
The state DOI website is the most reliable source for actual filed rate increases. Aetna publishes summary notices, but the full actuarial justification documents are available through the state. In many states, you can search by insurer name and plan type. I prefer using the DOI databases because they show you the proposed percentage before it is finalized, not just the result after it takes effect. That gives you a window to act. One important limitation to be aware of. If you are already on a rate increase, switching insurers mid-year generally does not help you avoid it. Most state filing rules tie the increase to your policy number and effective date. Changing carriers means a new application, a new health underwriting process if you are past your guarantee issue period, and a new rate that may already reflect industry-wide cost pressures. The timing almost never works out in your favor unless you are within your initialMedigap Open Enrollment Period, which runs for six months starting the month you turn 65 and are enrolled in Part B. After that window closes, you are subject to medical underwriting in most states, and a rate increase on your current policy becomes your baseline for comparison. Another thing worth knowing is that some states have tighter regulations on how much Aetna can increase rates in a single year. States like New York and Massachusetts have more restrictive rating practices. In those states, you might see smaller percentage jumps than in states with looser oversight. If you live in a high-increase state and your health is stable, moving to a lower-regulation state is not practical for most people, but it is worth knowing why your rates look different from a friend's in another part of the country.
When I review someone's Aetna Medicare Supplement Rate Increase History, I look at three things first. The pooling method on the policy, the state filing trends over the last five years, and whether any billing changes were made alongside the increase. Those three factors explain more than most renewal notices make clear. The rest is just noise.