What Aetna Small Business Plans Actually Cover
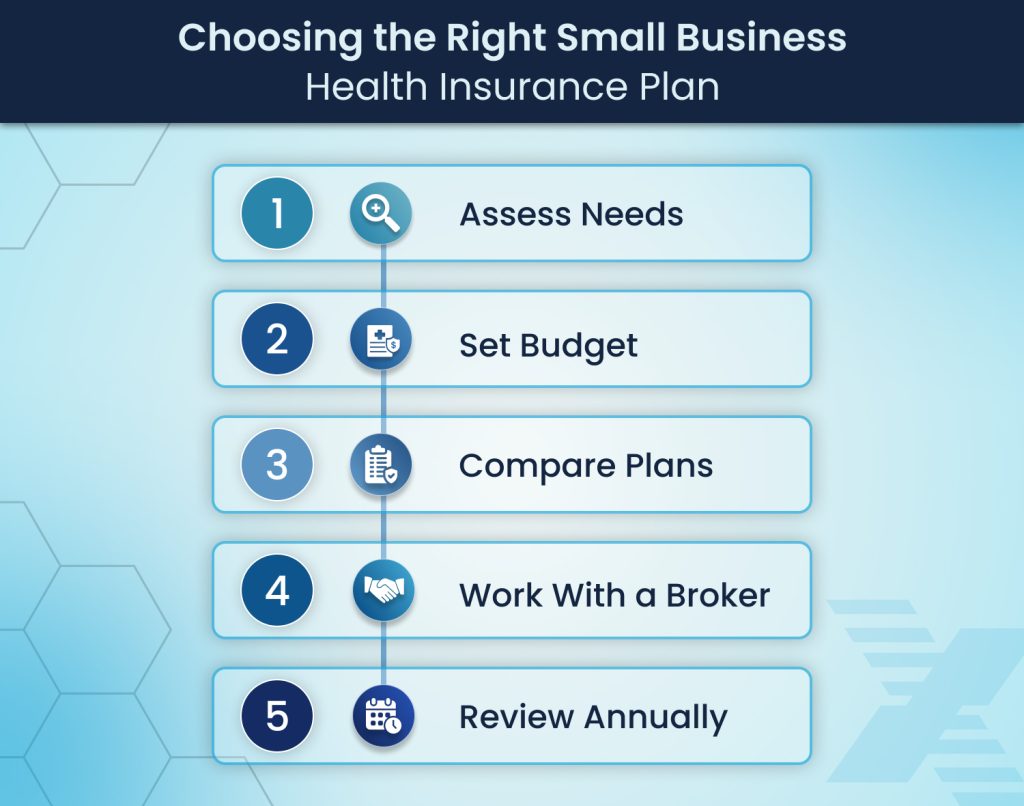
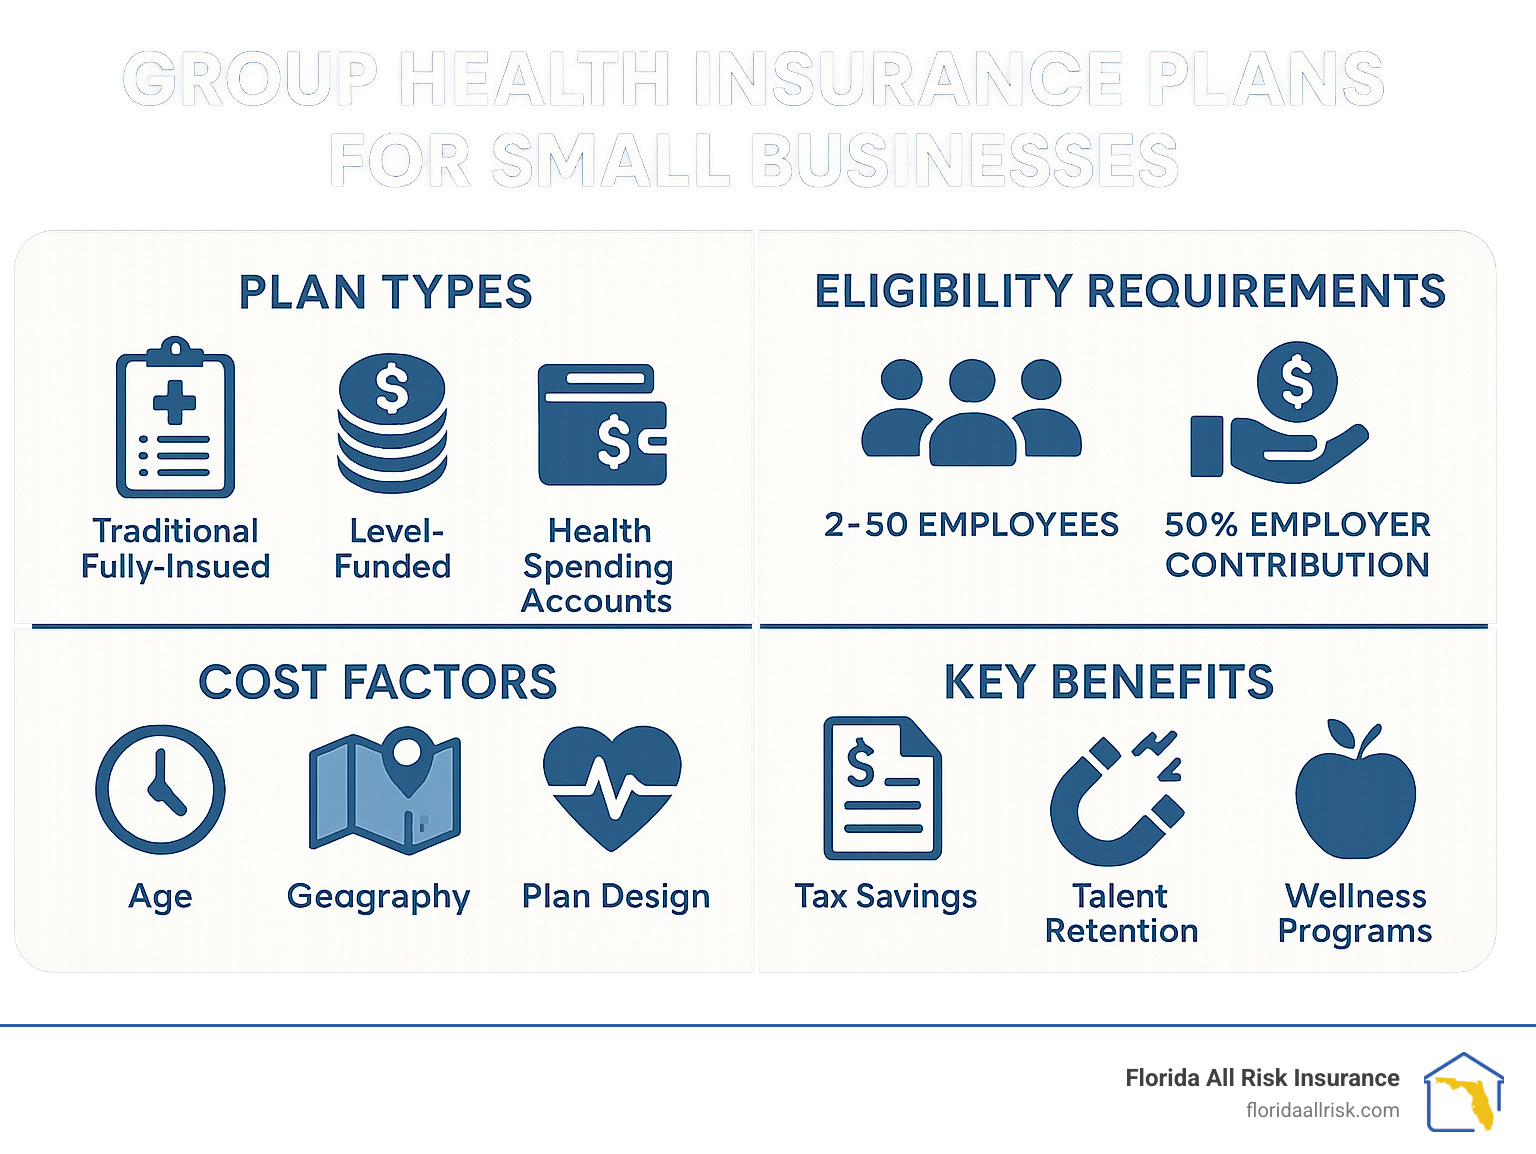
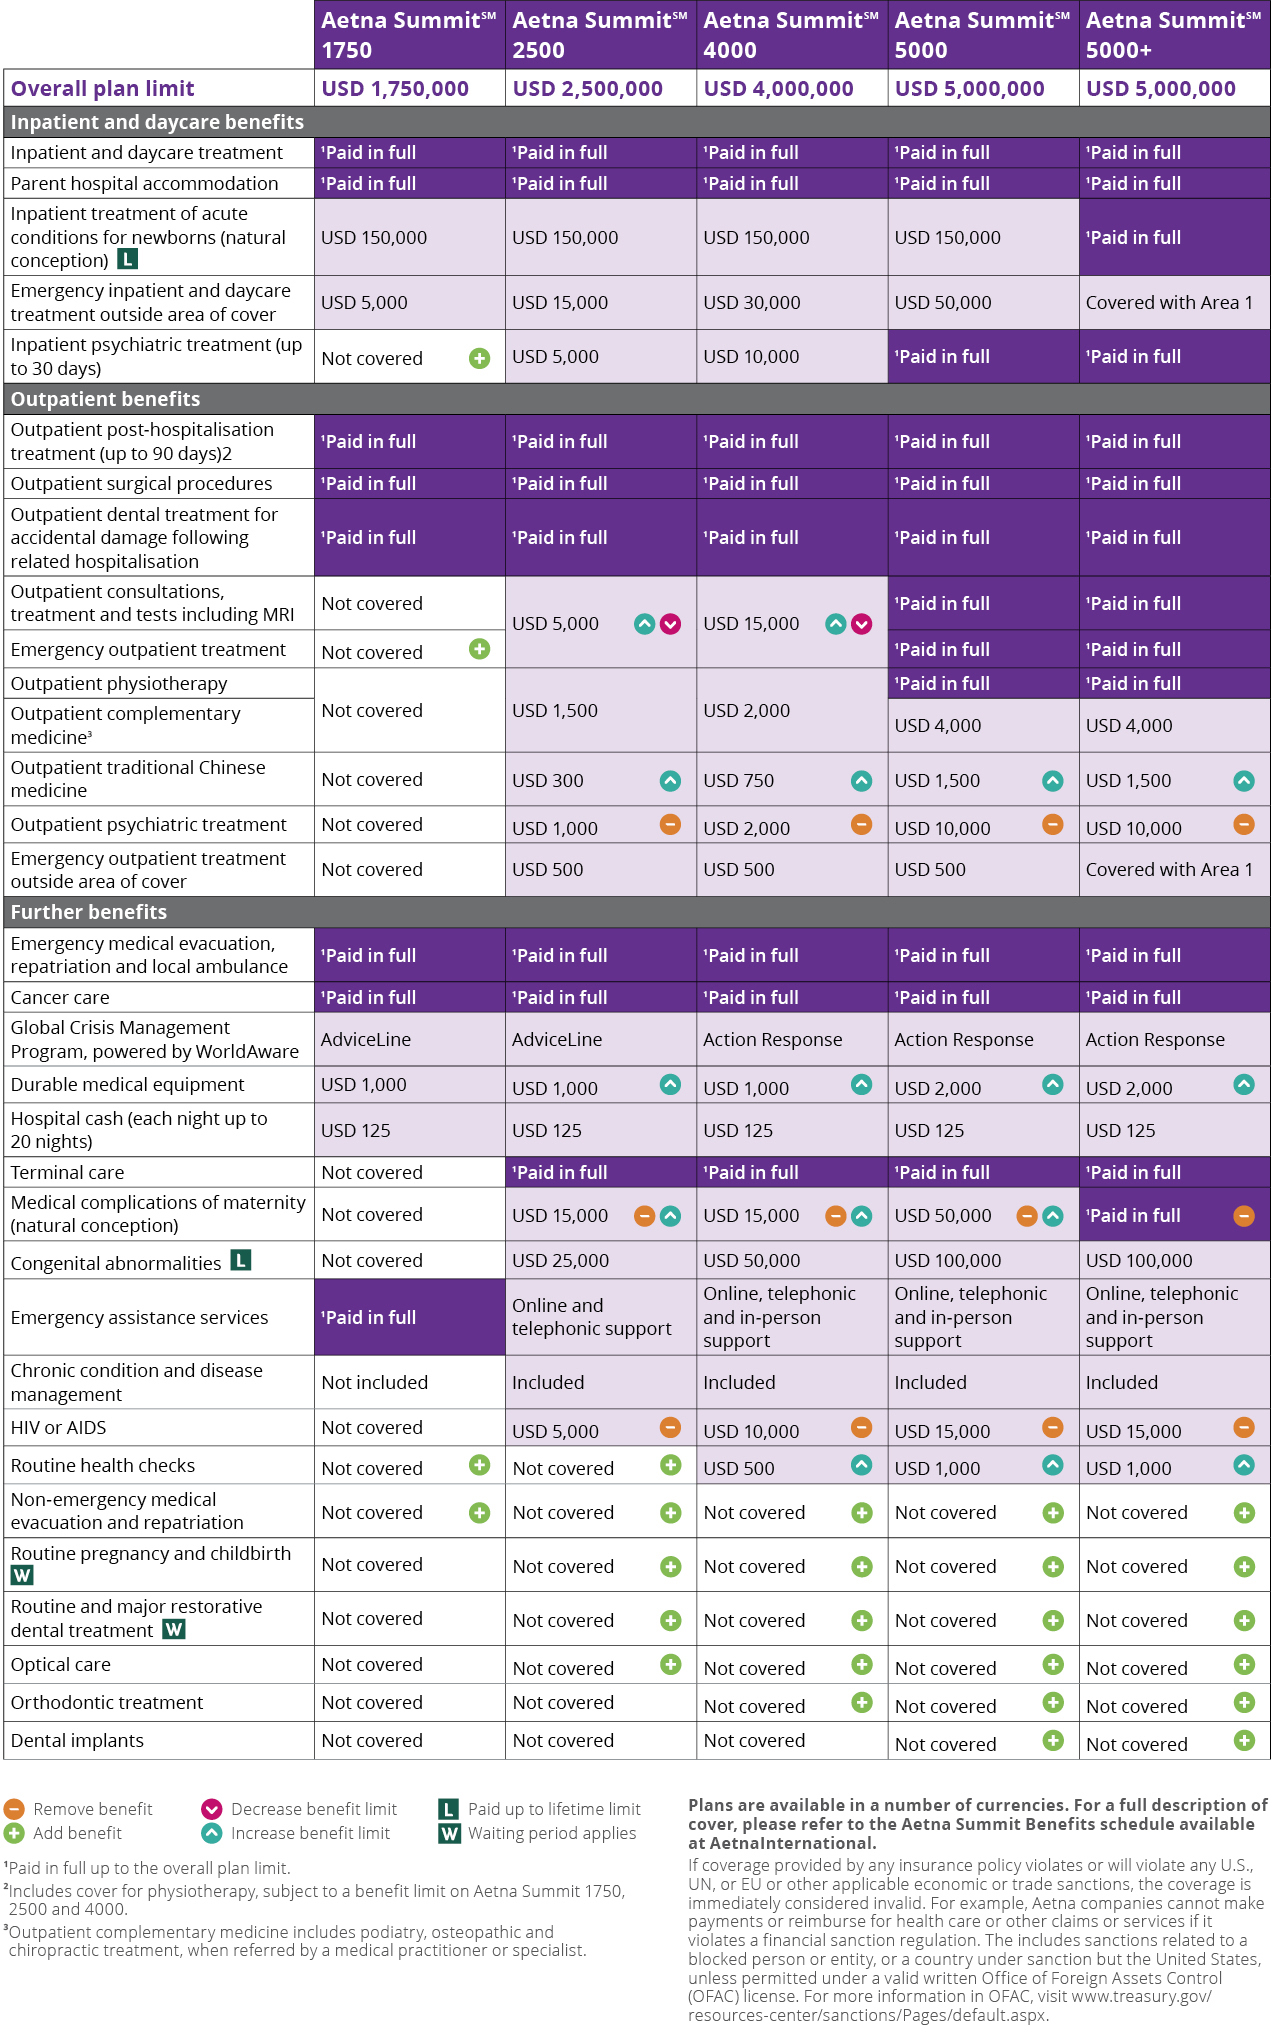
Aetna is one of the larger carriers in the small group health insurance market. Their small business plans generally offer PPO and HMO-style options, along with dental and vision riders. The exact lineup varies by state and employer size, which is usually defined as 1 to 50 employees in most markets. Coverage tiers range from bronze-level high-deductible plans to more comprehensive gold and platinum options. You're looking at medical, pharmacy, mental health, and preventive care as standard components. The enrollment process starts on your state's small business health exchange or directly through an Aetna agent. Most people go through a broker because the paperwork and plan comparisons are annoying to sort alone. You'll need employee demographics, W-2 data for contribution calculations, and a chosen effective date. Employer contributions typically start at 50 percent of premium, though you can go higher if you want to reduce employee costs. Aetna requires a minimum participation rate in many states — usually 70 to 75 percent of eligible employees must enroll. If you fall short, some plans let you still bind coverage but at a higher per-member premium. I ran into a situation a couple years ago where a client had 12 eligible employees but only 6 wanted to enroll. They were stuck below the participation threshold in their state. The workaround was restructuring the employee count by reclassifying a couple of part-timers as non-eligible dependents rather than regular employees, which brought the eligible pool down to 10 and cleared the 70 percent threshold with those 6 enrollments. It was a gray area legally but it worked for their specific situation. Not something to build a strategy around though.
How Aetna Small Business Plans Work in Practice
Once enrolled, claims processing goes through Aetna's provider network. Most small business owners use the Aetna provider directory to check in-network status before referring employees. The directory updates quarterly but there are lag periods where hospitals switch networks and the online data is stale. I've seen this cause surprise out-of-network bills for employees who checked the directory two weeks before a scheduled procedure. The fix is telling employees to verify directly with the provider's billing office, not just relying on the online tool. Prescription drug tiers are where most people get hit unexpectedly. Aetna small group plans typically use a four-tier formulary with generic, preferred brand, non-preferred brand, and specialty categories. Tier 3 and 4 drugs can run $50 to $200 per refill depending on the plan. Some employers don't realize this until someone hits a $3,000 annual pharmacy spend and complains. You can review the formulary during open enrollment and flag high-cost medication categories to your team so they aren't blindsided. Admin fees and brokerage commissions are another thing nobody talks about upfront. Aetna small group policies often have an administrative service fee on top of the premium, ranging from $2 to $8 per member per month depending on how much paperless self-service you set up. Brokers charge commission from the carrier, not the employer directly, but that commission is baked into the premium rate. Shopping multiple carriers simultaneously is worth the effort because the same benefit design can vary by 15 to 25 percent between insurers in the same county.
The portal side is functional but not great. Aetna's employer dashboard lets you run enrollment reports, track participation rates, and process life events. It works fine for basic tasks. The claims status lookup is slower than it should be — you'll usually get a 48-hour lag between when a provider submits a claim and when it shows as processed in the system. If you need real-time adjudication for employee disputes, you'll be waiting. A few brokers I know pull supplemental reports from their EAP provider to fill that gap.
Get the Full Details
Common Pitfalls and What to Watch For
Network narrowing is the biggest risk with any major carrier over time. Aetna has been consolidating hospital systems in several markets, meaning your plan might look good on paper but exclude the hospital three miles from your office. Check the specific network tier your chosen plan uses — some plans only cover certain hospitals while covering all others at a higher cost-share. This matters more if your employees work late and need urgent care access. Rate increases are another practical concern. Aetna small group premiums have trended upward 8 to 12 percent annually in many states over the past few years, driven by medical cost inflation rather than administrative fees. You should budget for at least a 10 percent increase year over year unless you change plan design. Switching to a high-deductible plan with an HSA in year two is the most common cost-control move, but that shifts risk to your employees and can cause morale problems if done abruptly. A gradual shift — like offering a PPO alongside a new HDHP option — softens the transition. Plan terminology changes between renewal cycles can catch people off guard. Aetna sometimes renames plan designs or adjusts benefit parameters without significantly changing the actual coverage structure. This makes direct year-over-year comparison difficult. Request the summary of benefits and coverage document at renewal and compare line items rather than relying on marketing names. The plan labeled "Silver 70" one year might be "Pathway Plus" the next, but the deductible and out-of-pocket maximums tell the real story.
There is no way around it — small business health insurance is bureaucratic and expensive. Aetna is a reasonable option if you value brand recognition and a broad enough provider network, but it's not the cheapest carrier in most markets. For truly budget-constrained employers, considering a QSEHRA or ICHRA arrangement might make more sense than a traditional group plan, especially if your employee base is small and some members already have individual coverage through a spouse or marketplace plan. Those arrangements let you set a fixed annual reimbursement amount instead of underwriting a full insurance policy. If you do go the Aetna route, start the renewal process at least 60 days before your current term ends. Premium quotes lock faster than most people expect, and last-minute rushes often mean accepting the auto-renewal terms without review. That's where the extra 10 percent hit comes from — not rate increases but failure to shop and restructure at renewal time.