Getting From Idea to Cash Flow in African Markets
Most people talk about entrepreneurship like it is a mindset problem. It is not. It is a logistics problem. You can have every positive thought in the world, but if you cannot move goods across a border, process a payment from a mobile wallet, or register a business before the tax authority changes its filing portal again, you are not running a business. You are running a hobby. I spent five years working with small business founders across West and East Africa. The ones who survived did not survive because they had better business plans. They survived because they figured out the system on paper was different from the system on the ground, and they adapted quickly.
African Entrepreneurship And Small Business Development
At its core, this field is about building commercial activity in environments where formal infrastructure is thin. That means everything from banking access to reliable electricity to consistent legal enforcement. The opportunity is enormous because a huge portion of economic activity happens outside traditional channels. The constraint is equally enormous because every transaction carries hidden costs that founders in more stable markets do not face. Small business development in this context involves solving problems that are basic in other regions but treated as optional here. Electricity. Internet connectivity. Payment processing. Supply chain reliability. You deal with all of these before you deal with scaling. The most common mistake is copying a model from Europe or North America and expecting it to work in Lagos, Nairobi, Dakar, or Kampala. The customer behavior is different. The payment preferences are different. The regulatory environment shifts without warning. The people who build businesses that last figure that out early instead of late.
Practical Steps That Actually Work
I am going to walk through the steps in the order they matter, not in the order a textbook would list them. Start with the regulatory side, then move to operations, then to sales, then to funding. Most founders do it backwards. Business registration in Africa varies wildly by country. In Ghana, you can register a business online through the Registrar General's Department and get your name cleared in a few days. In Nigeria, it depends on whether you are registering with the CAC at the federal level or with state authorities, and the timelines change based on which office you walk into. In Kenya, you use eCitizen, which mostly works but occasionally drops submissions during peak hours. Here is what most people miss. Registration alone does not give you legitimacy. You also need a tax identification number, a business bank account, and whichever sector-specific permits apply to your industry. Skip any of these and you will deal with fines or account freezes later. I had a founder in Accra who spent three months getting rejected by banks because he only had his business certificate and not his tax clearance. Banks require both. He lost three months of trying to open an account while his competitors who had paperwork ready moved forward.
Get the Full Details

Step Two: Set Up Payment Infrastructure Early
This is where African business dev gets interesting. Cash is still king in many markets. Mobile money dominates in others. Card payments are growing but remain limited. Your payment setup depends entirely on where you operate and who your customers are. If you are in Nigeria, you need Paystack or Flutterwave, and you need to understand that customers will try to pay via bank transfer even when you offer card options. In Kenya, M-Pesa integration is non-negotiable if you want to reach more than a small segment. In Senegal, Orange Money and Wave compete for dominance and your choice matters depending on your location and customer base. I worked with a supplier in Ibadan who sold industrial parts. He refused to accept mobile money because he thought it looked unprofessional. He also refused card payments through a gateway because the fees seemed high. He took cash and bank transfers only. His conversion rate dropped by about sixty percent compared to competitors who accepted mobile payments. He did not understand that his customers were younger and preferred digital transactions even if they could not afford cards. He lost revenue he did not know he was losing.
The workaround is straightforward. Accept every payment method your market uses. The transaction fees will eat into your margins by three to five percent, but the volume increase usually offsets it. Factor that cost in from day one. Do not treat it as an afterthought.
Step Three: Solve the Electricity and Internet Problem
This sounds absurd to write in a business guide, but it is one of the biggest operational risks. Generator fuel costs in Nigeria can range from forty thousand to one hundred and twenty thousand naira per month depending on your power consumption and local fuel prices. In South Africa, load shedding schedules determine whether your business operates at full capacity or not at all. In Zambia, power outages are frequent enough that every small business owner I know has a backup plan involving either inverters or generators. Internet reliability follows a similar pattern. Fiber is available in major cities but expensive. Mobile data is more accessible but inconsistent. I once watched a founder in Kigali lose an entire day's orders because her ISP went down and she had no 4G backup. Her orders were coming through WhatsApp. No internet meant no orders. She now maintains a secondary SIM from a different provider on her router at all times. The solution is redundancy. Budget for backup power and backup connectivity from the start. It will cost you ten to twenty percent more in overhead than a business in a stable infrastructure market. That is the cost of operating here. Plan for it or fail because of it.

Step Four: Understand Distribution Without a Distribution Network
African markets are not served by reliable last-mile logistics the way European or American markets are. Delivery companies exist in major cities but coverage is patchy. Informal delivery networks fill the gap, and they vary in quality. If you are selling products, you need a distribution strategy that accounts for this reality. In Nigeria, motorcycle riders and bicycle couriers handle a surprising amount of last-mile delivery. In Rwanda, bike delivery is well organized in Kigali but disappears the moment you leave the capital. In Tanzania, you deal with informal transport networks that move goods between towns but do not deliver to doorsteps reliably. I advised a food business in Lagos that tried to use a single courier service for the entire city. They failed because that service only covered Lagos Island and part of mainland Lagos. Orders to Ikeja and Ikorodu were delayed or lost. They switched to a multi-courier model using different providers for different zones and their on-time delivery rate improved from sixty-two percent to ninety-one percent within six weeks. The coordination required more management time, but the improvement in customer satisfaction and repeat orders more than compensated.
Step Five: Funding Does Not Look What You Think It Looks Like
Traditional venture capital in Africa is concentrated in a handful of countries and a handful of sectors. Most small businesses never access VC funding. That does not mean funding is unavailable. It means you need to know where to look. Microfinance institutions operate in almost every country. They charge higher interest rates than commercial banks, often between fifteen and thirty percent annually, but they approve loans faster and require less paperwork. In Ghana, there are cooperative societies andesus systems that provide small business credit through community networks. In Ethiopia, cooperative banks serve rural and semi-urban entrepreneurs who would be invisible to commercial lenders. Grant programs from development organizations exist but are competitive and slow. USAID, the African Development Bank, and various EU-funded programs all run small business support initiatives. The application process can take four to eight months from start to disbursement. If you need capital within sixty days, grants are not the answer.
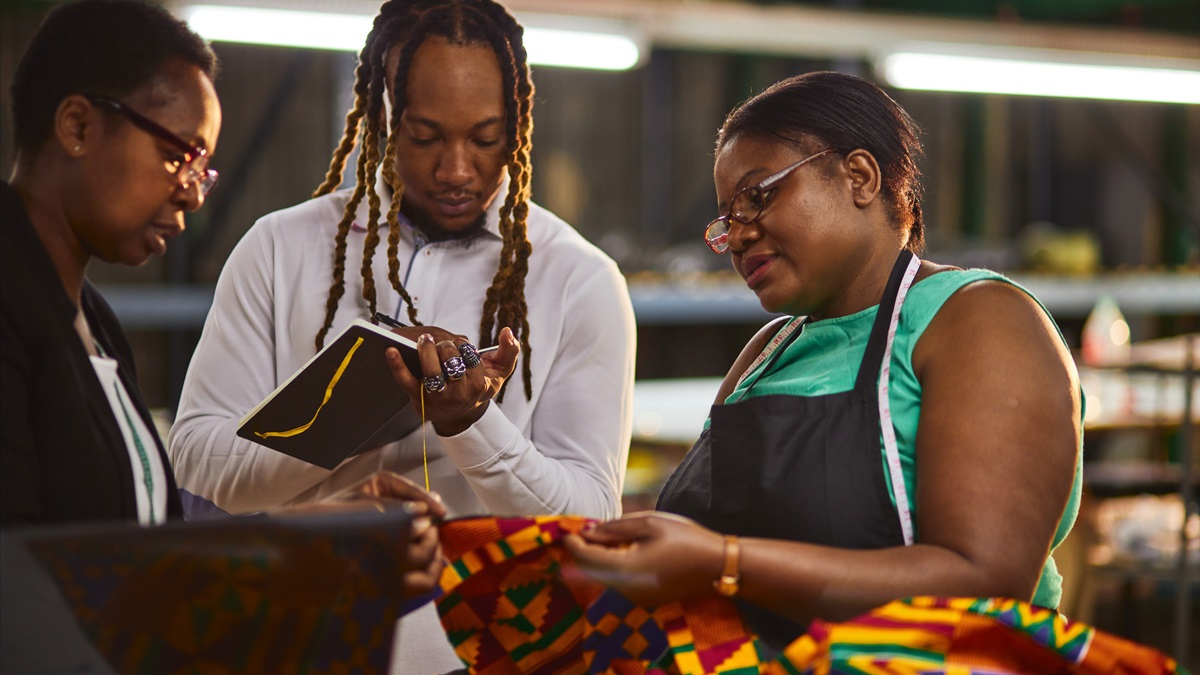
I recommended a textile manufacturer in Kumasi apply for a grants program when they needed working capital within three months. They missed a crucial shipment deadline because the grant money had not arrived. They should have taken a microfinance loan instead. The interest was higher, but the money was available immediately. They learned to match the funding source to the urgency rather than optimizing for cost alone.
Counter-Intuitive Insights That Save Businesses
There are two things most beginners miss that experienced operators take for granted. The first is that informal competition is often stronger than formal competition. You will spend time analyzing registered businesses in your sector and concluding that your differentiation is clear. Then you realize the real competition is the unregistered operator next door who sells the same product at thirty percent less because they do not pay taxes, do not have a shop, and do not follow quality standards that cost money to maintain. Your formal advantages become liabilities when price is the primary decision factor for your customers. The workaround is to compete on something other than price or to find a niche where quality matters more than cost. The second is that customer acquisition in Africa often happens through trust networks, not advertising. Instagram ads can work for certain demographics in urban areas, but word of mouth, family referrals, and community recommendations drive a disproportionate amount of business. I once saw a hair salon in Abuja grow from two clients per day to twelve clients per day without spending a single naira on advertising. The owner simply ensured every customer left satisfied enough to tell three other people. The growth took fourteen weeks. It was slower than paid advertising might have been, but the customers acquired through referrals had higher retention and higher lifetime value than any paid channel produced for them later.
When Things Break
I need to be honest about the scenarios where this approach does not work. It fails in markets with extreme currency volatility. It fails where regulatory capture is severe and business success depends on connections rather than execution. It fails when the addressable market is too small to sustain any business model beyond subsistence. It fails when you underestimate the time required to navigate bureaucratic processes. Some of these conditions are unavoidable. You need to assess them honestly before committing resources. If you are operating in a country with annual inflation above fifty percent, your pricing strategy needs to account for currency erosion on a weekly basis, not monthly. If the regulatory environment requires approvals that can be withheld arbitrarily, you need legal representation and contingency planning that goes beyond standard business practice. The businesses that survive are not the ones with the best ideas. They are the ones that understand the actual operating environment, plan for its failures, and adapt faster than the environment changes around them.
That is the practical reality of African entrepreneurship and small business development. Not inspiring. Not dramatic. Just a series of logistical challenges that require specific, grounded solutions.