Building Algo Trading Systems That Actually Work
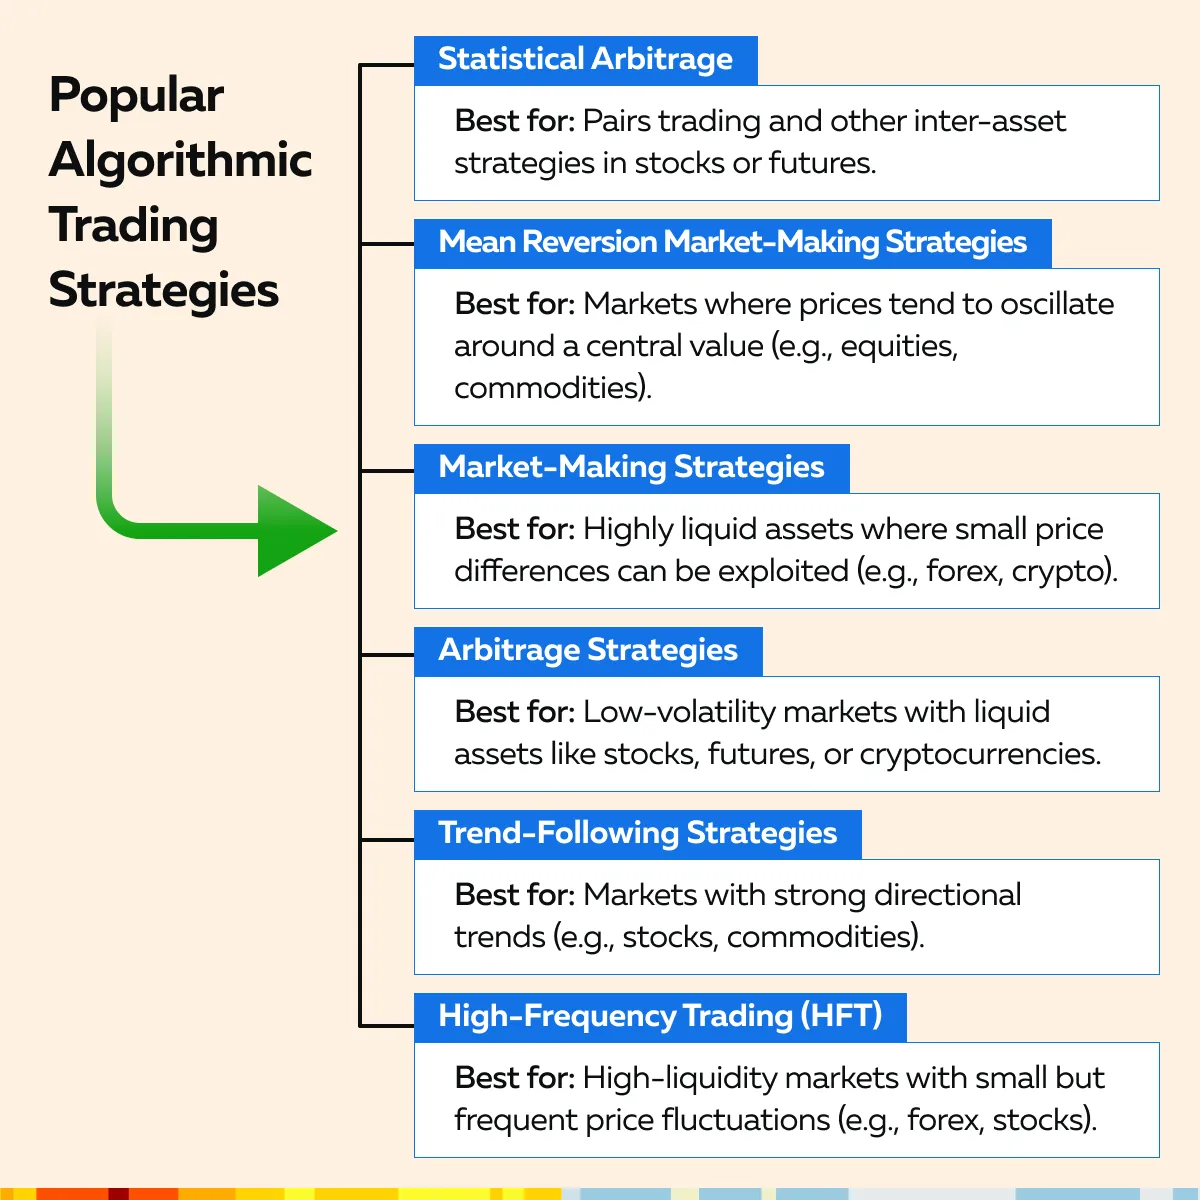
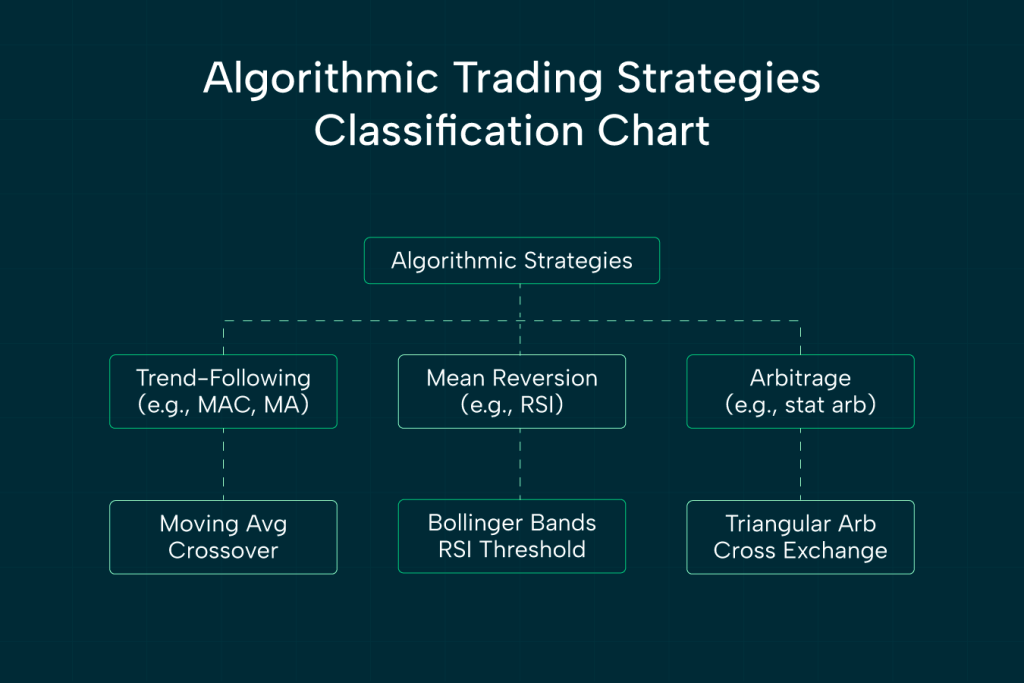
Most people build algo trading systems that blow up. Not because the math is wrong, but because they skip the boring parts. I learned that the hard way back in 2019 when a strategy I was proud of lost 40% of its paper trading capital in three weeks. The bug wasn't in the entry logic. It was in the exit logic, specifically how slippage and partial fills were handled during a flash crash event. The system tried to exit all at once, got filled at wildly different prices across multiple orders, and the P&L calculation came out wrong because I hadn't accounted for execution latency between individual fill reports. Let's get the definitions out of the way after I've already shown you what goes wrong. The main categories you'll run into are trend following, mean reversion, statistical arbitrage, market making, and momentum strategies. Each has a different risk profile and each fails in different market conditions. Trend following works great in strong directional moves but bleeds slowly in choppy sideways markets. Mean reversion is the opposite, it makes money in ranges and gets slaughtered during breakout events. The market structure dictates which strategy survives. I've seen beginners stack these together into some Franken-strategy that supposedly hedges all scenarios. It doesn't work that way. The correlations between these strategies shift unpredictably, especially during stress periods. You end up with something that looks diversified on paper but actually concentrates all your risk in one hidden factor. That's what happened to a friend of mine who ran three independent strategies, all of them implicitly betting on low volatility. When VIX spiked to 40 in March 2020, all three drew down simultaneously. He learned that diversification without factor analysis is just optimism.
How to Build One Properly
Start with the data, not the strategy. That's where most people get it backwards. They find a pattern they like, then go looking for data to validate it. That's curve fitting, and it will cost you money. Pull raw historical data from a reliable source, tick-level if possible, and understand its limitations before you write a single line of code. Gaps in the data, survivorship bias in equity lists, corporate action adjustments that aren't properly applied. These will bite you later. I spent two weeks last year debugging why my backtest results looked suspiciously good compared to live performance. The issue was that the data provider adjusted historical prices for splits and dividends retroactively, but the timestamps on those adjustments were inconsistent. Some dates had delayed updates while others were correct. The strategy was essentially trading on look-ahead biased data for about 8% of the simulation period. Fixing the data pipeline took a full day, and once I did, the backtest returns dropped by roughly 30%. That's the reality of rigorous data hygiene. After you clean the data, you define the strategy logic. This means writing out every rule in plain English first. Not pseudocode, not Python, just sentences. "Enter long when the 20-period moving average crosses above the 50-period moving average, provided volume is above the 20-day average volume. Exit when the cross reverses or when the position is up 3% or down 1.5%, whichever comes first." The more specific you are, the less ambiguity there is when you code it. Ambiguity is where implementation error lives.
Execution and Infrastructure
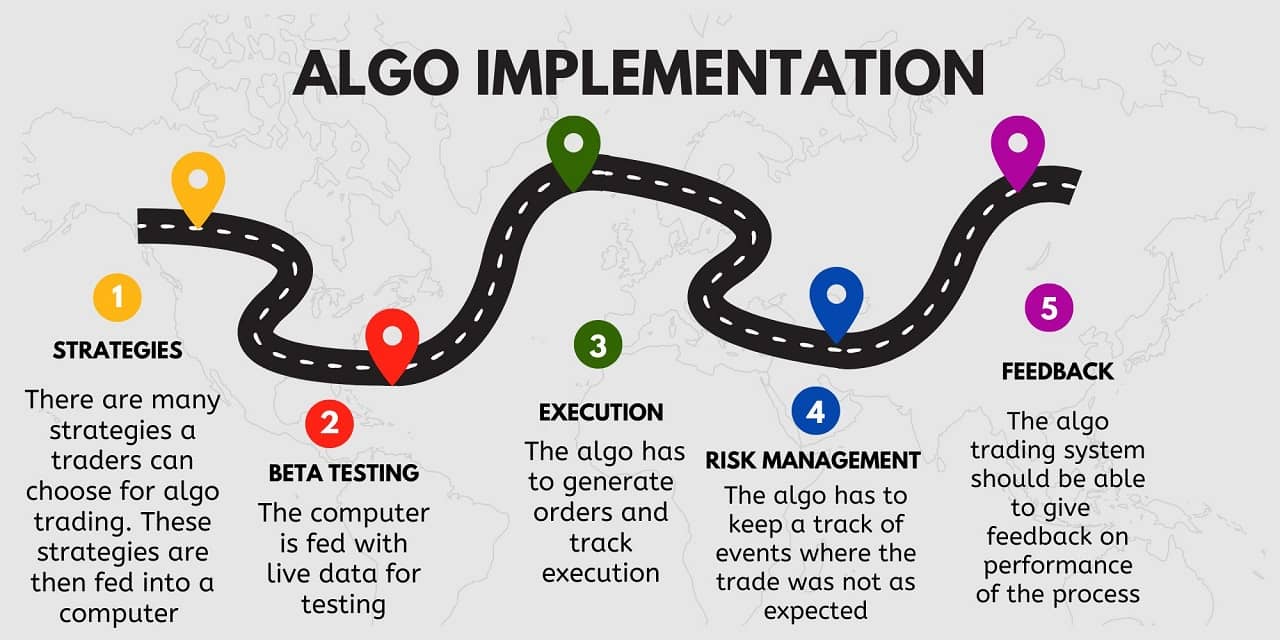
This section is what separates people who stay profitable from the rest. Your strategy might be sound, but if your execution infrastructure is slow or buggy, it won't matter. You need a reliable connection to your broker's API, a local or cloud-based server to run the bot 24/7, and error handling for every possible failure mode. Network timeout. API rate limit exceeded. Partial order fill. Connection drop during market hours. Write handlers for all of them. I recommend starting with a paper trading account attached to your live code. Don't write separate code for paper and live. Use a configuration flag to switch between them. I've seen too many traders maintain two codebases, update one, forget the other, and then deploy a broken live version. One codebase, one strategy, different environment configs. It keeps things simple. For order management, implement a retry mechanism with exponential backoff for failed orders. Set hard timeouts on order acknowledgment. If your broker doesn't confirm an order within a reasonable window, cancel it and reassess. During high volatility periods, brokers get sluggish, and leaving a potentially bad order hanging is worse than canceling and submitting a fresh one.
Get the Full Details

Backtesting Realities
Backtesting is necessary but deeply flawed. Every backtest makes assumptions about transaction costs, slippage, liquidity, and market impact. If you ignore these, your results will be fiction. I use a minimum slippage model of one tick for liquid instruments and two to three ticks for less liquid ones. Transaction costs should include both the spread and any commission. For futures, include the exchange and clearing fees. For equities, factor in the SEC fee and FINRA TRF charge if applicable. Walk-forward testing is the closest thing to a validation method I trust. You optimize on a rolling window of historical data, then test the optimized parameters on the out-of-sample period immediately following. Repeat across multiple windows. If the strategy performs consistently well out-of-sample, you have some confidence. If performance degrades sharply outside the optimization window, the strategy is overfit. I typically use a 60/40 in-sample to out-of-sample split with a minimum of five to ten walk-forward periods. Monte Carlo simulation on your trade sequence is another tool I use. It shuffles your actual trades randomly and generates thousands of possible equity curves. This tells you the worst-case sequence of losses your strategy could experience. It's not about predicting the future, it's about understanding the distribution of possible outcomes. A strategy that looks great in a standard backtest might have a 15% chance of a 50% drawdown when you account for trade sequence variance. That changes whether you can actually deploy it with real money.
Common Pitfalls
Over-optimization is the most common mistake. When you tune parameters to fit historical data too closely, you're optimizing for noise, not signal. A good rule of thumb is to keep the number of parameters below one-tenth of the number of observations in your backtest. If you have 1,000 trades in your backtest, don't optimize more than ten parameters. Fewer is better. Another pitfall is ignoring regime changes. Markets evolve. Volatility clusters, correlations shift, liquidity conditions change. A strategy that worked in a low-volatility bull market may fail in a high-volatility environment. I handle this by including regime filters in my strategies, things like volatility bands or trend strength indicators that reduce position size or pause trading when conditions move outside the strategy's comfort zone. This isn't about predicting the future, it's about not running a flat-earth strategy in a round-earth world. Liquidity risk is often overlooked by retail traders. A strategy might show excellent returns in backtest, but in practice, you can't enter or exit at the prices the backtest assumes. During normal conditions, this might cost you a few basis points per trade. During stressed conditions, it could be 50 basis points or more, or you might simply not be able to exit at all. If you're trading small-cap stocks or obscure futures contracts, this is a real concern. Paper trading under realistic assumptions helps you feel this before it costs you real money.
A Practical Starting Point
If you're new to this, start with a simple moving average crossover on a liquid instrument like ES futures or SPY. Paper trade it for at least three months. Track every trade manually in a spreadsheet alongside your bot's trades. Compare the two. Look for discrepancies in fills, timing, and P&L. This exercise alone will teach you more about the gap between theory and practice than any course or YouTube video. My initial attempt at this took me about four weeks to get working reliably, mostly because I didn't account for the timing difference between when my strategy generated a signal and when the broker actually filled the order. Resources for getting started are plentiful. Python with libraries like backtrader, QuantConnect, or zipline covers most needs for backtesting and execution. Many brokers offer APIs, Interactive Brokers being one of the most common choices among retail algo traders. Their API documentation is thorough, though the learning curve is steeper than some alternatives. For futures specifically, NinjaTrader has a solid development environment with decent community support. I'd recommend sticking to one platform until you're comfortable, then expanding. The bottom line is that algo trading is a technical discipline that requires patience. The strategies themselves are rarely the hard part. Building robust systems that handle the messy realities of live markets, monitoring them continuously, and knowing when to shut them down are the actual skills. I still check my strategies manually every day, even the ones that have been running profitably for months. Complacency is how you lose what you've built.