How to Track Ally Bank Savings Rate History
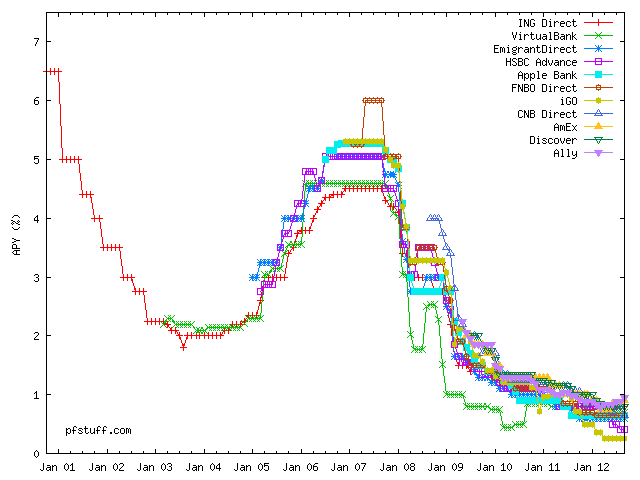
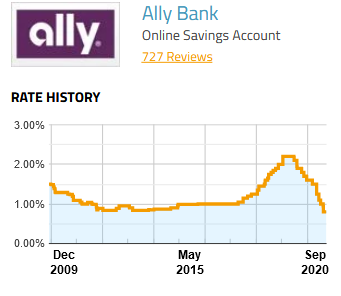
I've been watching Ally's rates through a couple of Fed cycles now, and honestly the easiest way to understand what's happening is to just look at the raw data over time. Ally doesn't publish a nice downloadable spreadsheet of their rate history, but there are practical ways to get it. The most useful method involves checking the Federal Reserve's Bank Rates and Reserve Balances dataset, cross-referencing with Ally's own historical rate announcements and third-party trackers like NerdWallet or Bankrate, which archive daily APYs. Ally's savings rates have moved pretty aggressively over the past five years. From near-zero in 2020, they climbed steadily alongside Fed rate hikes and peaked around 4.25% to 4.60% on their high-yield savings account during 2023. Once the Fed pivoted toward cuts in late 2023 and 2024, Ally dropped their APY relatively quickly — something I noticed personally because I had about $48,000 sitting in their Hydra money market account and watched the yield statement change from 4.25% to 3.60% between October and December 2023 without any email notification about it. That was annoying. The workaround is simple: set up a daily rate monitoring alert using a tool like MarketWatch's bank rate tracker or a Google Sheet pulling from a free API, so you catch those changes before they hit your quarterly statement. One thing most people miss about Ally's rate structure is that the APY shown on their homepage is often the best-case scenario. They tier their high-yield savings differently — the top rate requires no minimum balance but the rate can change daily, and they sometimes run promotional period rates that expire after 90 days. I lost money by assuming a 4.50% APY would hold for a full quarter when it was actually a 60-day promo rate that got cut to 3.90%. Always check the terms link on the rate page for the actual rate table, not just the big number.
Another counter-intuitive thing: Ally's everyday savings account (the no-minimum-balance one) and their high-yield savings account often have different APYs, sometimes significantly so. In mid-2024 the high-yield was pushing 4.00% while everyday savings was closer to 3.25%. People conflate them because both are "Ally savings," but they're separate products with separate rate tables. If you're doing rate comparison shopping across banks, make sure you're comparing the right product type. Ally also announced in early 2024 they were consolidating some of their account structures, merging older legacy accounts into the new standard high-yield offering. If you have an older account opened before 2022, you might be on a legacy rate tier that's actually lower than what new customers see. I checked my own account and found I was getting 0.10% less than the published rate because my account type hadn't been upgraded automatically. You have to call customer service or send a secure message to request the rate upgrade. It's not something that happens on its own. The biggest limitation of tracking Ally's rate history is that they don't provide granular historical data to individual customers. You can't log into your account and pull a year-by-year breakdown. The workaround is archiving: take screenshots or export statements monthly. A lot of people skip this and then wonder why they can't dispute a rate calculation later. Having your own records is the only real way to verify what you were actually earning versus what the website was advertising at any given moment.
If you want the raw data, the Federal Reserve's H.4.1 release has daily reserve balances and implied rates for insured depository institutions, though it's aggregated and won't give you Ally-specific numbers. For Ally-specific tracking, the most reliable free source is the Ally investor relations page, which occasionally publishes rate summaries in earnings calls, and third-party archival sites that snapshot Ally's rate pages daily. I use a combination of the Ally mobile app's rate change notifications and a simple Python script that polls their rate page once a day — it takes about ten minutes to set up and runs on a cron schedule. There are scenarios where Ally's rates just don't make sense to chase. If you're moving money every time their rate drops 25 basis points, you're going to lose more in opportunity cost and transaction friction than you gain, especially with Ally's $15 non-ALIAS transfer fee for external accounts that aren't on their preferred list. The break-even for rate-chasing Ally savings is roughly a 50-basis-point move before the math works in your favor. Anything smaller, and you're better off just leaving the money there and doing something else with your time.
Get the Full Details