Navigating Medicare Supplement Rate Hikes Without Losing Your Mind
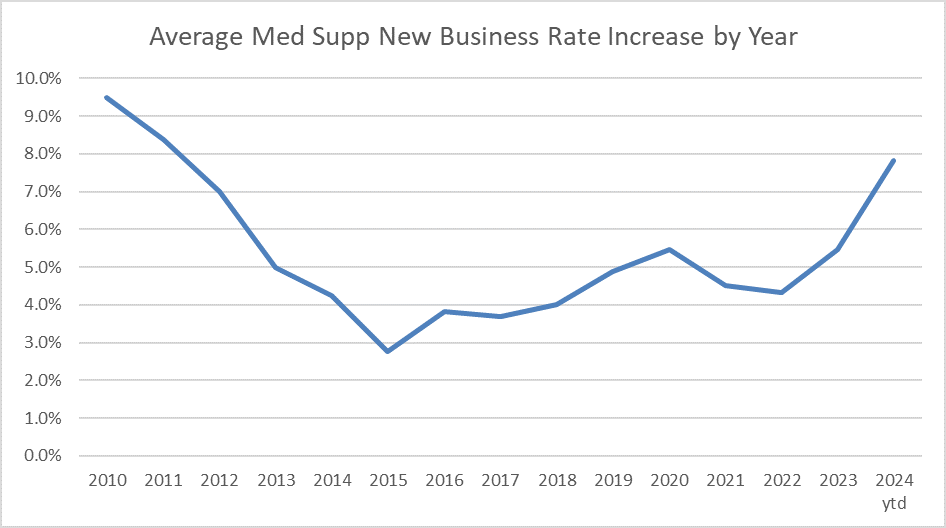
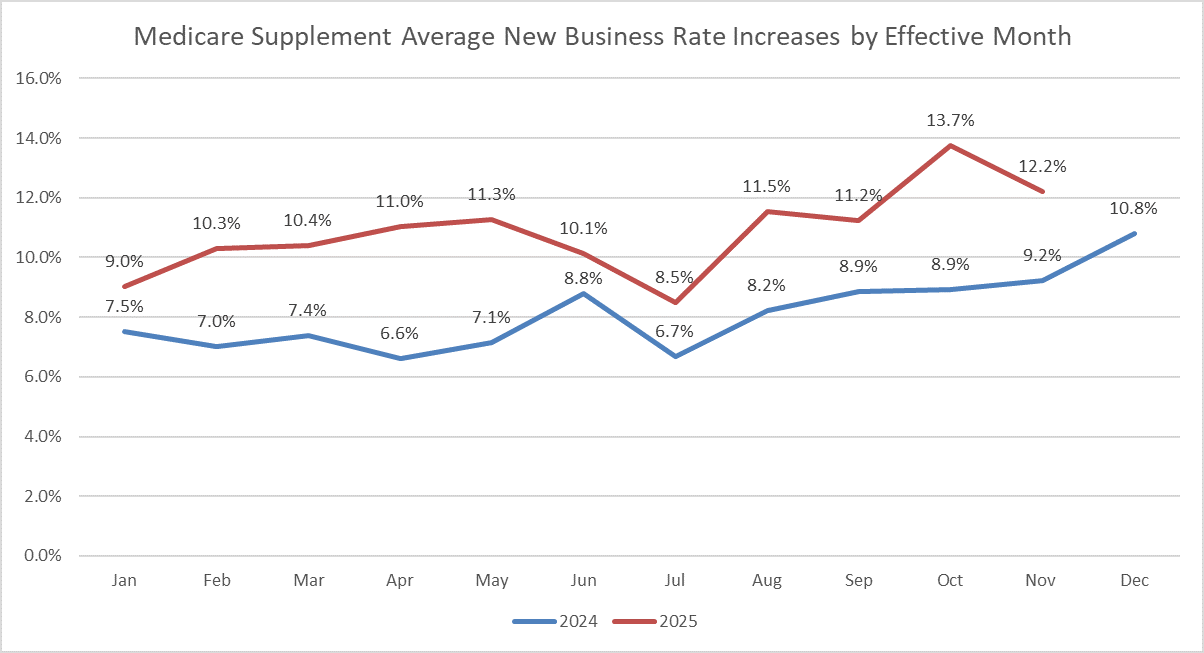
Most people don't realize their Medicare Supplement (Medigap) premiums can jump significantly from one year to the next. The American Medicare Supplement Rate Increase History is something that matters enormously once you're actually living through it. I deal with this all the time, and the confusion around how these rates are calculated and projected is the kind of thing that burns clients and agents alike. Let me break down what's actually going on and how to work with it. Medigap plans are standardized by the federal government — Plan G in Texas is basically the same coverage as Plan G in Maine. But the premiums? Those vary wildly and are set by individual insurance carriers. When you look at an American Medicare Supplement Rate Increase History for a specific plan, you're looking at a company's track record of how much they've raised prices over time. This is different from Original Medicare, which gets federal adjustments. Medigap rate history is purely carrier-driven.American Medicare Supplement Rate Increase History: What You Actually Need to Know
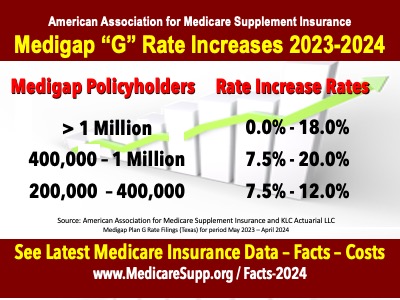
There's a critical distinction most people miss. Insurance companies use one of three rating methods, and it completely changes what your rate history will look like. Attained-age pricing means your premium is based on your current age. Every year, as you get older, your rate goes up. The American Medicare Supplement Rate Increase History for an attained-age policy will show a steady, predictable climb. A 65-year-old might pay $120 for Plan G, and by 75 that could be $220 or more. The increases are baked into the system. You signed up knowing this. It's not aggressive — it's structural. Issue-age pricing locks in your rate based on your age when you first bought the policy. Your premiums still increase annually due to inflation and medical cost trends, but they won't spike just because you aged. The rate history here looks flatter in the early years and then begins to accelerate as the insured population gets older collectively. I've seen this trip people up because they assume issue-age means frozen premiums. It doesn't. It just means age-related spikes aren't part of the equation. Community-rated pricing charges everyone the same premium within a state regardless of age. This is rare for Medigap — most states don't allow it — but when you find it, the rate history looks very flat across all ages. The annual increases are driven purely by medical inflation, usually in the 3 to 7 percent range. Here's where it gets practical. If you're comparing policies and one has a lower starting premium but uses attained-age pricing, while another costs more upfront but uses issue-age, the attained-age policy can overtake it in total cost within five to seven years. I had a client last year who almost signed a deal with a carrier that advertised $89 per month for Plan G. I pulled their actual rate history for the past eight years and showed them that same policy was at $147 the next year and tracking toward $200 by year four. The issue-age competitor at $112 started was projected to be around $138 at that same four-year mark. The upfront savings was a bait switch.To dig into real rate history data, you need to go directly to the carriers. State insurance departments sometimes publish aggregate data, but it's usually lagged by a year and grouped broadly. The most useful approach is to request a formal illustration from at least two carriers for the same plan type. Ask specifically for a table showing projected premiums at years one through ten, and ask them to disclose the rating method. Legitimate agents will have this available. If someone hesitates or can't produce a clear comparison, that's a red flag worth walking away from. Another thing nobody talks about enough is that carriers can and do increase rates across entire policyholder classes, not just for individuals. A "rate adjustment" can apply to everyone who holds Plan G with that company in your state, regardless of when they signed up. I've seen single-year increases of 12 to 18 percent in states like Florida and Arizona during periods of high medical inflation. This is legal and allowed under your policy contract, but most people don't read the fine print about it. When you're evaluating a carrier's history, look for clusters of large general rate hikes — that tells you the company is aggressive about adjusting premiums across the board, not just for aging individuals.