Why most amortisation schedules you find online are useless for actual accounting
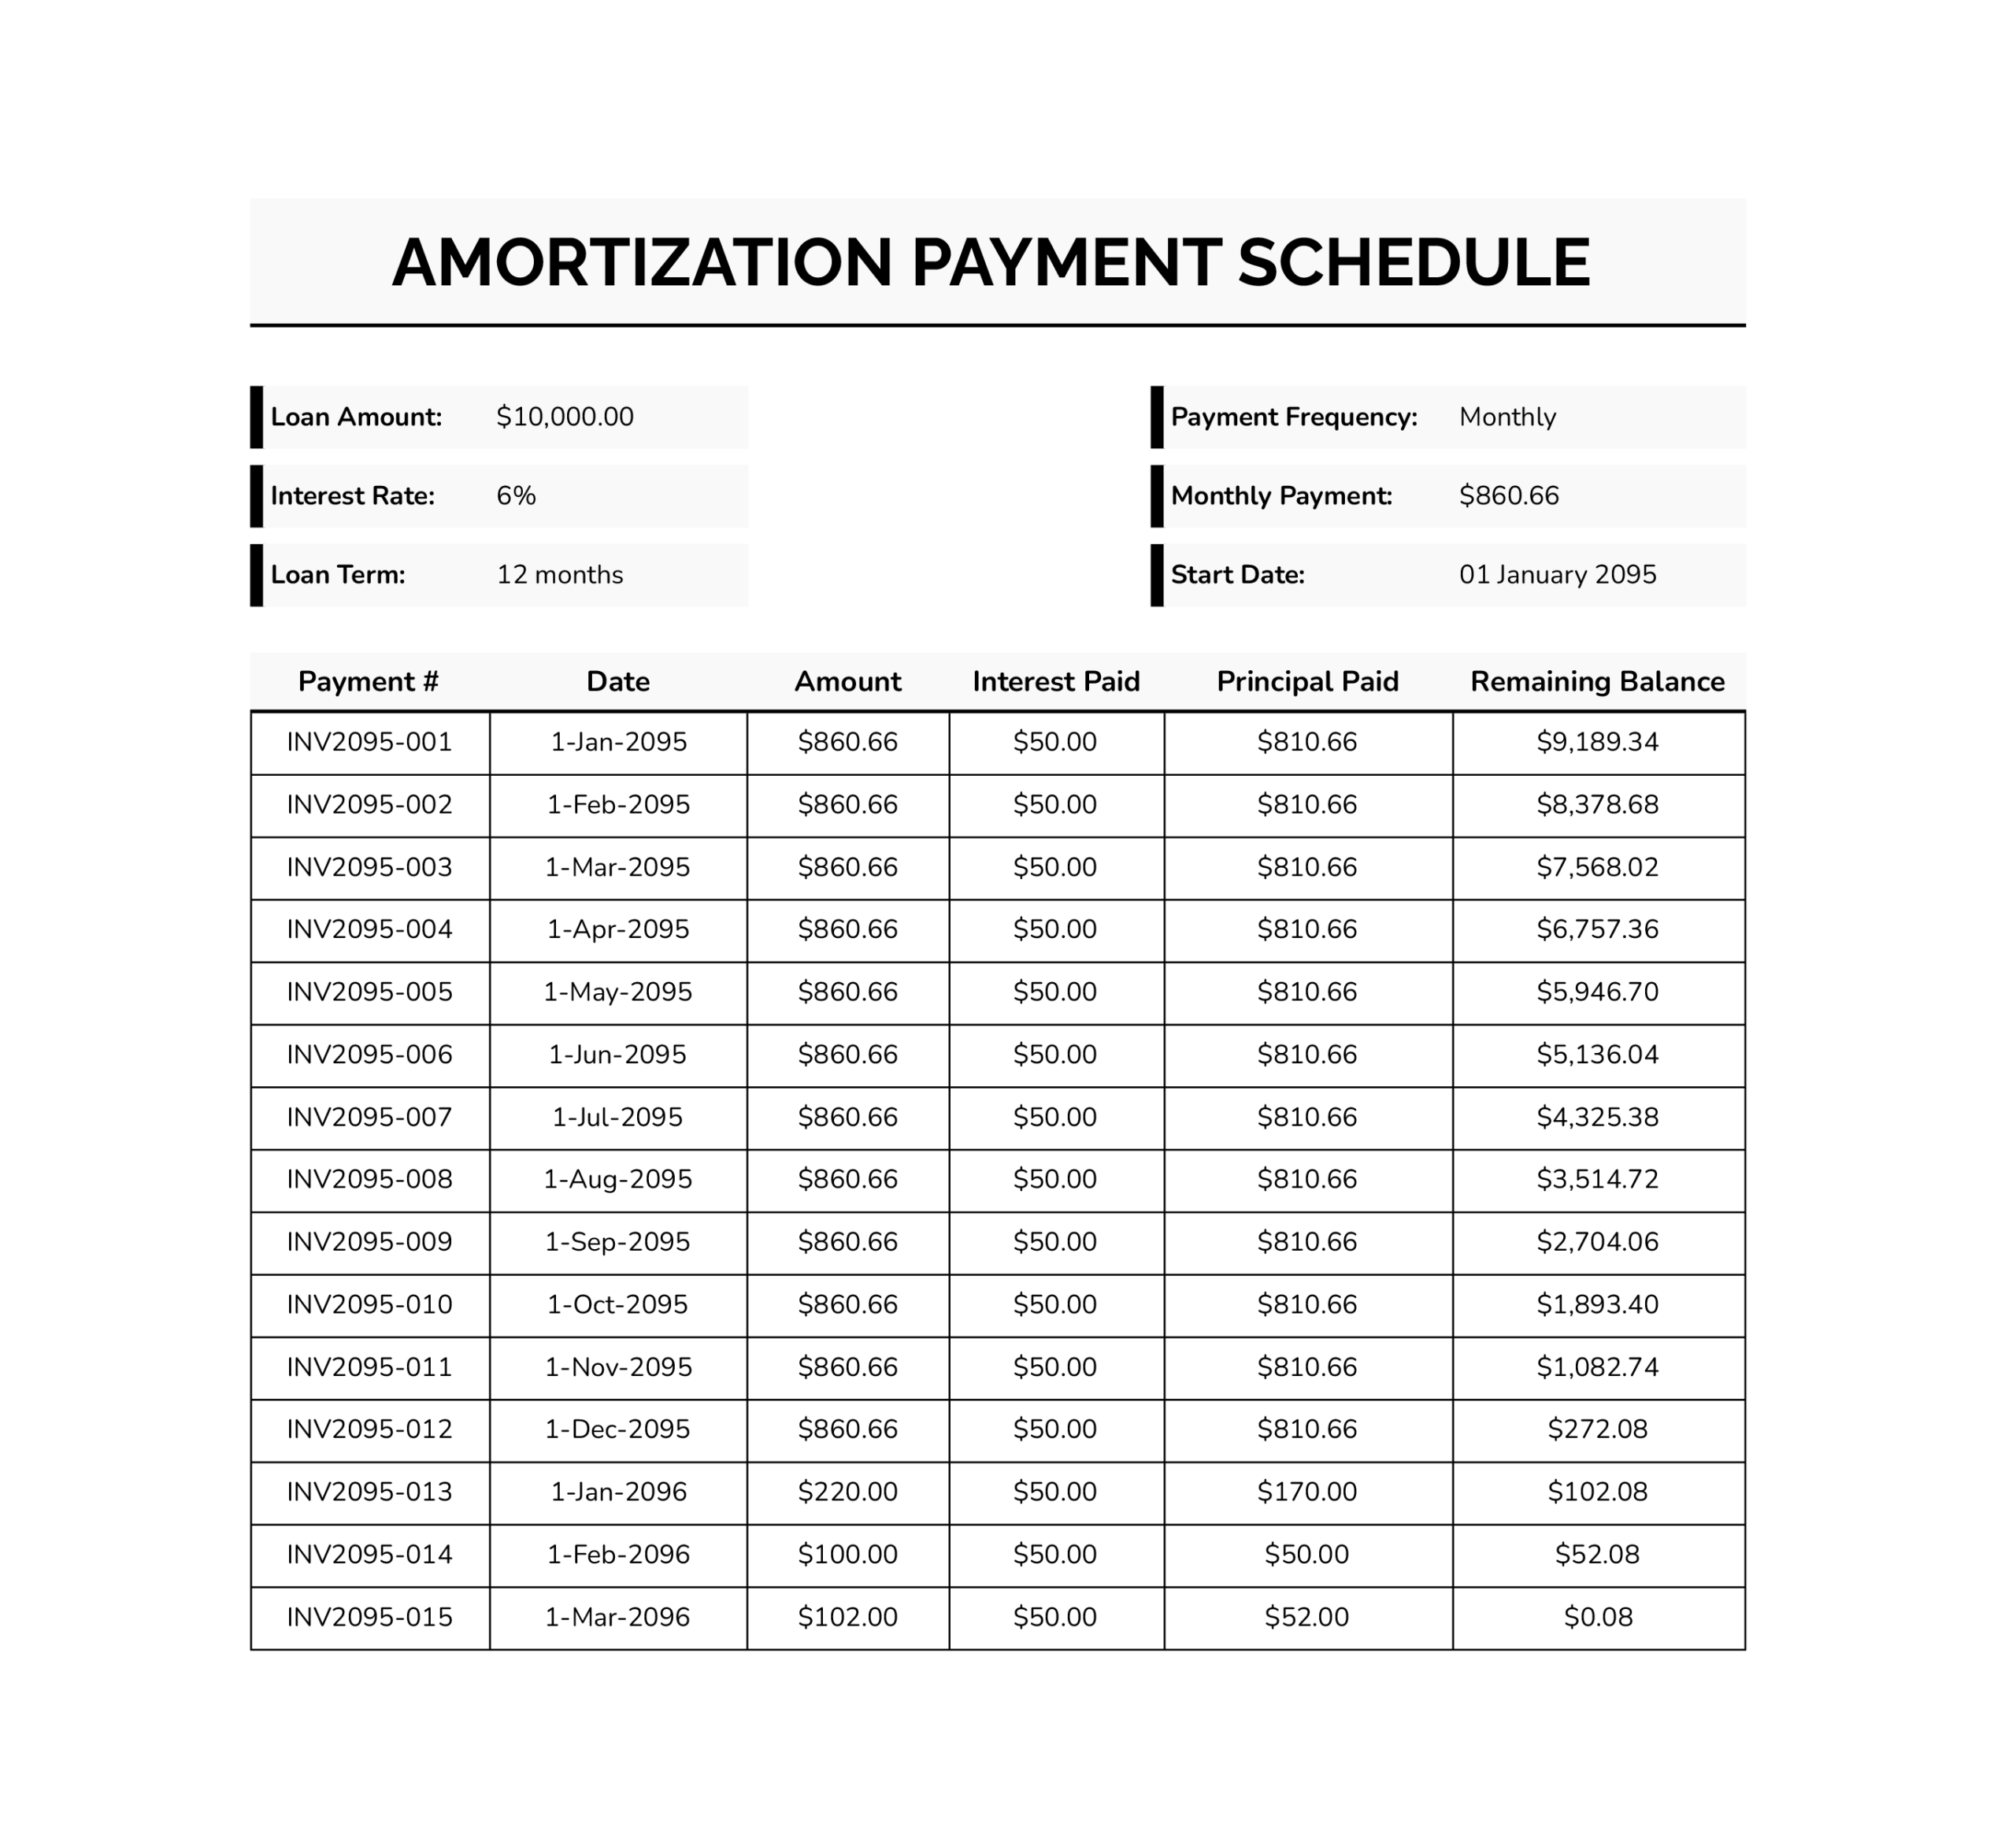
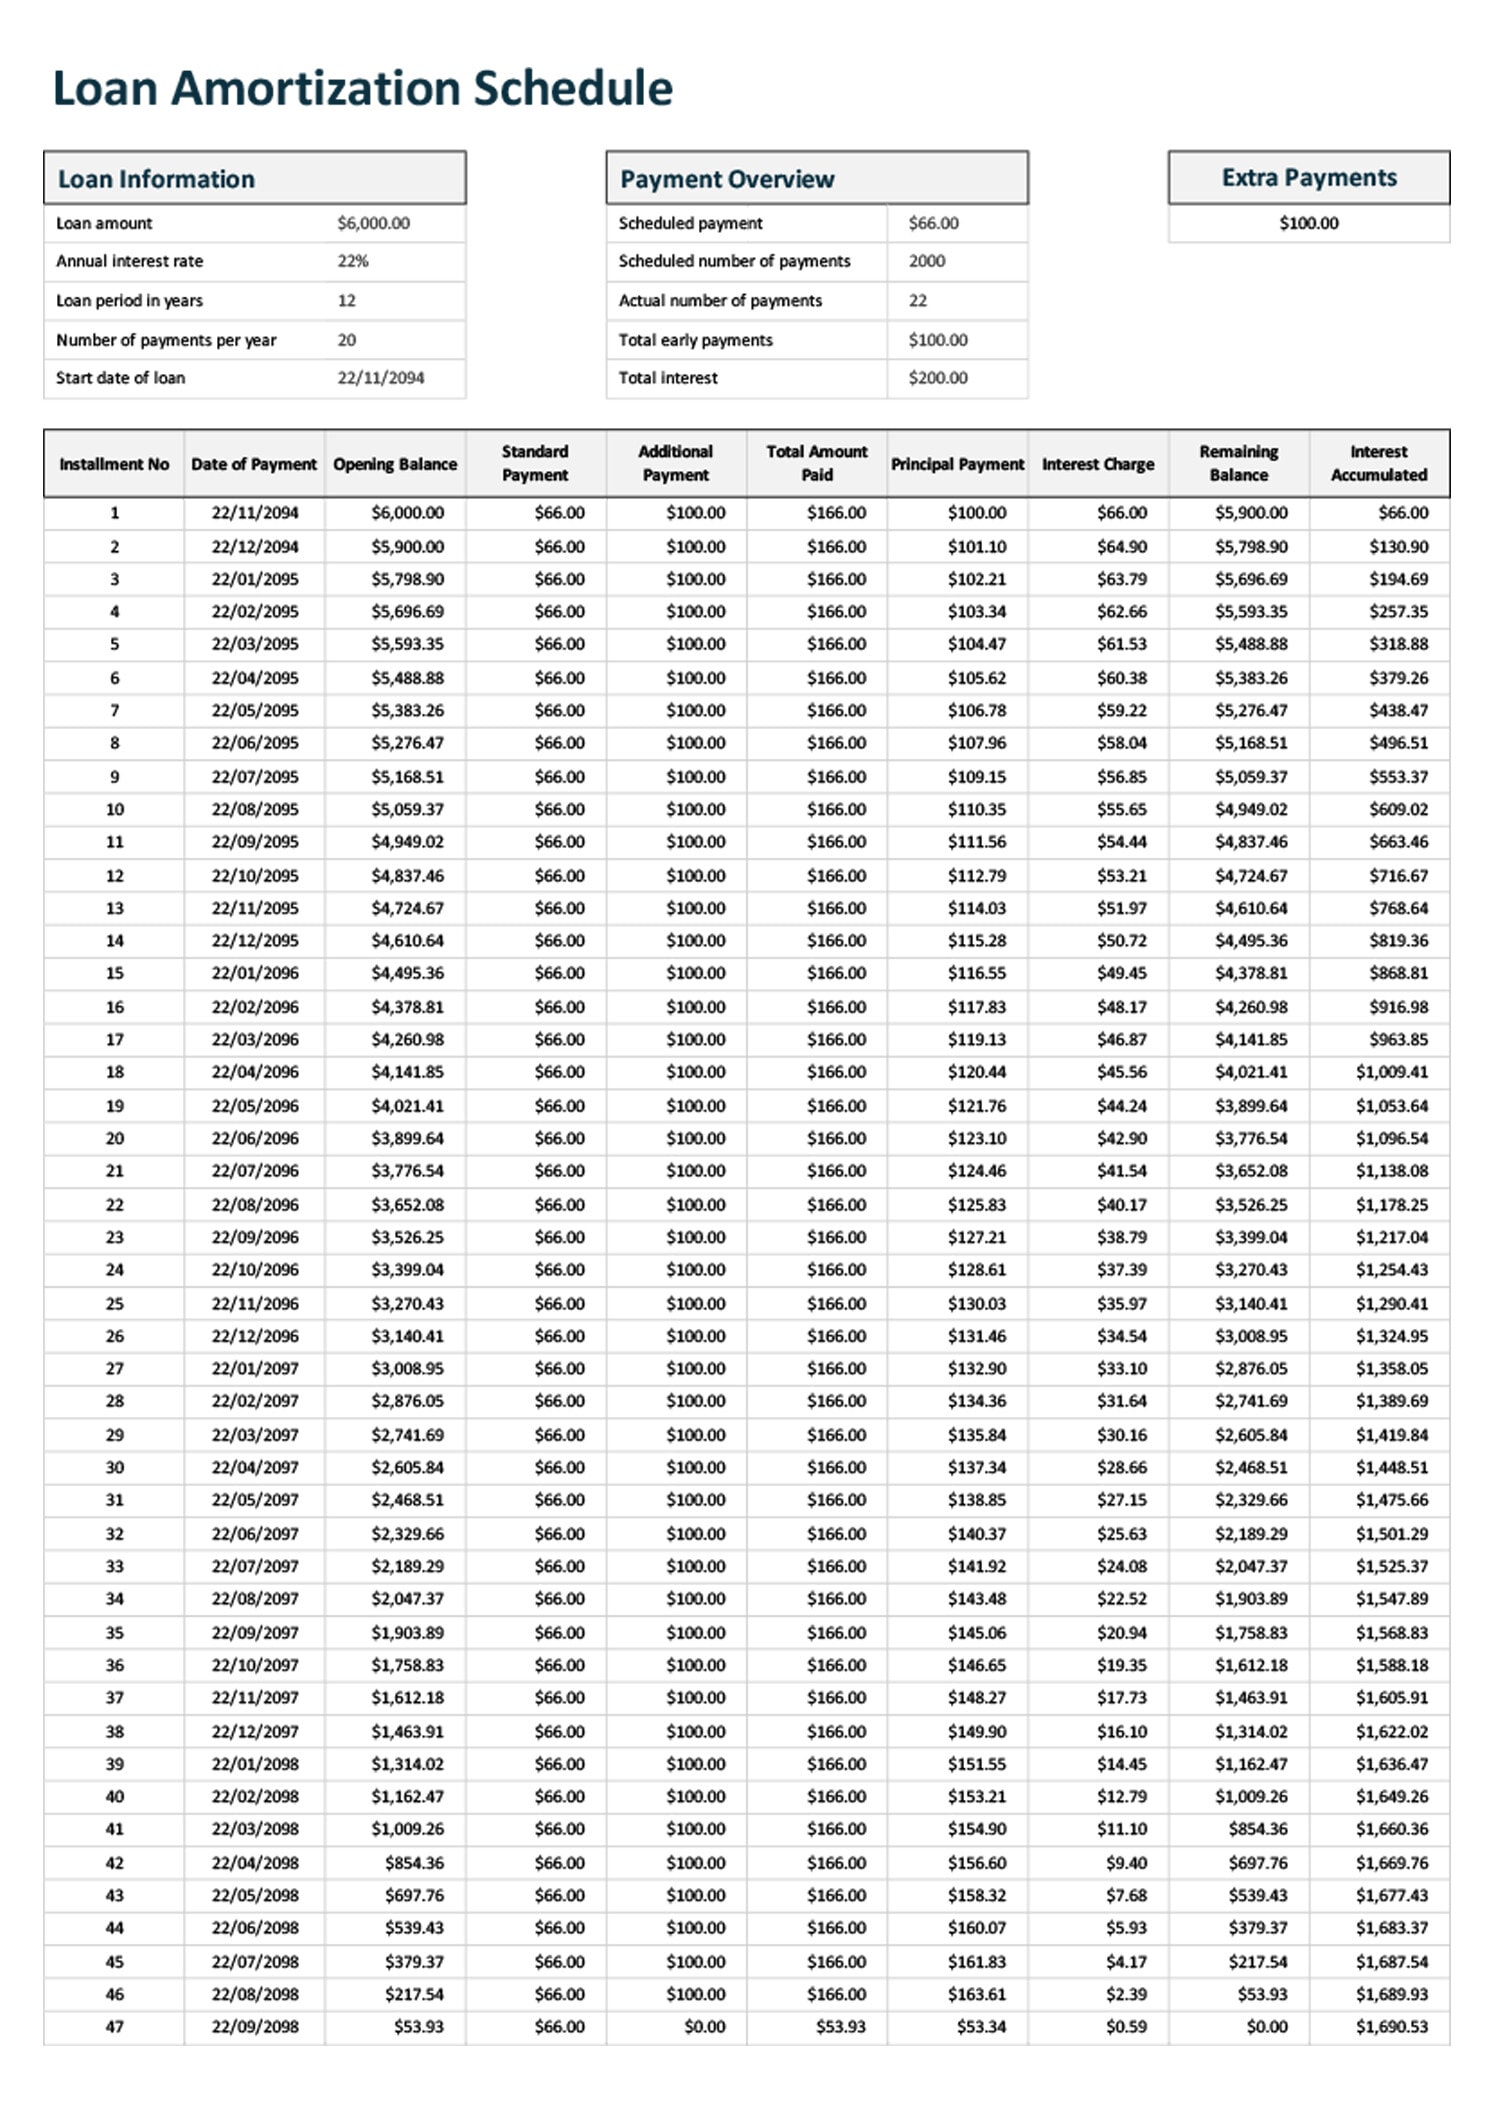
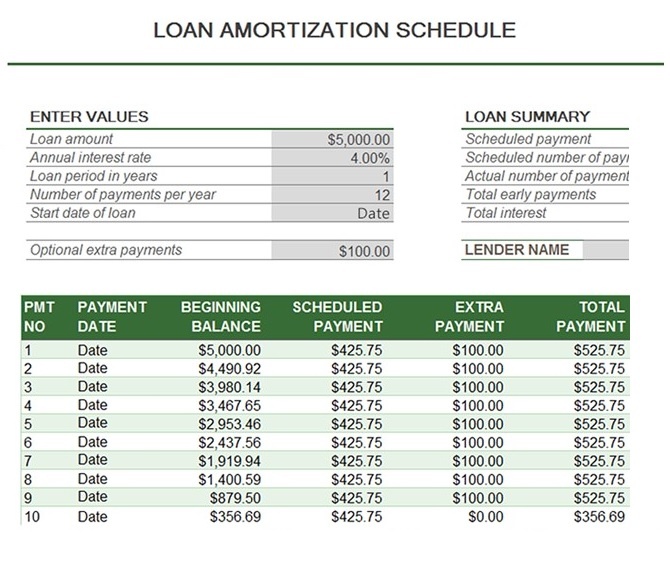
I spent three years cleaning up loan data for mid-market lenders before I got tired of watching junior analysts manually re-enter numbers from PDFs into Excel because nobody had bothered to build a proper schedule in the first place. The core problem isn't that people don't know how to calculate interest. It's that almost every template out there assumes a textbook scenario and falls apart the moment a real loan has a partial period at inception, an irregular payment date, or a rate change mid-term. I still keep my own sheet for this work because it handles the edge cases that the standard templates ignore. A proper amortisation schedule needs to track more than just principal and interest per row. You need the draw date, the first payment date, the compounding basis, the day-count convention, the payment frequency, the balloon amount if there is one, and the residual balance after each period. Without those fields, the template is just a calculator in disguise and it will give you the wrong answer on anything that isn't a standard 30-year fixed mortgage. Here is the layout I use as a starting point. The columns are: Period, Payment Date, Beginning Balance, Payment, Principal Portion, Interest Portion, Ending Balance, Cumulative Principal Paid, and Cumulative Interest Paid. If you are dealing with multi-currency loans or foreign exchange adjustments, you add a column for the FX rate applied on the valuation date. Most people skip the FX column and then wonder why their reconciliation is off by a few basis points at quarter end.
The method behind the numbers
The interest for each period is calculated on the beginning balance using the periodic rate. That periodic rate comes from dividing the annual nominal rate by the number of compounding periods per year, not by the number of payments. When a lender says 6% compounded monthly, the periodic rate is 0.5%, and that matters because some contracts use 360-day year conventions while others use actual/365. I have seen deals where the difference between those two conventions added thousands of dollars over the life of a five-year loan. The principal portion is simply the total payment minus the interest portion. The ending balance is the beginning balance minus the principal portion. This seems trivial until you hit a partial period. If the loan closes on the 18th of the month and the first payment is due 45 days later, you cannot just use the standard monthly formula. You need to accrue interest for the extra days separately and then fold that accrued amount into the first full period or handle it as a separate line item, depending on how the contract is drafted. Most templates do neither.
A real problem I ran into and how I fixed it
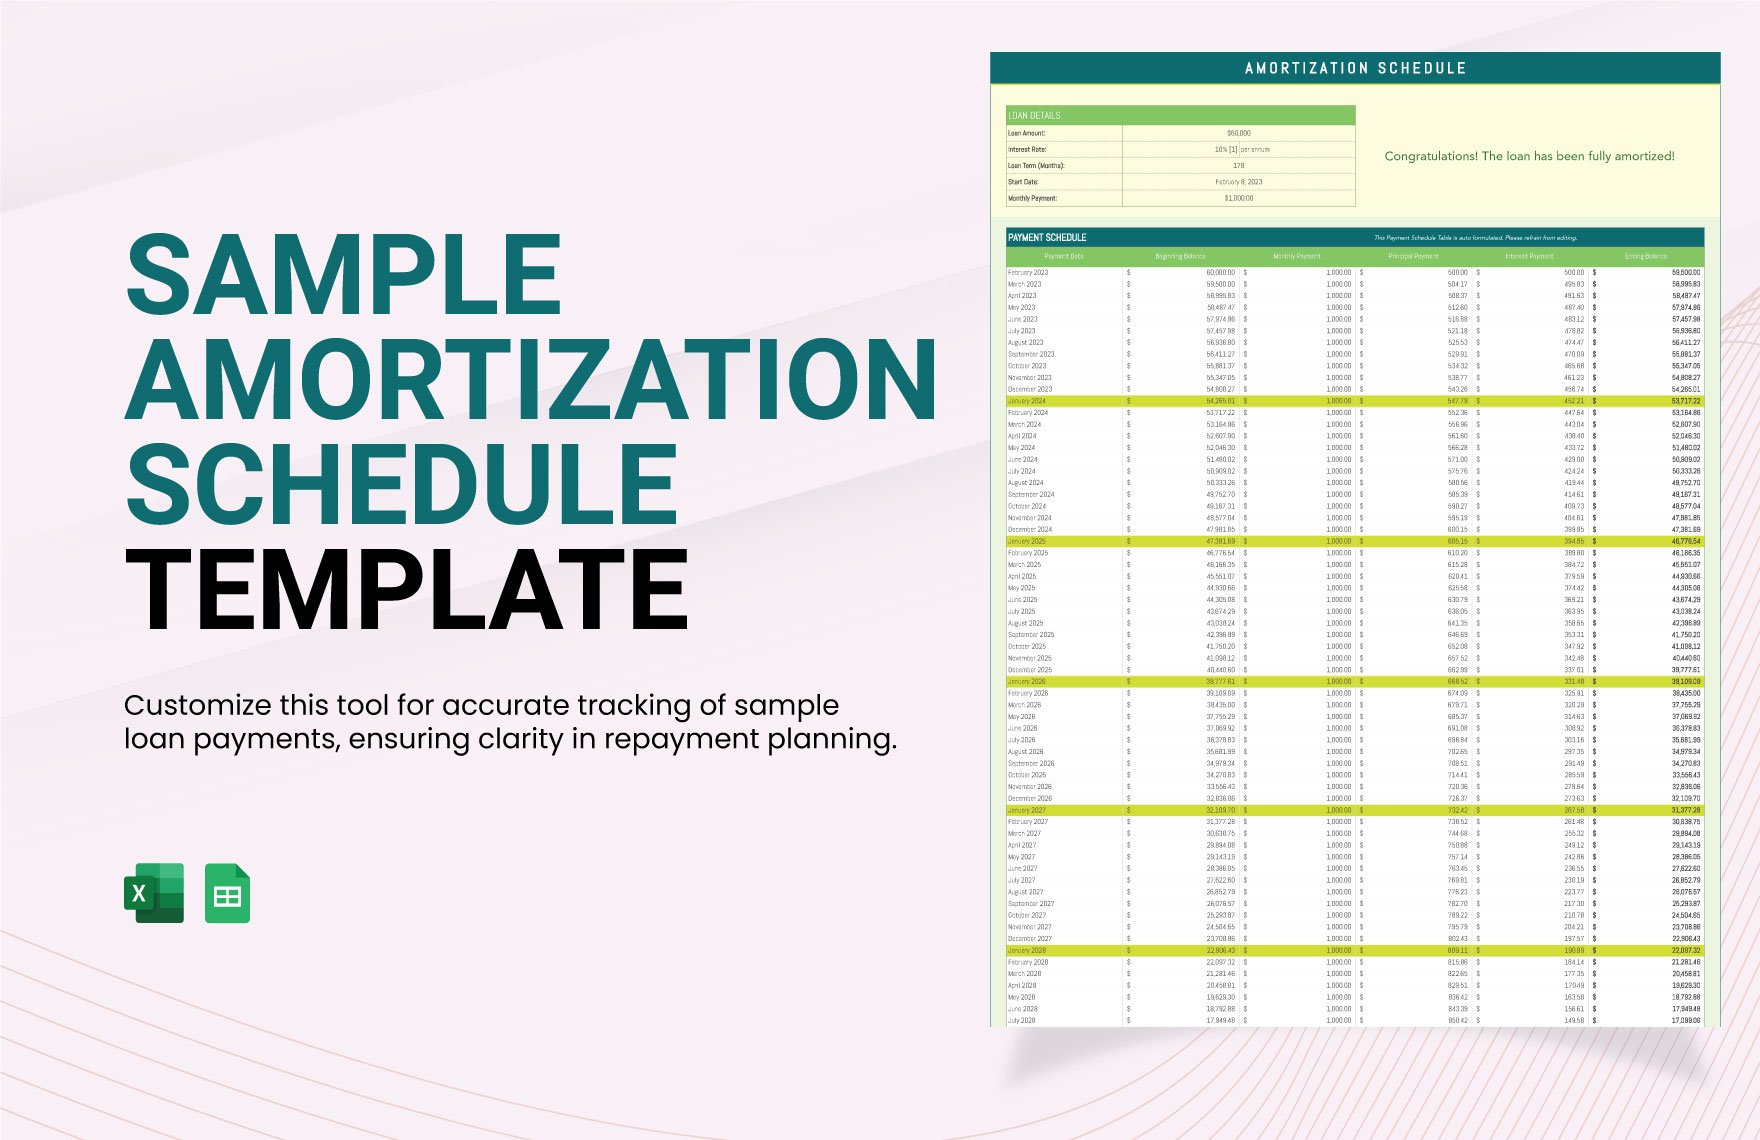
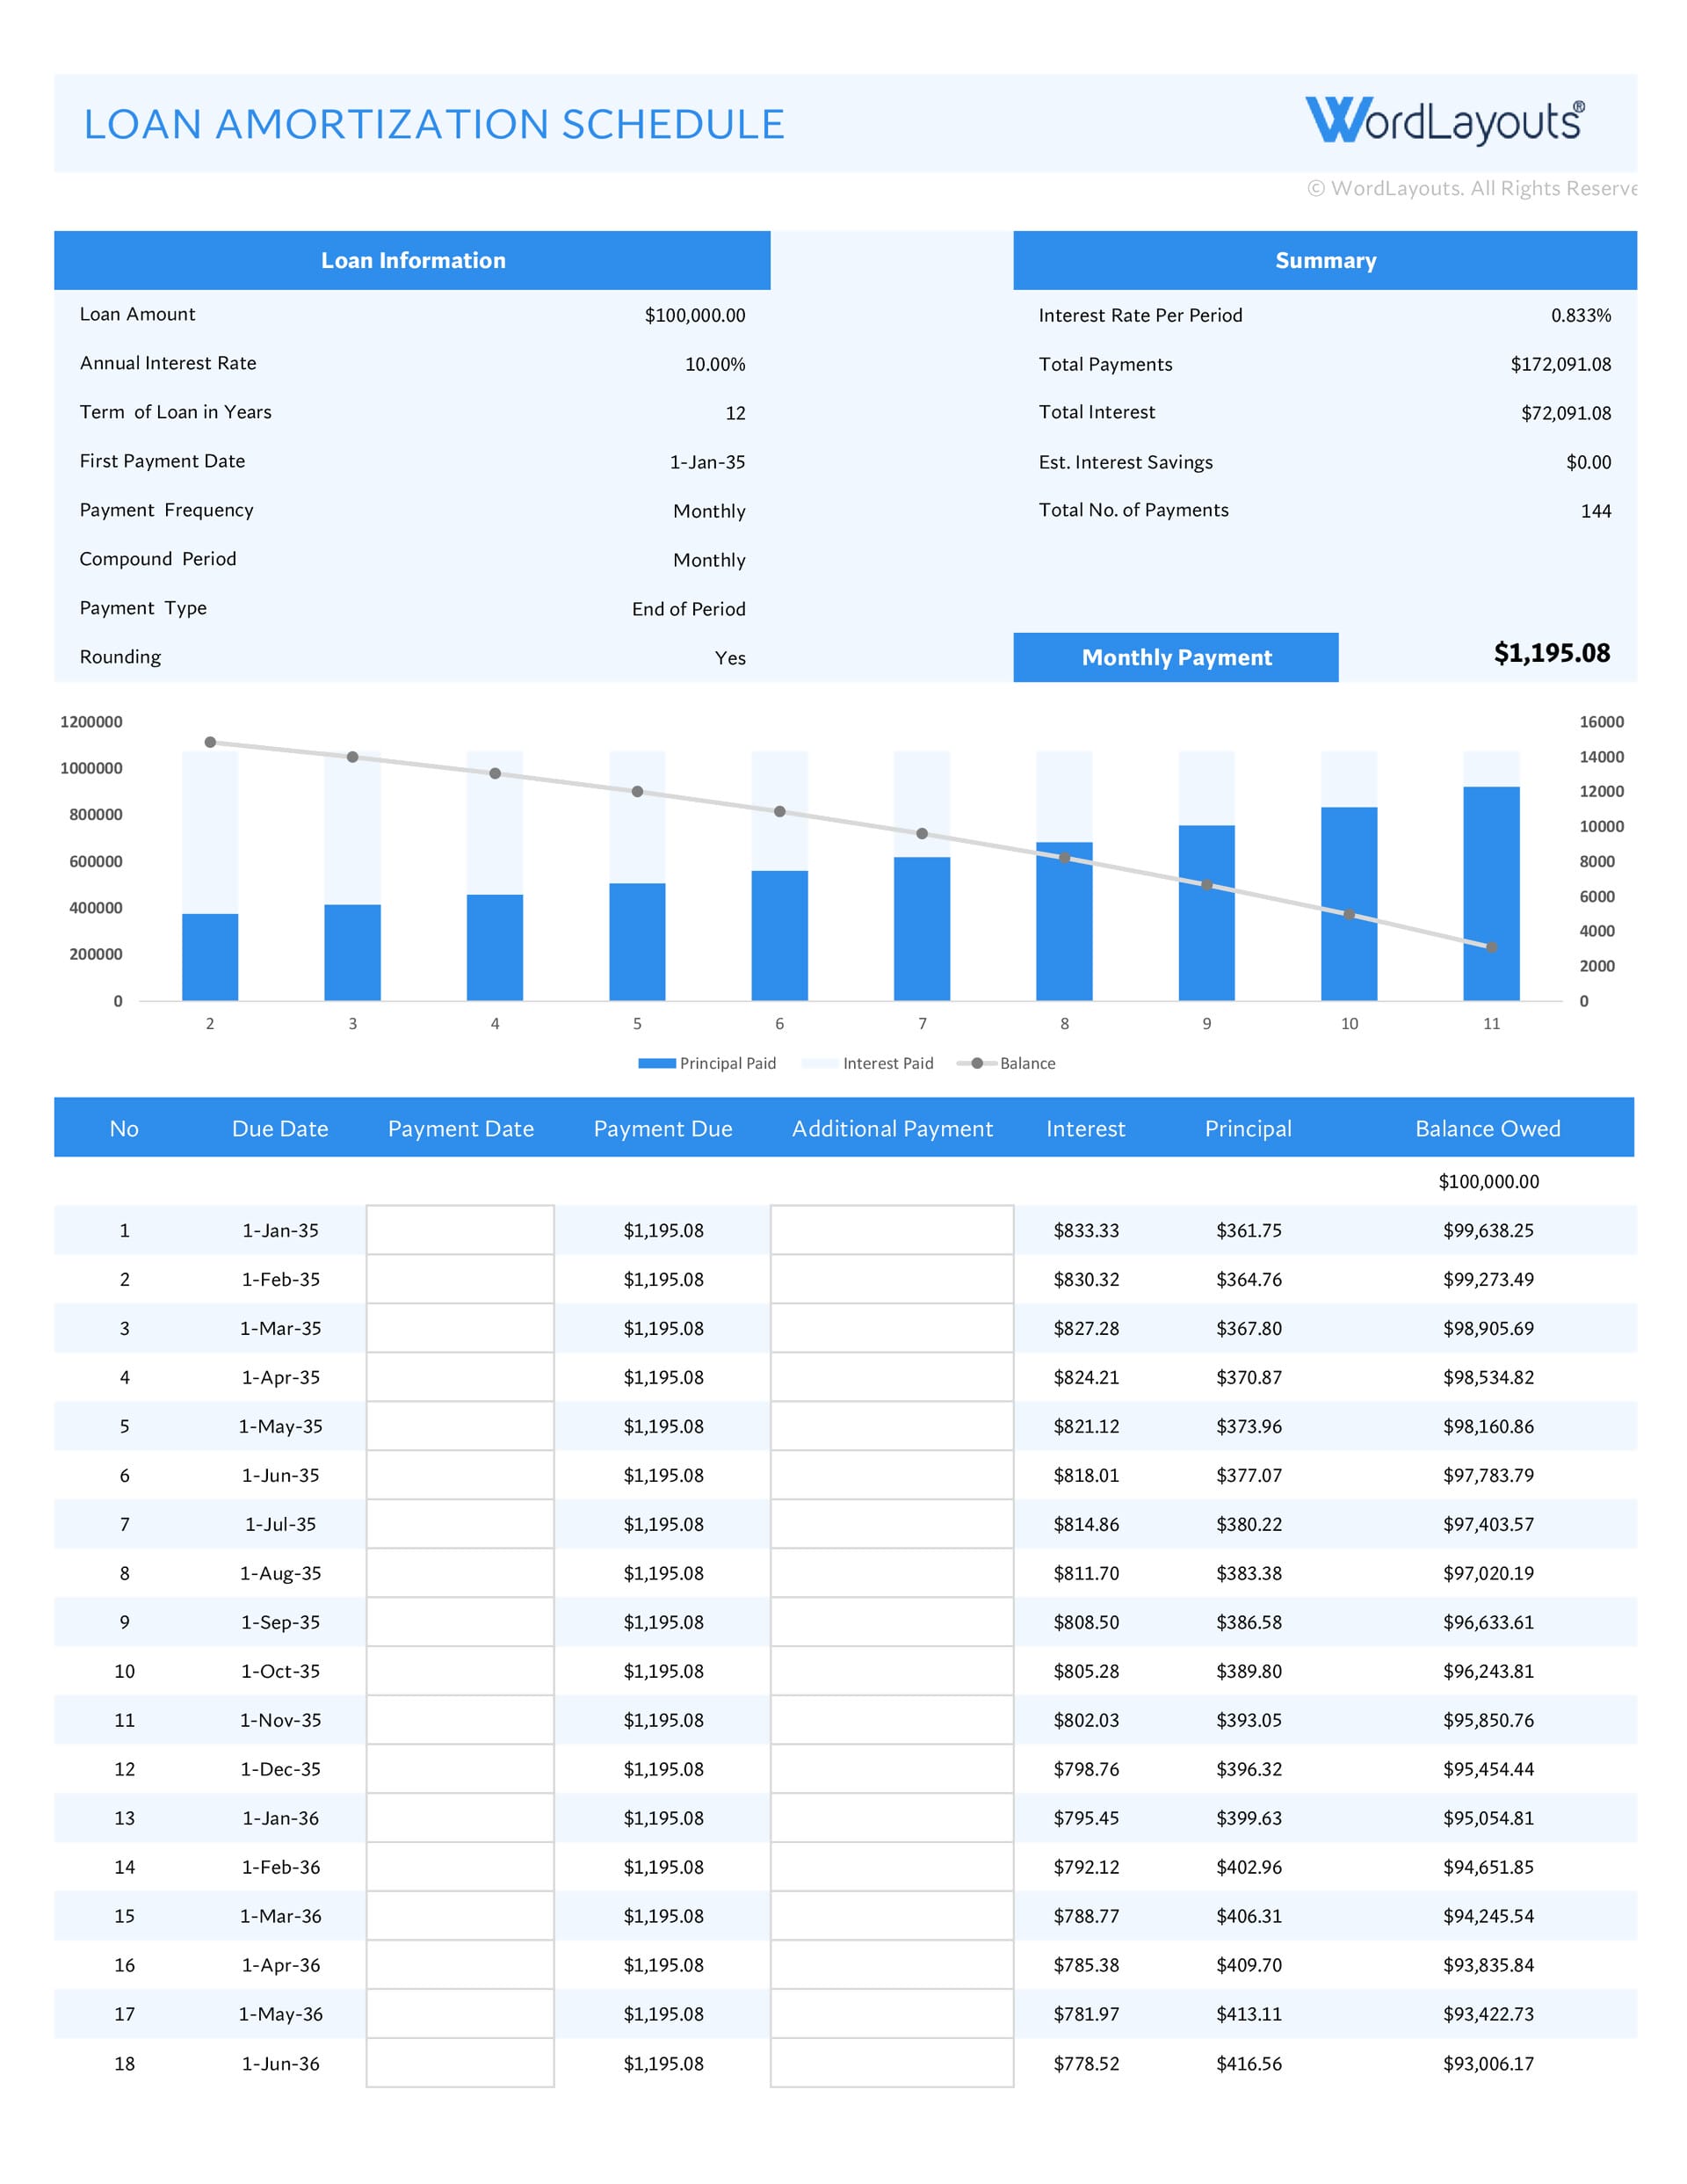
Last year I was working with a client who had a line of credit that was drawn down intermittently over 14 months. The existing template assumed one original principal and one steady amortisation path. Every time a new draw occurred, the schedule broke. The beginning balances didn't align with the remaining term, the interest calculations doubled up on the same days, and the cumulative totals were garbage by month six. I rebuilt the sheet so that each draw had its own sub-schedule with a start date, an end date, and its own amortisation trail, and then I rolled those sub-schedules into a master view using a pivot table keyed off the payment date. It took about two hours to set up correctly. After that, updating the schedule for new draws took roughly ten minutes instead of rewriting the whole thing. If you want something you can download to start from, I put together a working template with that multi-draw structure built in. It includes the sub-schedule logic, the day-count selector, and a validation row that flags when the ending balance does not reconcile to zero at maturity. You can find it at example-downloads.example/amortisation-schedule-template-v2.xlsx. The file itself is an Excel workbook. If your organisation blocks macros or prefers Google Sheets, the equivalent sheet is available on the same page.
Get the Full Details
Common pitfalls that will quietly ruin your schedule
The first pitfall is rounding. If you round the interest to two decimal places on every row and then use that rounded interest to back into the principal, your final payment will be wrong by several dollars. The fix is to keep the interest calculation at full precision in the background cells and only round the display column. You can do this by using a separate cell for the unrounded value and a formatted cell for presentation, or by using a helper column that retains full decimal accuracy and summing from that column instead of from the displayed values. The second pitfall is payment timing. Many templates assume the first payment is exactly one period after funding. In practice, the first payment can be anywhere from 25 to 45 days out. If you hard-code the payment count as a simple 60 for a five-year monthly loan and then shift the first date, the schedule will never reach a zero balance at maturity. The correct approach is to set the maturity date as the anchor and derive the payment count from the actual calendar, not the other way around. A practical way to do this is to use an array of payment dates generated from the start date and frequency, then calculate the interest for each interval based on the actual days between dates. A third issue is prepayment. Most basic templates do not account for it. If the borrower makes an extra principal payment, the remaining term either stays the same and the payment drops, or the payment stays the same and the term shortens. You need to decide which behavior the contract specifies and build a toggle into the sheet. I usually include a parameter called PrepaymentTreatment with two options: RecalculatePayment or RecalculateTerm. The default is RecalculateTerm because that is what most commercial loans use, but consumer products often prefer RecalculatePayment. Picking the wrong one silently inflates or deflates the interest cost.
When a template is not the right tool
An amortisation schedule template works well for single-loan calculations, quick estimates, and small portfolios where you are dealing with a few dozen instruments and monthly updates. It starts to break down when you need to track hundreds of loans with different currencies, varying day-count conventions, embedded options, or when you need auditable version history. In those cases, a spreadsheet becomes a liability rather than an asset. I have watched teams lose half a day every month reconciling divergent versions of the same template because someone updated a cell in the wrong copy. For that scale, a lightweight database with a scheduled job that regenerates the amortisation table from source data is faster and safer, even if the initial build takes a few days. The tradeoff is real: you spend time upfront and save time continuously. If your workflow is one-off or low-volume, the template is fine. If it is ongoing and high-volume, you are better off investing in a proper system. Run a few checks. Confirm that the sum of all principal portions equals the original loan amount. Confirm that the sum of all interest portions equals the total interest cost at maturity. Confirm that the final ending balance is exactly zero or within one cent of zero. Confirm that the payment dates follow the agreed frequency without gaps or overlaps. If any of those fail, the schedule is wrong, and it does not matter how clean the formatting looks. I usually add a summary block at the top that pulls those four totals and highlights them in red if they do not match, because when you are looking at 60 rows of numbers, it is easy to miss a discrepancy until someone asks for a reconciliation and you have to trace it back through three months of updates. The template I linked above includes that summary block by default, along with the multi-draw logic and the day-count selector. It is not a perfect solution for every situation, but it covers the cases that break most free templates. If you run into a scenario it does not handle, like a loan with step-up rates or a grace period that differs from the standard accrual window, you can extend the sheet by adding a rate-change table and linking it to the periodic rate field. I tend to avoid building every possible edge case into the base file and instead keep the extension logic separate, because the more you cram into one sheet, the more likely someone is to break a hidden dependency.