Building an Amortization Schedule with Extra Payments in Excel
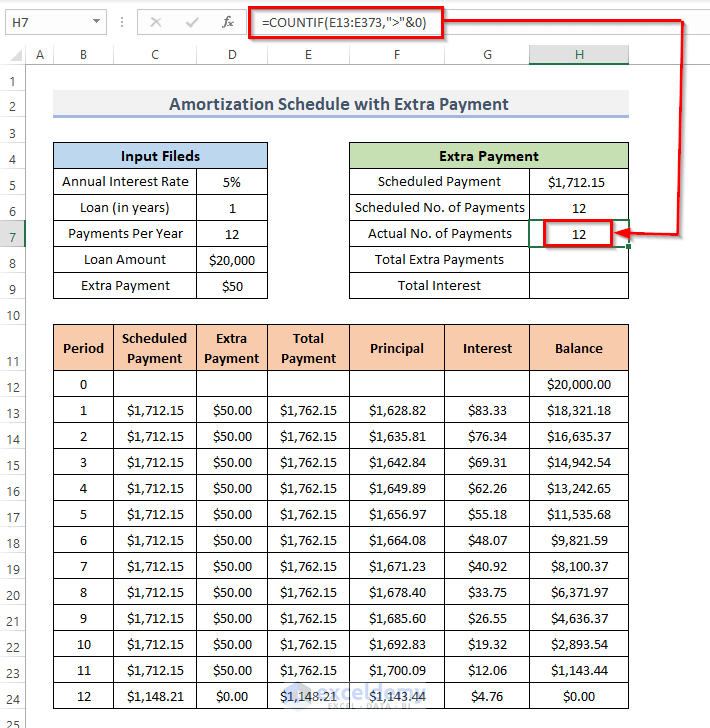
Most people try to modify a standard amortization table by just tacking extra payments onto the regular schedule, and it creates a mess within a few months. The compounding effect of extra principal changes every subsequent row, and if your formulas don't recalculate automatically, you end up with numbers that drift from reality. Here is how to actually set it up. The core structure needs five columns at minimum: Payment Number, Beginning Balance, Scheduled Payment, Extra Payment, and Ending Balance. Your Beginning Balance for each row references the previous row's Ending Balance. The tricky part is the interest calculation, because interest accrues on the beginning balance for that period, not on some hypothetical original amount. So your interest column is simply the monthly rate multiplied by the beginning balance, and your principal portion is the total payment minus interest. When you add an extra payment, you subtract the entire extra amount from principal in that same row. I built one of these for a client last year who wanted to model what would happen if they threw an annual bonus at their mortgage every December. The straightforward approach worked fine until we hit the refinance scenario. They had assumed a different interest rate starting mid-year, but the amortization table kept using the original rate for every single row because the rate was hardcoded as a constant rather than pulled from a referenced cell. I spent about forty-five minutes going through each formula and converting those hardcoded values into cell references tied to a single rate input section at the top. Once that was done, switching the rate mid-term meant editing one cell instead of hunting down twenty or thirty individual formula references. It is an annoying friction point that nobody mentions when they are writing tutorials about this.
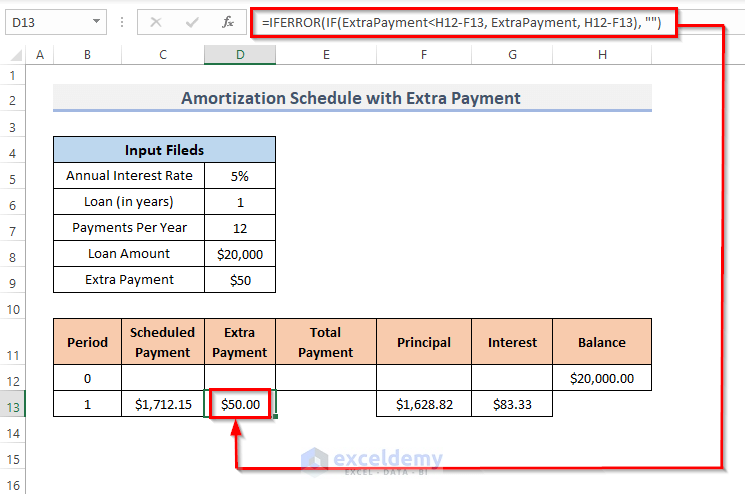
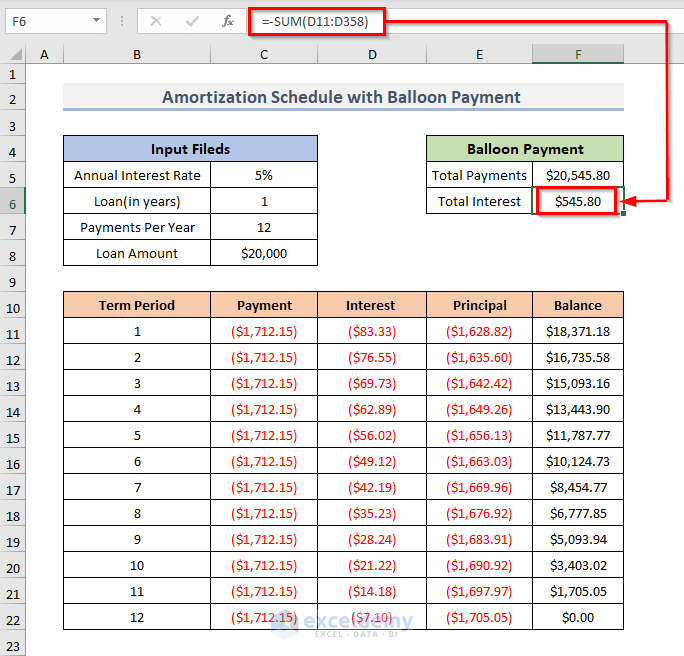
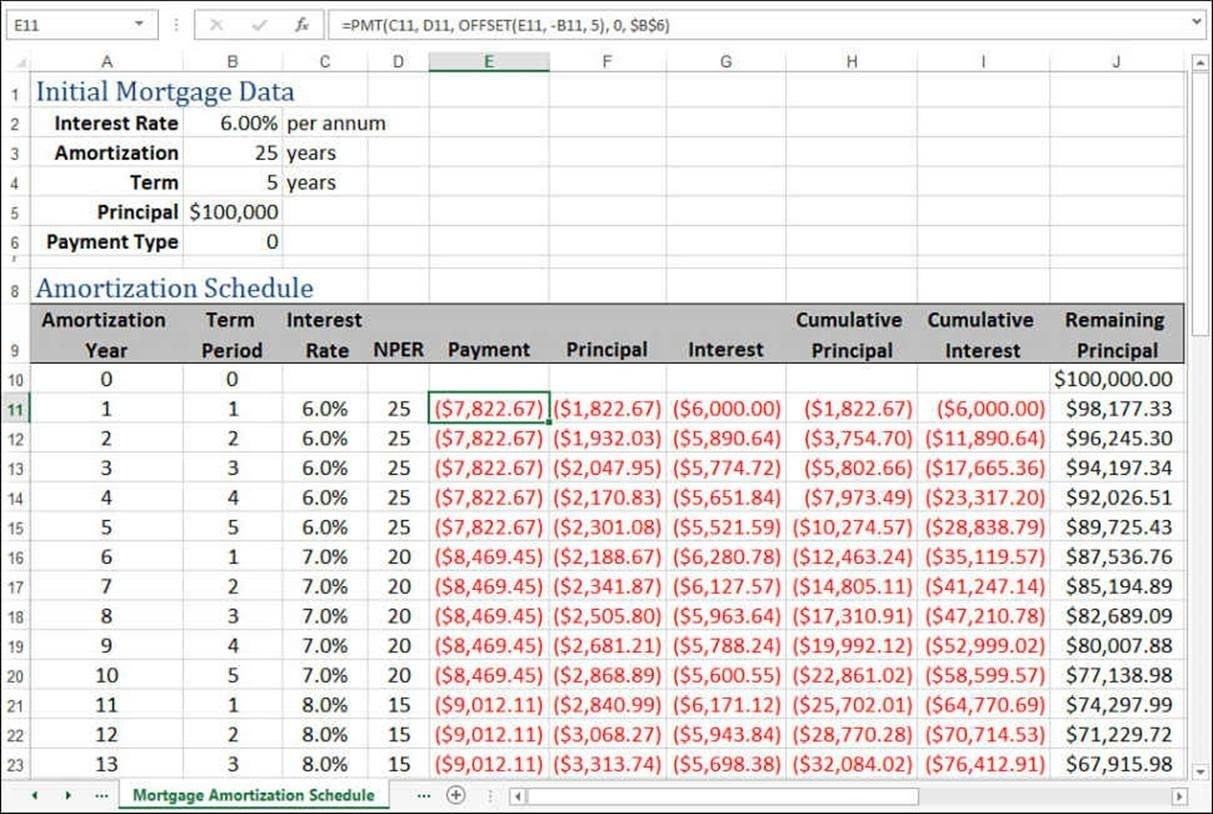
Here is the actual formula logic you need. For the scheduled payment amount, use the PMT function: =PMT(rate/12, total_periods, -loan_amount). That gives you a fixed monthly payment. For the extra payment column, you can either hardcode a static amount or reference a separate input cell so you can test different scenarios without rewriting formulas. The ending balance for any given row is: beginning balance plus interest minus total payment minus extra payment. If the extra payment plus the regular payment exceeds the remaining balance, the formula can produce a negative number, which technically means the loan is paid off early. You handle that with an IF statement that caps the final payment at whatever remains. One thing that catches people off guard is that extra payments do not reduce your required monthly payment amount unless your lender explicitly applies them that way. Most lenders apply extra principal directly to the outstanding balance while keeping the same payment schedule. This means your payoff date shifts earlier but your monthly obligation stays identical. The Excel model should reflect this reality, because some people build calculators that re-amortize the loan after each extra payment, which produces a lower monthly figure that does not match how actual mortgages work in practice. If you want to see the cumulative interest paid versus the original schedule, add a parallel column that calculates what the interest would have been without any extra payments, then subtract. The difference is your total interest savings, and dividing that by the original total interest gives you a percentage saved. For a typical 30-year loan at 6.5 percent with an additional two hundred dollars per month, you are looking at somewhere between eight and twelve years shaved off the term depending on the principal balance, and roughly thirty to forty percent less in total interest over the life of the loan. Those are rough numbers from memory on loans I have modeled, not exact predictions for your specific situation.
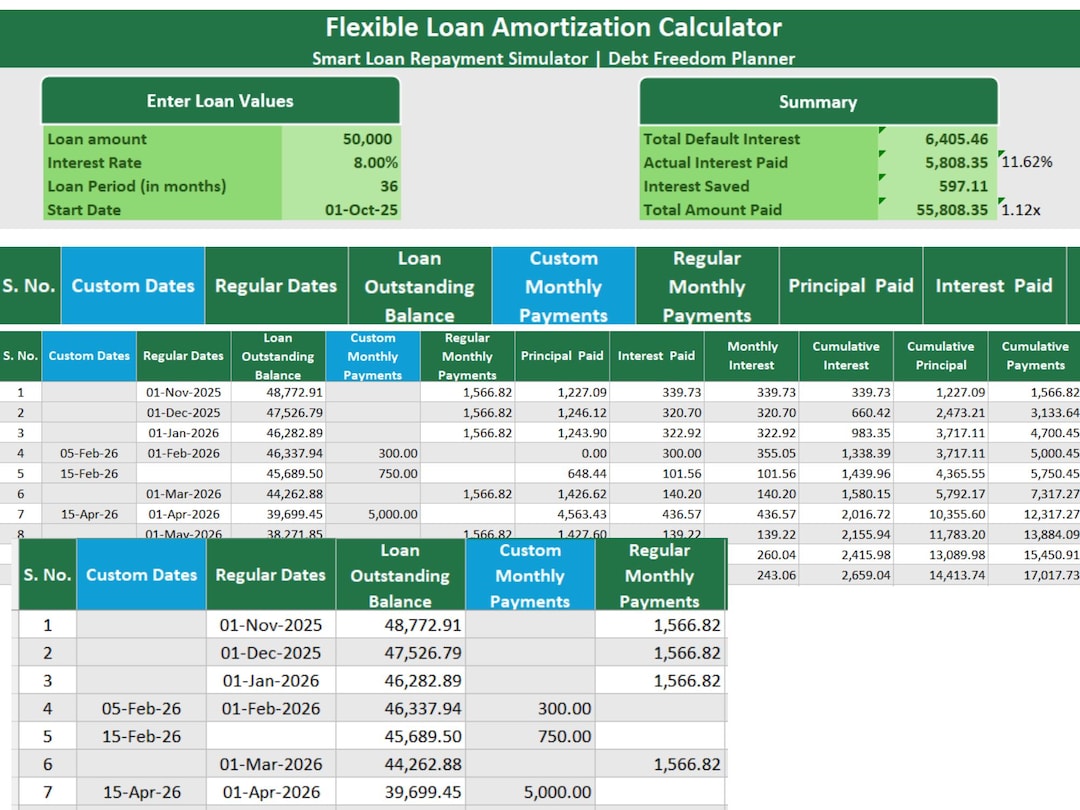
There are genuine limitations to an Excel-based amortization calculator. It assumes fixed payments and a constant interest rate unless you manually adjust each period, which defeats the purpose of automation. Adjustable-rate mortgages introduce variability that makes the spreadsheet significantly more complex, and most people do not want to rebuild their model every time their adjustment period hits. Second, Excel is not designed for legal or financial advice, and the numbers it produces should not be used as a substitute for a lender's official payoff statement. Lender amortization tables sometimes include fees, escrow adjustments, or prepayment penalties that a generic spreadsheet will not capture. If you are making this kind of decision with real money on the line, getting a formal projection from your servicer costs nothing and takes five minutes. For people who just want a working file rather than building from scratch, there are decent free templates available through the Excel template gallery and a few personal finance websites. Search for "amortization schedule with extra payments" and pick one that has clearly labeled input cells at the top rather than formulas buried throughout the sheet. The ones that look prettiest often have fragile structures that break when you change the loan amount or term. Simpler is better here. The PMT function itself has a few gotchas worth noting. The rate and nper arguments must be on the same time basis, so if your rate is annual you divide by twelve and multiply your years by twelve. Some people forget this and the resulting payment is completely wrong. Also, the present value argument should be entered as a negative if you want the payment to return as a positive number, or vice versa. Mixing signs arbitrarily will give you a payment that looks correct but is actually the opposite sign, which then propagates errors through the entire schedule.
Get the Full Details
Another advanced nuance that most online guides skip is how to handle partial payments. If you make an extra payment mid-period instead of at the beginning of the month, the interest accrues on the full balance for that period. Some calculators assume extra payments are applied at the start, which understates your interest cost slightly. The difference is small on a monthly basis but becomes noticeable over years. You can model this by adding a column for the exact payment date and using a day-count fraction to allocate interest properly, though that requires switching to a more complex day-count convention formula rather than the simple monthly approach most templates use. If your goal is simply to see whether extra payments make sense for your situation, there are also dedicated amortization calculators on lender websites and financial planning platforms that handle these edge cases better than a do-it-yourself spreadsheet. Excel is powerful when you need to run scenarios side by side or build custom assumptions, but it is not the only tool for the job. Use whichever approach gets you the answer without making you second-guess the math.