Why Your Monthly Payment Is a Lie
A balloon loan has a smaller monthly payment than a fully amortizing loan of the same term and rate, because the final payment—a lump sum called the balloon—is never included in the monthly calculation. Most people building amortization tools get this wrong on the first pass. They calculate payments as if the loan fully pays off over the stated term, then just tuck the balloon in as an afterthought. It works in Excel, but it breaks when you try to show a real amortization schedule to a borrower who needs to see exactly how the balance changes each month. The fundamental structure is this. You have a principal amount, an annual interest rate, a loan term in years, and a balloon payment amount or date. The monthly payment is calculated on the full principal as though the loan were amortizing completely over the full term. Then at the balloon date, whatever principal remains is due in a single payment. The trick is figuring out what that remaining principal actually is, because it is not zero and it is not arbitrary. Here is the math without the textbook padding. The monthly payment uses the standard annuity formula: P = (r × PV) / (1 - (1 + r)^-n), where r is the monthly interest rate, PV is the present value or loan amount, and n is the total number of monthly payments. The balloon balance at the end is simply the future value of the original loan amount minus the future value of all payments made. In Excel that is FV(rate, nper, -pmt), and the result is your balloon.
I built a balloon amortization calculator for a commercial lending group about four years ago. The spec was simple enough on paper: enter loan amount, rate, term, and balloon date, get back a schedule and payment breakdown. The problem I ran into was not the core math. It was the edge case of a balloon that fell on a date with a different day count than the standard 30-day month, like February in a non-leap year when the other months in the schedule were all 30 days. The payment amount stayed the same but the accrued interest for that period was wrong by a few dollars, which cascaded into every subsequent balance line. I fixed it by computing accrued interest per period using the actual days in that period divided by 360, instead of blindly using a flat 30/360 convention. That small change aligned the schedule with what the underwriters were actually seeing on the production side.
How to Build It Without Losing Your Mind
Start with the inputs. Loan amount, annual interest rate, loan term in years, and balloon specification. The balloon can be defined in two ways: as a specific dollar amount, or as a date when the remaining balance becomes due. These produce different schedules and require different handling in the calculation engine. When the balloon is a date, you are essentially running a shorter amortization. Calculate the monthly payment using the full loan term and full principal, then at the balloon date compute the remaining balance. That remaining balance is your balloon payment. Everything before that date is a standard amortization schedule. Everything after is a single bullet payment that closes the loan. When the balloon is a dollar amount, the calculation flips. You know the final payment, so you need to find the monthly payment that satisfies the equation: present value of all payments plus present value of the balloon equals the original loan amount. This requires an iterative solver. You can use Goal Seek or a simple bisection method. The bisection approach converges in maybe twelve iterations, which is fast enough that nobody notices.
Get the Full Details
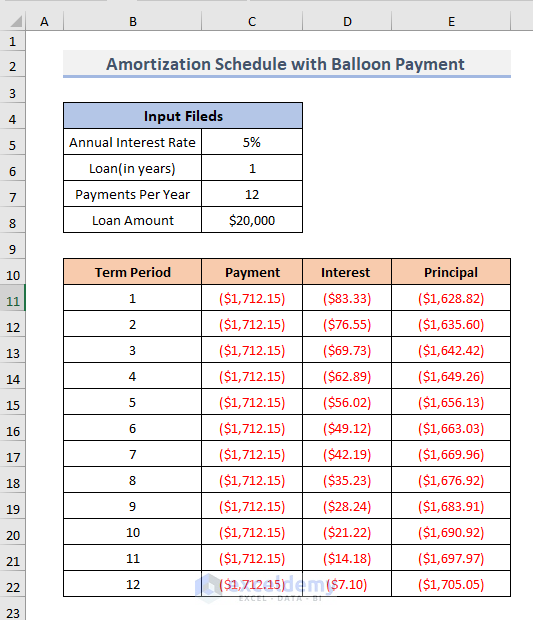
Here is a concrete example that I use when training junior developers on this. A $500,000 loan at 7% annual rate, 7-year term with a balloon at the end of year 7. The monthly payment comes out to $4,476.46. The remaining balance after 84 payments is approximately $377,298. That is the balloon. The borrower pays $4,476.46 every month for seven years, then writes a check for $377,298. Total interest paid over the life of the loan is roughly $103,022 in regular payments plus the implicit interest embedded in that final balance, which depending on how you measure it makes the effective cost significantly higher than 7%.
What Nobody Tells You About Balloon Payments
People assume the balloon is just a delayed payment. It is not. It is a refinance trigger. The monthly payment is calculated to be manageable, which makes the loan look affordable, but the balloon ensures that the lender recovers most of the principal at a predetermined date. If the borrower cannot refinance or sell the asset, the loan defaults. This is not theoretical. I have seen commercial real estate deals where the borrower assumed they could refinance at renewal, but rates had jumped 200 basis points and the property value had dropped. The balloon became a forced sale. From a tool-building perspective, the important implication is that your calculator should surface the balloon clearly, not bury it in row 85 of a spreadsheet. Label it. Highlight it. Make it impossible to miss. Borrowers skim. Lenders skim. The balloon is the thing that kills deals, so it deserves visual emphasis. Another nuance that trips people up is the difference between a true balloon and a demand loan. A true balloon has a fixed payment schedule and a fixed maturity. A demand loan can be called at any time. Some products labeled as balloon loans are actually demand loans in disguise. If you are building a calculator for a specific product type, verify which one it is before you code the schedule. The output is fundamentally different.
There is also the issue of prepayment. If a borrower prepays part of the loan before the balloon date, the remaining balance shrinks, and the balloon shrinks with it. Your calculator needs to handle optional extra payments without breaking the schedule. The cleanest way is to recalculate the balloon at each prepayment event using the updated remaining balance and the original payment amount. Do not try to re-amortize the whole schedule from scratch unless the prepayment is structured as a formal modification.

Practical Implementation Notes
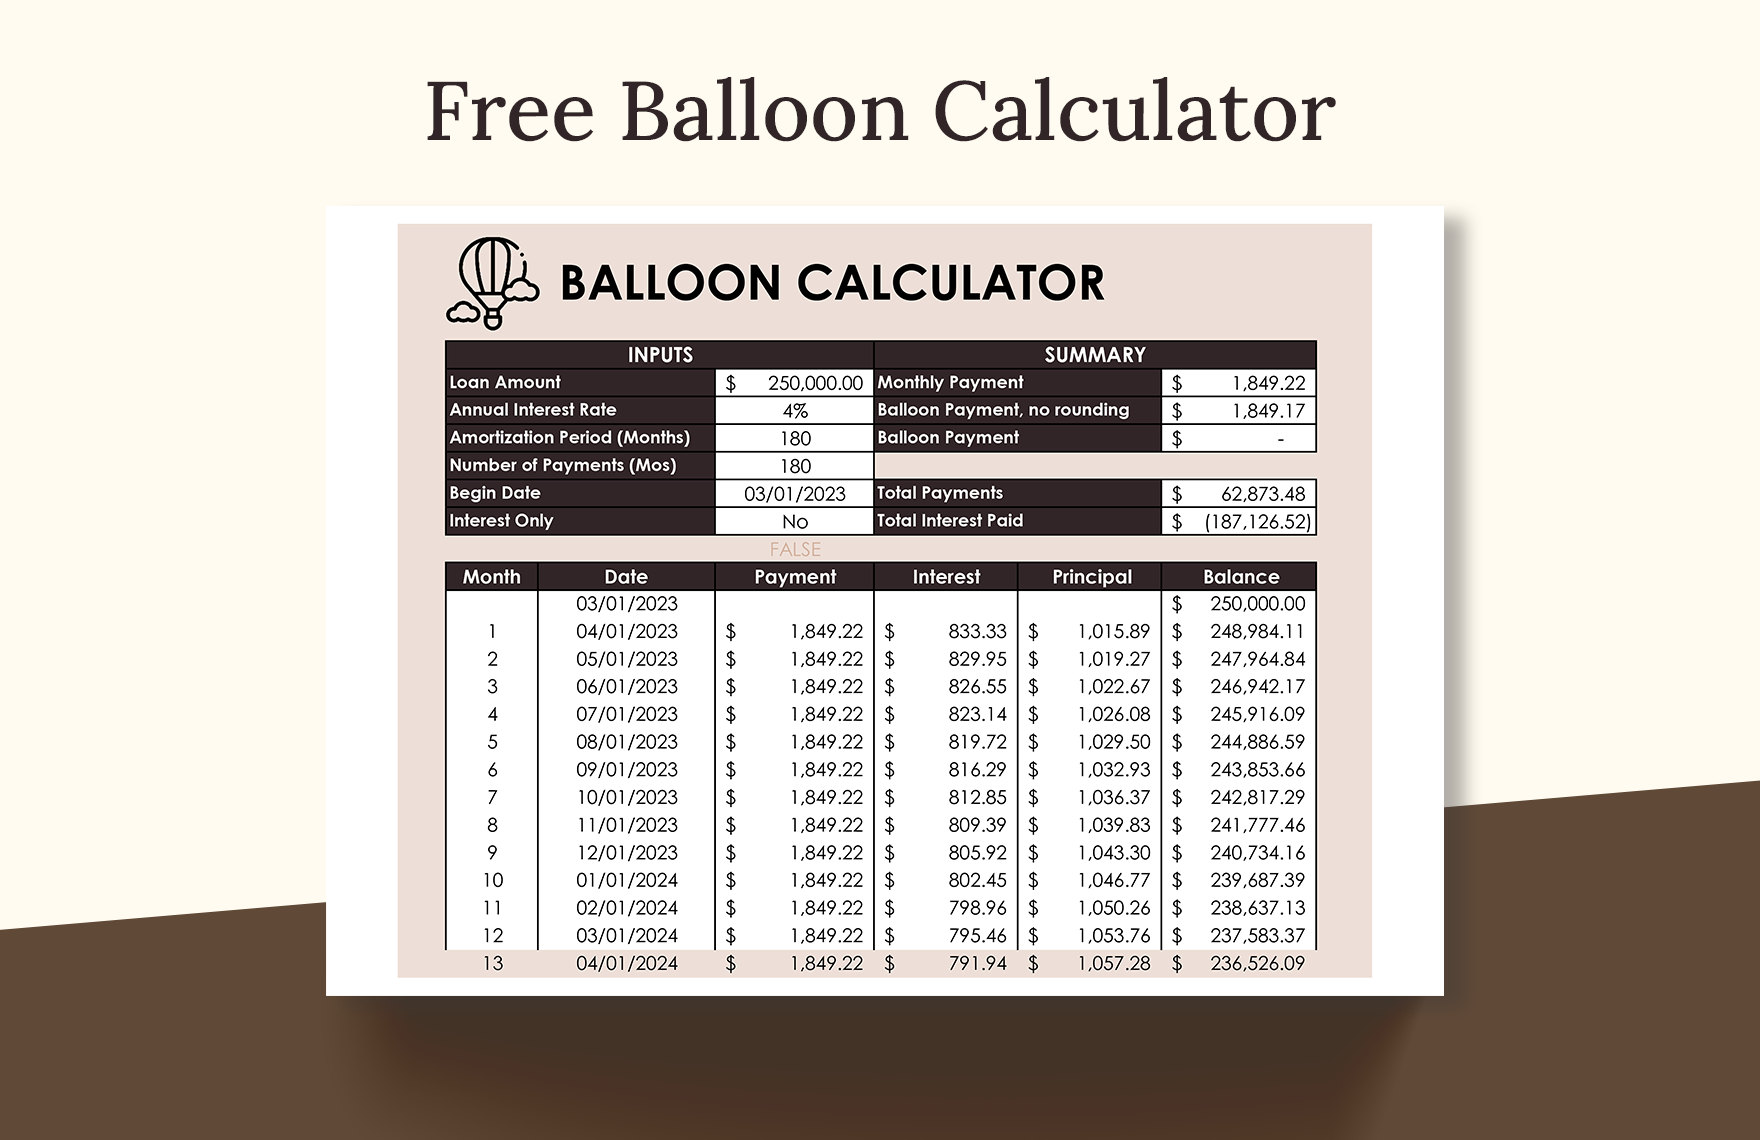
Use the actual/360 day count convention for commercial loans. It is the industry standard in the United States. Residential loans often use actual/365. Mixing them up will give you incorrect accruals and a schedule that does not match what the servicing system produces. I learned this the hard way when a client's production system and my calculator disagreed by $47 on a $2.1 million loan. The discrepancy traced back to one loan using 30/360 and the other using actual/360. Thirty minutes of debugging and a single constant change later, we were aligned. For the user interface, keep it simple. Input fields for loan amount, interest rate, term, balloon date or amount, and optionally start date. Output fields for monthly payment, balloon payment, total interest, and total cost. Show the amortization schedule as a table with columns for payment number, date, payment amount, principal portion, interest portion, and remaining balance. The last row before the balloon should show the remaining balance equal to the balloon amount. That visual confirmation catches errors faster than any unit test. If you are building this as a web tool, consider using a lightweight JavaScript library for the math rather than reinventing it. The core functions are trivial, but floating point arithmetic in JavaScript can produce artifacts like a balance of $0.0000001 instead of zero at the end of a fully amortizing schedule. Round to two decimal places at each step, or use a decimal library. The difference between a clean output and a broken one is often a single rounding decision.
When This Approach Fails
A balloon amortization calculator is not useful if the loan has variable rate adjustments. Once the rate changes mid-term, the payment schedule needs to be recalculated and the balloon balance may shift. The basic model assumes a fixed rate throughout. If you need variable rate support, you are no longer building a balloon calculator. You are building a dynamic amortization engine with rebalancing logic. That is a different product. Similarly, if the balloon payment is structured as a percentage of the original loan rather than the remaining balance, the calculation changes again. Some commercial loans use a fixed percentage balloon, like 20% of the original principal regardless of how much has been paid down. In that case, the monthly payment is calculated to leave exactly that percentage as the final balance. The solver approach I described earlier still works, but the target changes from remaining balance to a fixed dollar amount. The biggest limitation I want to flag is that no calculator accounts for fees, points, or closing costs. The payment you see in the schedule is the contractual payment. It does not reflect the true cost of borrowing if the loan carries origination fees or prepaid interest. For a complete picture, you need to incorporate those into an APR calculation, which requires a separate iteration. I usually build that as a second output tab rather than mixing it into the main schedule. Keeping them separate avoids confusion and makes the tool easier to maintain.
If you need something to download, I have a spreadsheet-based version that handles both date-based and amount-based balloons with optional prepayments. It uses actual/360 day counting and rounds at each period. The file is a Google Sheets template, so no installation is needed. Link is in the comments if anyone wants it. The core logic is transparent and you can audit every cell.