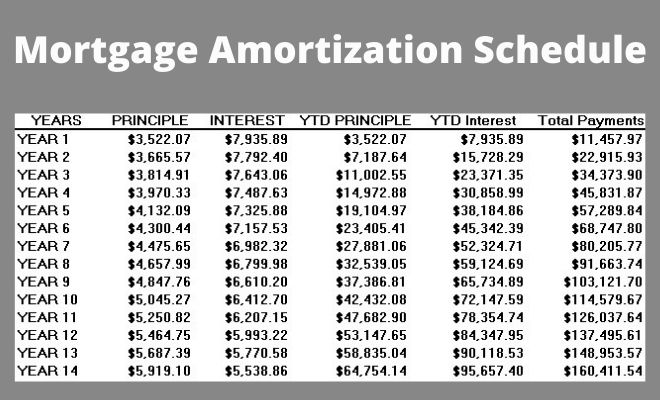
How an Amortization Chart Actually Works in Practice
An amortization chart mortgage is just a table that breaks down every payment you make over the life of a loan into principal and interest. That's it. There's nothing magical about it. You plug in your loan amount, interest rate, and term, and it shows you exactly how each monthly payment gets split between paying down what you owe and what goes to the lender as profit. Most people look at these charts and either ignore them or get confused by the numbers. I've spent years helping people understand what they're actually looking at. The standard approach is to start with the remaining balance and the annual percentage rate. Divide the annual rate by 12 to get your monthly rate. Multiply the remaining balance by that monthly rate to find the interest portion of the payment. Subtract that interest amount from your total monthly payment, and whatever is left goes toward the principal. Repeat that process for every single month until the balance hits zero. In Excel or Google Sheets, you can set this up in about ten minutes using the PMT function for the payment amount and the PPMT and IPMT functions to split each payment into its two components. The built-in Excel functions calculate with 15 digits of precision, which matters more than you'd think when you're dealing with a 30-year loan and compounding monthly.
Understanding the Amortization Chart Mortgage
The reason these charts look the way they do is because of how compound interest works in reverse. Early in the loan, most of your payment is interest. A borrower on a $400,000 loan at 6.5% for 30 years is paying roughly $2,528 per month, and in month one about $2,167 of that is interest and only $361 goes to principal. By month 180, they're still paying $2,528, but now $1,073 goes to principal and $1,455 is interest. The total payment never changes on a fixed-rate mortgage, but the split flips dramatically over time. That curve is the entire point of the chart. What most people don't realize is that the amortization schedule also tells you exactly how much equity you're building at any given point. If you want to sell or refinance, the remaining balance is right there. I had a client once who wanted to refinance after exactly five years on a $320,000 loan at 4.75% for 30 years. She thought she'd paid down a meaningful chunk of principal. The chart showed she'd only reduced the balance by $18,432. She was paying off the bank's interest first, as always. The chart didn't lie, but it was a harsh reminder she hadn't expected. One edge case that catches people off guard involves extra payments. When someone makes an additional principal payment mid-month, the amortization schedule doesn't automatically adjust unless you rebuild it. I built a custom spreadsheet for a client who was making biweekly payments instead of monthly. The standard Amortization Chart Mortgage template in Excel assumes one payment per month and won't reflect the actual payoff timeline correctly. I switched the calculation to use 26 half-payments per year, which effectively adds one extra monthly payment annually. That shortened her 30-year loan to 23 years and saved her approximately $47,000 in total interest. The difference wasn't trivial, and it only showed up when the schedule was recalculated properly for the payment frequency.
Another thing worth noting: many online calculators and spreadsheet templates round each payment's principal and interest to the nearest cent. Over 360 months, those rounding differences compound. The final payment is often a few dollars off from what a strict formula would predict. If you need pixel-perfect accuracy for legal or tax purposes, use the cumulative functions in Excel rather than manually rounding each row. The CUMPRINC and CUMIPMT functions aggregate across periods and handle the floating-point arithmetic more cleanly. The main limitation of any amortization chart is that it assumes a fixed interest rate and a fixed payment schedule. If you have an adjustable-rate mortgage, the chart becomes useless after the initial period because the rate resets based on an index you can't fully predict. For ARM loans, you need a projection model that factors in rate caps, margin adjustments, and index forecasts. A static table can't capture that. Similarly, if you plan to make irregular extra payments, the original schedule will mislead you about your payoff date and total interest cost. The workaround is to build a dynamic version where each row's starting balance is pulled from the previous row's ending balance, and you have a column for optional extra payments that recalculate the remaining term after each entry. If you're just looking for a quick reference, the core components you need are the loan amount, the annual interest rate, the loan term in years, the payment frequency, and the start date of the loan. Enter those into a spreadsheet, set up the PPMT and IPMT formulas referencing the correct period number, and drag them down for the full term. It takes longer to set up than to admit it does, but once it's built, it's repeatable for any loan you encounter.
Get the Full Details