Building Amortization Schedules That Actually Work
I spent last Tuesday debugging an amortization template where the final payment was off by $0.47. The client was furious because the schedule didn't balance to zero, and they'd already sent the spreadsheet to their accountant. Turns out the issue was cumulative rounding on the IPMT function. Each row rounded the interest portion independently, and over 360 months that added up. I switched to using a helper column that calculated the remaining balance first, then derived the principal from that, which eliminated the rounding drift entirely. That's the thing about Amortization Excel templates. Most people build them once, they work for their own loan, and they never think about edge cases until someone else tries to use it for something slightly different. The difference between a spreadsheet that works and one that falls apart usually comes down to how you handle those edge cases.
The Core Formula Structure
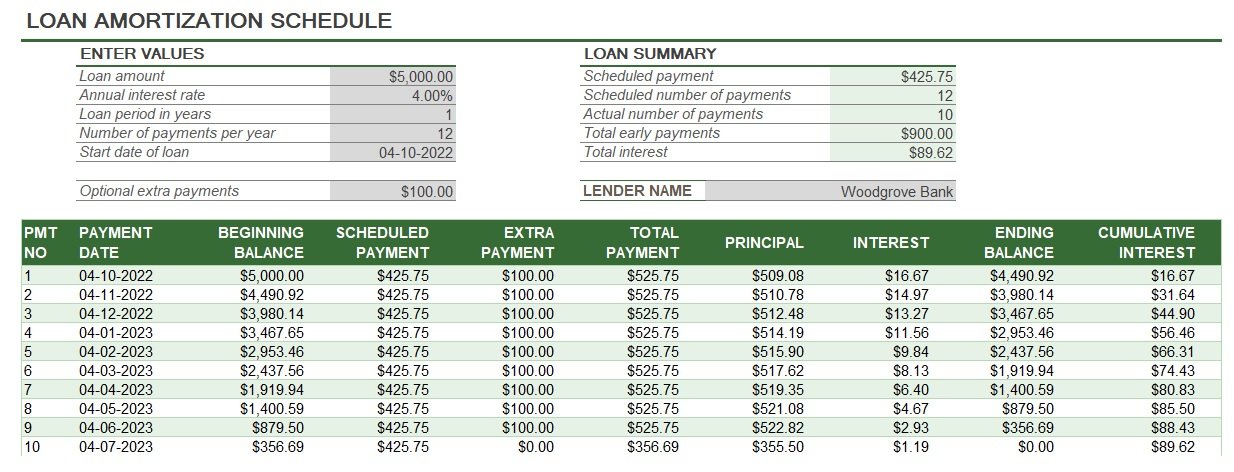
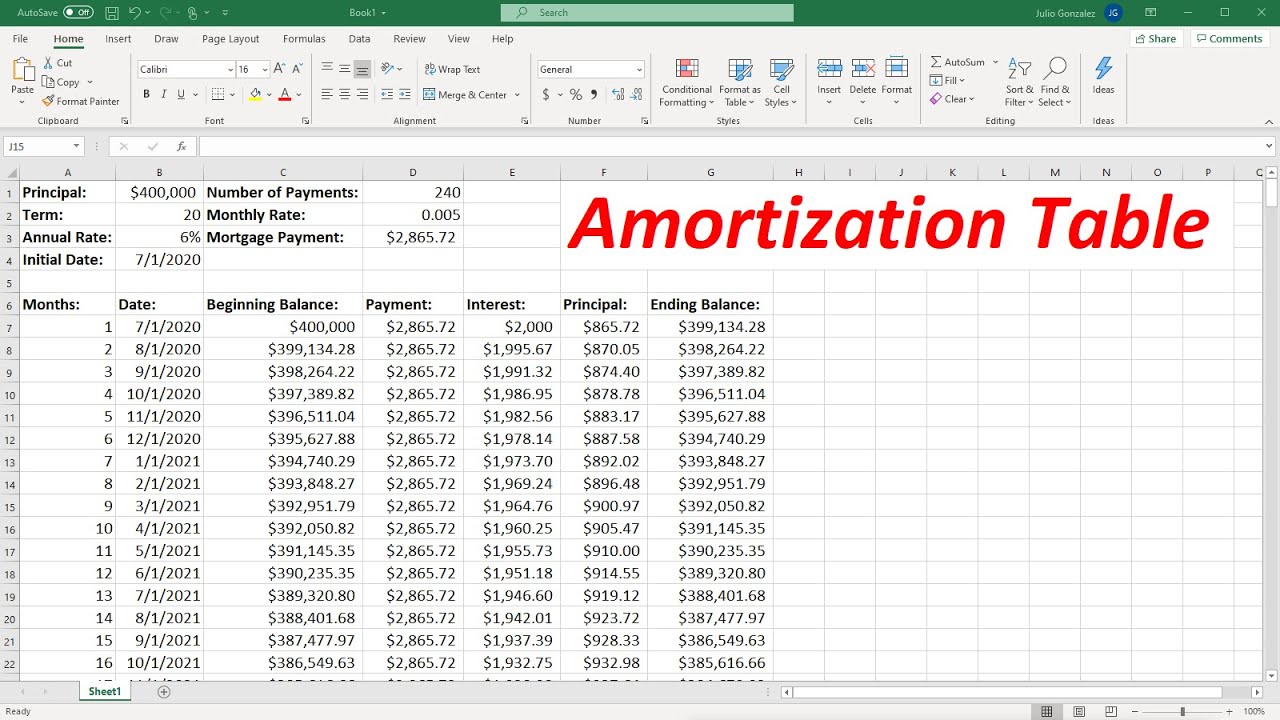
At its simplest, a loan amortization schedule tracks three things per period: the payment amount, how much goes to principal, and how much goes to interest. The payment stays constant in a fixed-rate loan, which is what most people expect. The principal portion grows over time while the interest portion shrinks. This is the opposite of what beginners assume. They think the interest decreases linearly. It doesn't. The reduction accelerates because each payment reduces the balance, which reduces the next period's interest calculation. The PMT function calculates the total payment. It needs three arguments: the rate per period, the total number of payments, and the present value. For a monthly loan, you divide the annual rate by 12 and multiply the years by 12. Easy enough. The result gives you a negative number because Excel treats payments as cash outflows. Multiply by -1 or wrap it in ABS if you want it positive. PPMT handles the principal portion. It takes the same rate, the period number, total periods, and present value, plus an optional future value and payment type. IPMT does the same for interest. These two functions together should always equal the PMT result for any given period. When they don't, that's usually where rounding or formatting errors creep in.
Setting Up a Basic Schedule
Start with headers. Period number, payment date, total payment, principal, interest, and remaining balance. Put the loan amount in a single cell somewhere visible. Link your first balance cell to that loan amount. The second balance cell subtracts the previous period's principal from the previous period's balance. Drag that formula down for the entire loan term. For the payment column, reference the PMT function once and copy it down. You could recalculate it every row, but that wastes computation. The payment doesn't change in a fixed-rate loan, so calculate it once and lock the reference. Principal and interest columns pull from PPMT and IPMT respectively. These need the period number to change in each row. Reference the period column instead of hardcoding numbers. If you delete a row later, everything shifts automatically. Hardcoded values break when the schedule grows or shrinks.
Get the Full Details
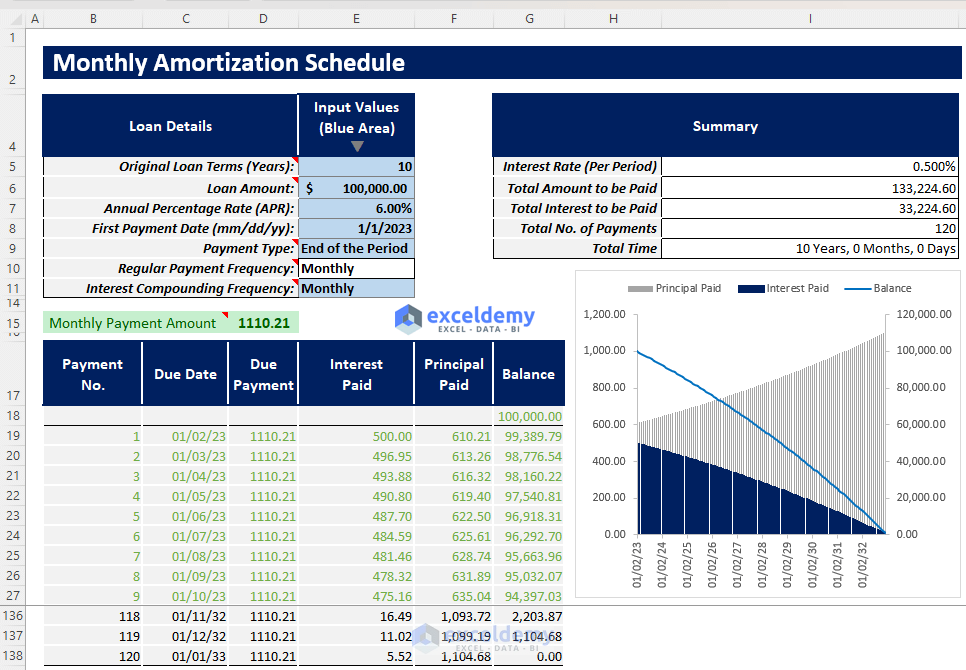
Date handling is where things get messy. Most loans don't start on the first of the month, or they have irregular first periods. The EOMONTH function helps when you need payment dates at month boundaries. But if your loan documents specify exact dates, store those separately and reference them. Don't try to calculate dates from scratch inside the amortization formula itself.
A Problem I Ran Into With Mid-Month Payments
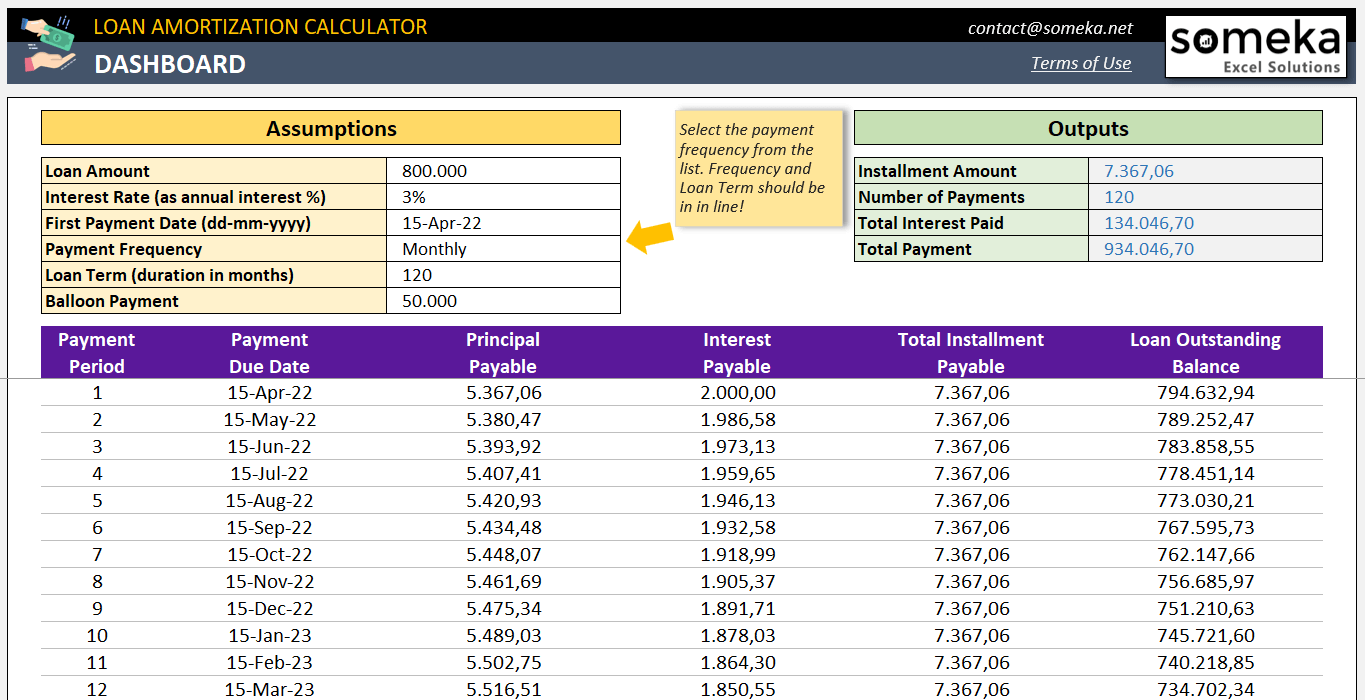
Last year a client had a mortgage that closed on the 18th of the month, with the first payment due 45 days later. Standard amortization templates assume payments happen on the same day each month. This one didn't. The first period was 27 days, the second was 31, then it settled into a pattern that never quite aligned with calendar months. The workaround involved calculating actual days between payments and using the EFFECT function to convert the nominal annual rate to an effective rate based on the actual compounding periods. Then I built a custom payment calculator that adjusted the first period's principal and interest based on the actual number of days. The rest of the schedule followed standard formulas, but the first row needed special handling. This kind of situation doesn't come up often, but when it does, a template built with rigid date assumptions falls apart immediately. Accounting for the first period separately, even if it means an extra row or two, saves hours of debugging later. The client's loan officer had rejected three different templates before I showed up with one that matched their closing documents exactly.
Common Pitfalls That Break Schedules
Rounding is the biggest one. Excel stores values with up to 15 digits of precision, but your cells might display only two decimal places. When you sum displayed values, you get a different total than when you sum the underlying precision values. Turn on the Show Precision button or use the ROUND function at each step if exact penny matching matters. Most commercial loan systems require this. Personal spreadsheets can usually get away with ignoring it unless you're doing audits. Another trap is the payment type assumption. The PMT function defaults to end-of-period payments. If your loan requires beginning-of-period payments, add zero as the fifth argument instead of leaving it blank. Some lenders actually use this convention, especially lease-style arrangements. Getting this wrong shifts your entire schedule by one period. Extra payments cause silent failures in basic templates. If someone pays an additional $200 toward principal in month 12, the standard formulas don't account for it. You need to either build in a separate extra payment column or manually adjust the balance each time. I've seen people just delete rows to simulate early payoff, which breaks the period numbering and makes the schedule unusable for tax reporting.

When Excel Isn't the Right Tool
Amortization Excel works fine for straightforward fixed-rate loans. It struggles with adjustable rates that change frequently, loans with penalty clauses, or situations where the lender applies payments in a non-standard order. If your loan has a balloon payment at the end, you can model it with the FV function, but tracking it across multiple periods gets messy. Spreadsheet limits also matter. Beyond 1,000 periods, performance degrades noticeably on older hardware. More importantly, audit trails disappear. If someone changes a formula three rows up, there's no log of who changed what and when. Financial institutions usually require documentation that Excel templates can't provide without significant manual effort. For complex scenarios, dedicated loan management software handles the math more reliably. But those tools cost money and require training. A well-built Excel template handles 90 percent of residential loan amortization needs and costs nothing extra. The key is knowing when your situation crosses that 90 percent threshold.
What to Check Before Using Someone Else's Template
Test it with a simple case first. A $10,000 loan at 6 percent annual rate over 12 months should have a payment of $860.66. If the template gives you a different number, stop and figure out why before trusting it with anything larger. Most errors show up immediately in test cases. Verify the final balance equals zero, not just approximately zero. If your schedule ends with a balance of $2.34, something is wrong. Small differences might be acceptable for personal budgeting, but they're disqualifying for any formal documentation. The rounding issue I mentioned earlier is exactly this kind of problem. It looks fine at first glance but fails scrutiny later. Check that the sum of all principal payments equals the original loan amount. This should hold regardless of interest rate or term length. If it doesn't, your principal column formulas are broken. Interest payments should sum to something close to the total interest cost, though that depends on whether you're accounting for the full term or an early payoff scenario.
Make sure the date column behaves correctly when you filter or sort. Amortization schedules are often sorted by payment date for reporting purposes. If your dates are stored as text instead of actual date values, sorting produces garbage results. Test this before submitting the schedule to anyone who might need to reorganize it. The real value of an Amortization Excel template isn't in the formulas themselves. Those are standard and available anywhere. The value is in handling the specifics of your situation correctly. A template that accounts for your actual payment dates, handles rounding appropriately, and survives extra payments without breaking will save you more time than any fancy feature ever could.