What You Actually Need to Know Before Building One
Most people don't realize a balloon mortgage amortization schedule looks normal for five, seven, or ten years and then completely falls apart the moment the balloon payment hits. The monthly payments are calculated as if the loan will amortize over a much longer period — usually 15 to 30 years — but the actual loan term is far shorter. That discrepancy is where everything gets messy. I've spent more years than I care to count dealing with commercial loans and investment property financing, and the balloon structure comes up constantly. People see low monthly payments and think they're getting a deal. They are not. Not really. The payment is low because the lender is spreading principal and interest across a long amortization window while collecting the note early. The borrower is betting they can refinance or sell before the balloon comes due.Amortization Schedule For Balloon Mortgage
The basic mechanics are straightforward. You pick a loan amount, an interest rate, an amortization period (say 25 years), and a balloon maturity date (say year 7). The monthly payment is computed using the full 25-year amortization. At the end of year 7, whatever principal remains is due in full. Here's the thing most online calculators won't show you clearly: the remaining balance at balloon maturity is not a small number. On a $500,000 loan at 6.5% amortized over 25 years, after 7 years of payments you'll still owe roughly $408,000. That's the balloon. You either pay it, refinance it, or sell the property. There is no magic in the schedule that makes it disappear. To build your own schedule, you need three inputs: principal amount, annual interest rate, and two time periods — the amortization period and the balloon term. The monthly payment formula is the standard annuity formula:
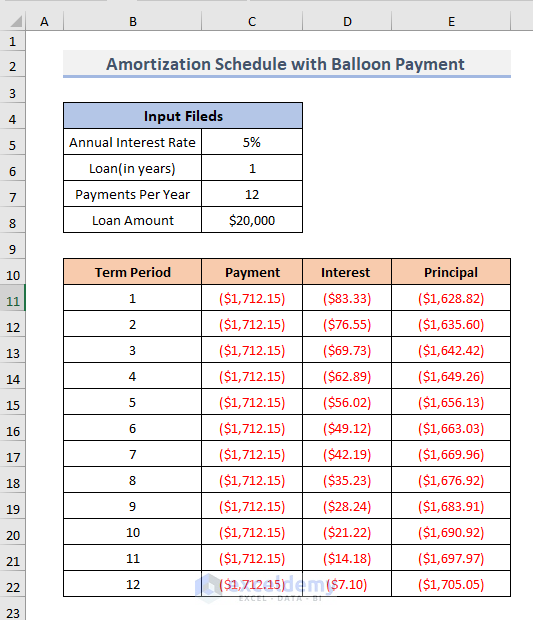
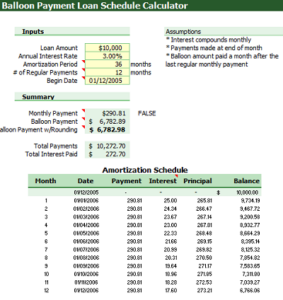
PMT = P × [r(1+r)^n] / [(1+r)^n - 1] Where P is the principal, r is the monthly interest rate (annual rate divided by 12), and n is the total number of payments over the amortization period. Once you have the payment, you build a row-by-row schedule. Each month, the interest portion is the remaining balance times the monthly rate. The principal portion is the payment minus the interest. You subtract the principal portion from the balance. Repeat until the balloon date, then record the remaining balance as the balloon payment. I used to do this by hand in spreadsheets for years. What I do now is use a structured approach. Column A is the payment number. Column B is the date. Column C is the beginning balance. Column D is the payment. Column E is the interest portion. Column F is the principal portion. Column G is the ending balance. In column E, the formula is simply C×(annual_rate/12). In column F, it's DE. In column G, it's CF. On the balloon payment row, column D becomes the entire remaining balance from column G of the prior row.
The practical problem I keep running into is that lenders sometimes use a 360-day year for interest calculations instead of 365. This is called the bank method or ordinary simple interest, and it changes every payment by a fraction of a percent. Over 84 months on a half-million dollar loan, that difference can add up to several hundred dollars in principal that shifts your balloon balance by a noticeable amount. If you're building this for a real transaction, confirm which day-count convention the lender uses before you finalize anything. A $300 variance seems small until you're closing and the numbers don't match the lender's disclosure documents. Another edge case that caught me recently involved a partially prepayable balloon. The borrower made a $75,000 lump-sum payment in month 31. Most standard amortization calculators don't handle this cleanly because they assume consistent payments. The workaround is to insert a new row at the point of prepayment, recalculate the remaining balance, and then continue the schedule from that point forward using the same payment amount but a reduced remaining term. The payment itself doesn't change in a standard balloon — only the balance does. So after the prepayment, you just carry the old payment amount forward and let the schedule naturally reach zero faster than originally planned, or you recalculate the payment if the loan terms allow for it. What people miss when they look at a balloon mortgage amortization schedule is that the equity buildup in the early years is painfully slow. In the first three years of a 25-year amortization at 6.5%, roughly 70 to 75 percent of each payment goes entirely to interest. If you're counting on appreciation to cover the balloon, you need realistic assumptions about the market. I've seen borrowers walk into year seven expecting a 15 percent property value increase that never materialized, leaving them unable to refinance and forced to sell at a loss.
Get the Full Details

The biggest structural weakness of balloon mortgages is the refinancing risk. The schedule assumes you can refinance at the end of the term. But if credit markets tighten, if your income changes, if the property value drops, or if the lender simply decides not to renew, you're underwater with a payment due in 30 days. There is no buffer in the schedule. No row says "good luck." The remaining balance is the remaining balance. If you need a downloadable template, I built a Google Sheets version that handles the standard case and the prepayment edge case. The sheet uses conditional formatting to highlight the balloon payment row in red so it doesn't get overlooked. The core formulas are in columns E through G as I described above. You only need to change the four input cells at the top: loan amount, annual rate, amortization years, and balloon term in years. Everything downstream recalculates automatically. One more thing worth noting — and this is the part that separates people who understand these loans from people who get burned by them. Some balloon mortgages include a yield maintenance clause or a prepayment penalty that extends well beyond the balloon date. This means even if you want to pay off the loan early after the balloon matures, you might still owe significant penalty interest. The amortization schedule itself won't show this. It's buried in the promissory note. Always read the note separately from the payment schedule. They are two different documents and they don't always tell the same story.