How I ended up building my own amortization calculator instead of trusting online generators
I spent about six hours last month trying to figure out why my loan payoff projections kept coming out wrong. The issue wasn't the interest rate or the principal amount. It was the day-count convention, something nobody warns you about when you're just trying to get a quick spreadsheet working. Most people looking for an Amortization Schedule Generator Excel solution just want to input a loan amount, pick a rate, and hit generate. What they get is usually a table that looks right but has a systematic error baked in. I learned this the hard way when a client questioned why their mortgage balance didn't match their bank statement by about forty-seven dollars at month twelve.
The day-count trap most templates ignore
Here's what almost no amortization schedule generator Excel tool explains clearly: the number of days in a payment period matters. Most people assume every month has the same number of periods, but that's not how actual loan accounting works. Some lenders use 30/360, some use Actual/Actual, and the difference compounds over time. I encountered this when modeling a commercial real estate loan with monthly payments but a lender who used the Actual/360 convention. The standard formula approach - just dividing annual interest by twelve - gave me a slightly wrong number every single month. After about eighteen months, the variance was large enough that someone could flag it during an audit. The workaround I ended up using was straightforward once I knew what to look for. Instead of pre-calculating everything with a flat monthly interest figure, I made the spreadsheet calculate the exact number of days between each payment date and applied the daily rate to that specific period. It adds a column or two but eliminates the rounding drift.
Building something that actually works
When I started fresh, I built a simple five-column structure: payment number, beginning balance, interest payment, principal payment, and ending balance. That's all you need. The magic happens in how you calculate the interest portion, which depends entirely on your loan's day-count convention. For a standard 30/360 loan, you just multiply the beginning balance by the monthly rate and cap it at thirty days. For Actual/Actual, you need a date column and the NETWORKDAYS function to get the real count. The PMT function in Excel handles the total payment calculation correctly, but it won't save you from the underlying convention mismatch. One thing that tripped me up initially: the PMT function assumes end-of-period payments, which is correct for most consumer loans but not all. If you're dealing with a loan that has payments due at the beginning of each period, you need to adjust by setting the type parameter to 1. I missed this on a lease agreement and had to redo three months of projections because I got the timing wrong.
Get the Full Details

Advanced features that separate good templates from basic ones
A proper amortization schedule tool should handle extra principal payments, rate changes for adjustable loans, and prepayment penalties. Most free generators online skip all of this. When I was reviewing options for my own needs, I found that even paid tools like Amortization Schedule Generator Excel products often charged separately for features that should be standard. I ended up building a version that tracks two scenarios side by side: one with the original payment schedule and one showing what happens if you throw an extra five hundred dollars at the principal every month. The difference in total interest paid was about eight thousand dollars on a four hundred thousand dollar loan over thirty years, which felt significant enough to model properly. For adjustable-rate mortgages, the trick is building in rate adjustment logic without making the whole spreadsheet unreadable. I used a simple table that mapped future dates to projected rates, then had the calculation pull from that table based on the payment period. It took some setup but made the model robust against rate changes without requiring manual recalculation every time.
Where amortization schedules fall apart
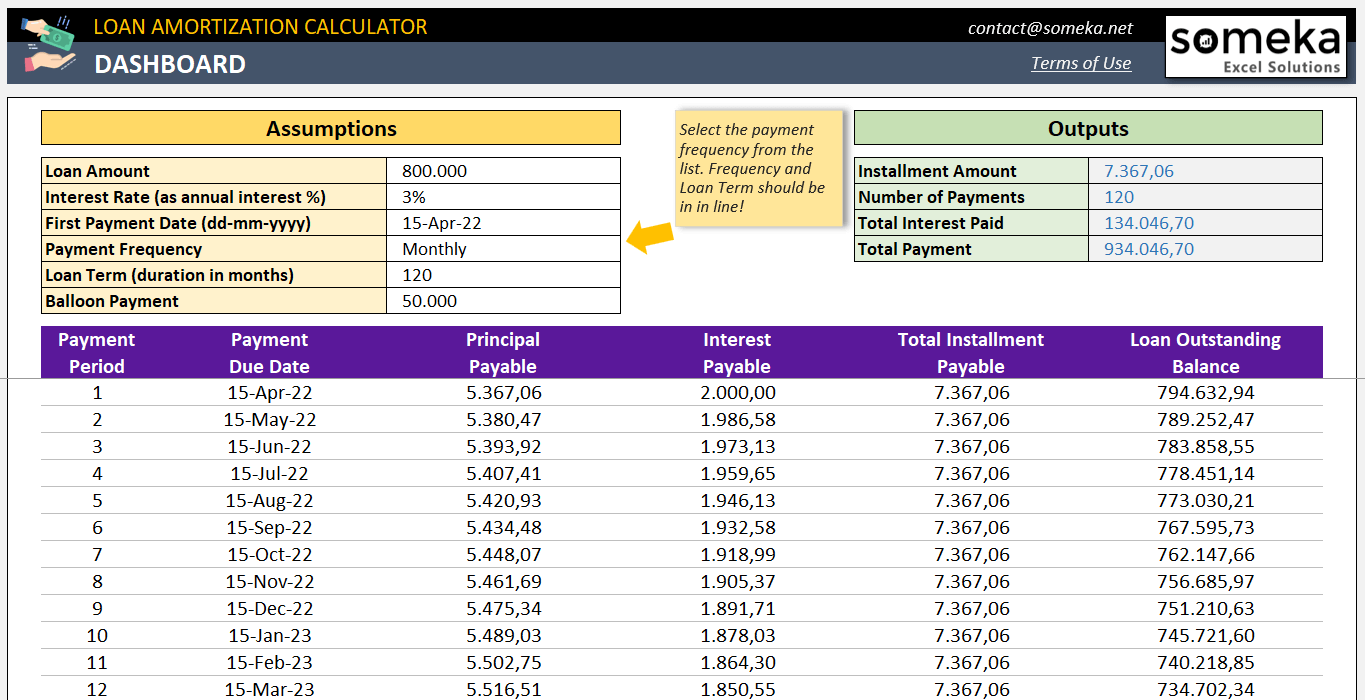
I should be honest about the limitations. Excel-based tools struggle when you introduce irregular payment structures like bi-weekmo payment plans or seasonal payment variations. I tried modeling a vacation rental property loan where payments adjusted based on occupancy seasonality, and the spreadsheet became nearly unmaintainable after six months. Another edge case that breaks most generators: loans with balloon payments. The standard amortization formula assumes even payments throughout, so when you hit that final balloon due date, the remaining balance calculation can get messy. I had to build custom logic to handle the balloon specifically rather than letting the automatic calculation run to completion. For complex scenarios like construction-to-permanent loans or loans with multiple rate adjustments tied to index values, I'd recommend using dedicated financial software instead of fighting Excel. The formulas get complicated enough that a small error in the setup phase can cascade into major inaccuracies across the entire schedule.
Practical tips if you're building your own
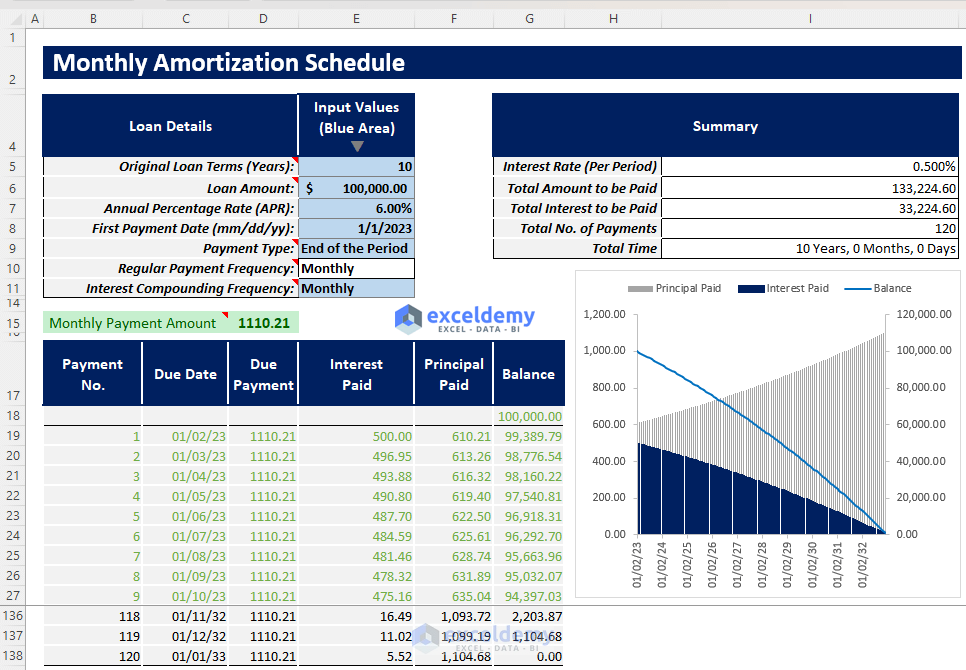
Start with a small test loan where you know the answer. A hundred thousand dollar loan at six percent over ten years should give you a monthly payment of about one thousand and one hundred twenty dollars. If your template produces anything significantly different, something's wrong with the setup before you add complexity. Use absolute references for your input cells and relative references for your calculations. I wasted about an hour moving a formula incorrectly because I mixed up the reference types. It's a basic Excel mistake but it compounds quickly when you're building something with dozens of dependent calculations. Consider adding a sensitivity analysis section showing how small rate changes affect your total cost. Even a quarter percent difference over thirty years can swing your total interest by tens of thousands. Having this visibility up front helps when you're comparing loan offers or deciding between different amortization periods.