How an Amortization Schedule Actually Works in Practice
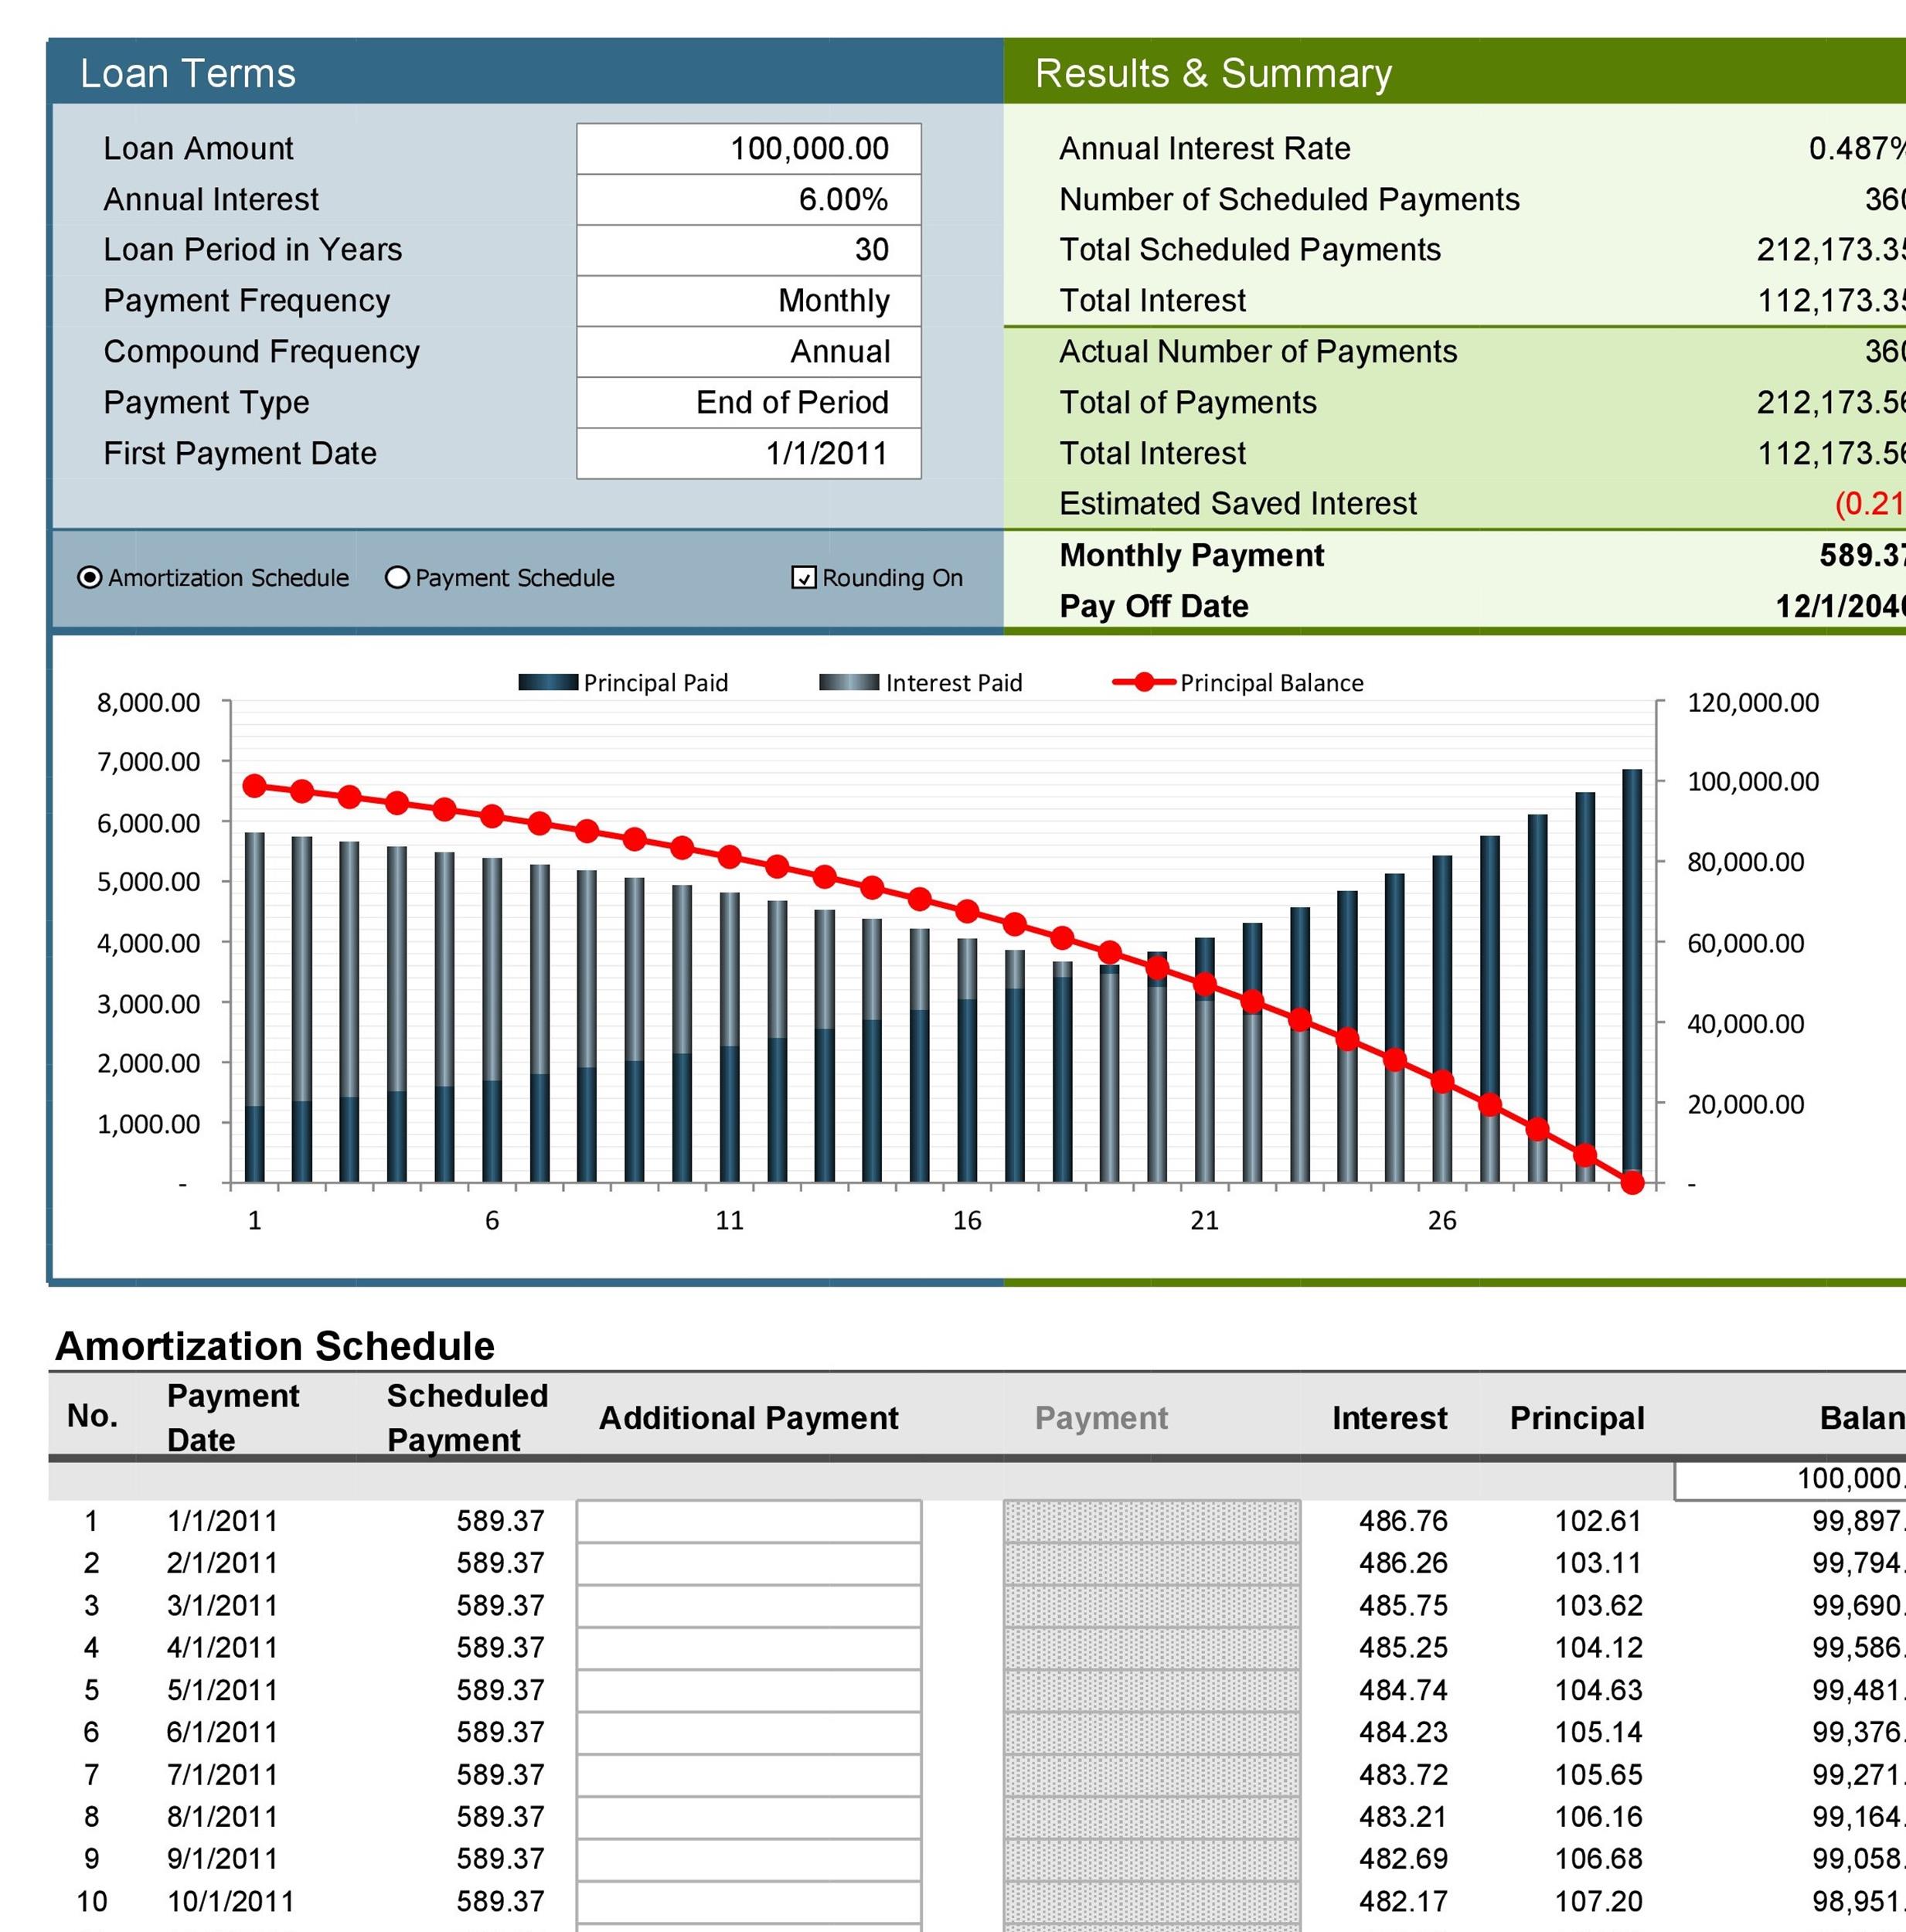
An amortization schedule is simply a table that breaks down each loan payment into principal and interest over time. That's it. The more interesting question is why people keep reinventing the wheel when Excel already has everything you need built in. I built custom amortization calculators for about three years before someone pointed out that the PMT, PPMT, and IPMT functions do all the heavy lifting. That cut my setup time from about forty-five minutes to under five per template.
Building Your Own Amortization Schedule In Excel Template
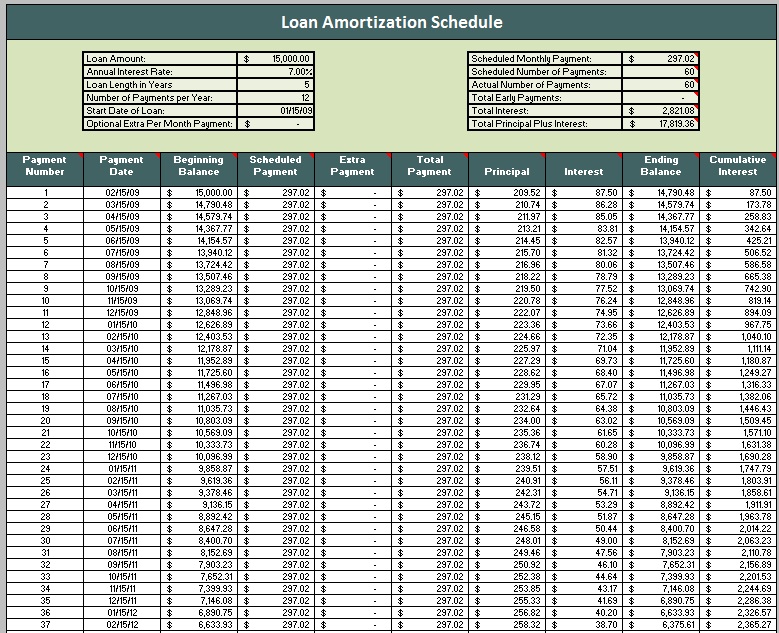
Start with the basic inputs at the top of your sheet. You need the loan amount, annual interest rate, loan term in years, and the start date. These four cells drive everything else. Put them in a clean block so they're easy to find and modify without scrolling. The trick most people miss is converting the annual rate to a monthly rate and the years to total payments. Excel's PMT function expects the rate per period and the number of periods, not the annual figures. So if your rate is 6.5 percent and the term is 30 years, you divide the rate by 12 and multiply the years by 12. Simple enough, but I've seen too many templates calculate everything on an annual basis and then wonder why the numbers don't add up to the monthly payment the borrower actually owes. Once your inputs are set, you build the payment schedule row by row. Column A gets the period number. Column B pulls the date using the DATE function based on your start date plus the period offset. Column C is your payment amount, which stays constant across a standard fixed loan. That's the PMT formula referencing your input cells.
Column D calculates the interest portion for that specific period using the IPMT function. Column E gets the principal portion with PPMT. Column F tracks the remaining balance, which is where most templates fall apart. The formula should take the previous balance minus the current period's principal payment. If you reference the wrong cell or skip a row, the whole schedule derails and you won't notice until the final balance doesn't hit zero.
Get the Full Details
Common Pitfalls That Waste Hours
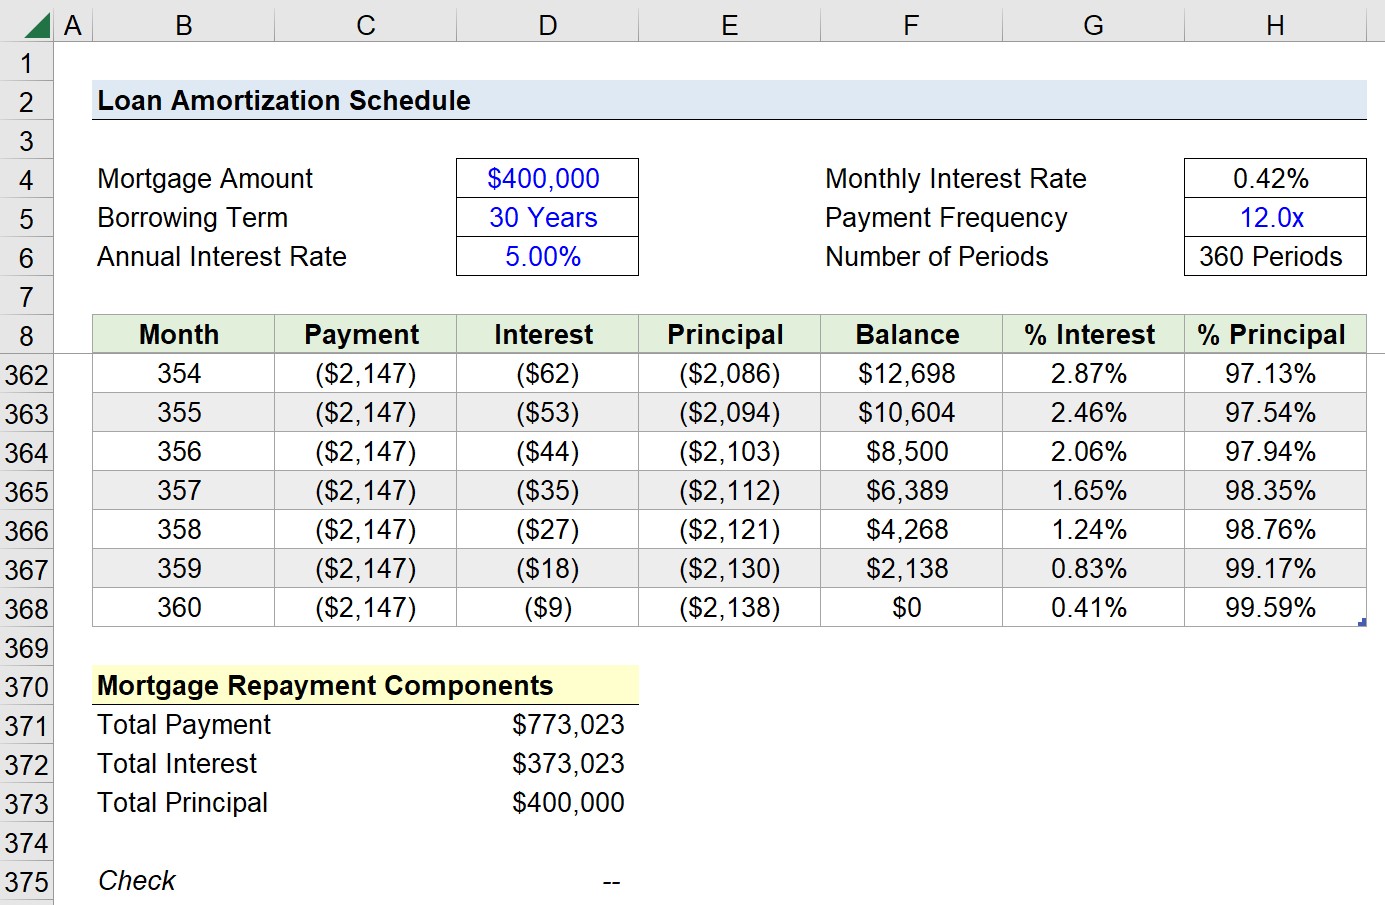
The most common problem I encounter is rounding. Excel stores numbers with far more decimal places than it displays. When you format cells to show two decimals, the underlying value still has thirteen or fourteen digits of precision. If you sum the displayed values, they won't reconcile. Always use ROUND on your interest and principal calculations, or better yet, round the payment amount itself and adjust the final period to absorb any penny differences. I ran into this exact issue last year when a client handed me a schedule where the final balance was off by thirty-seven cents. The root cause was a payment calculated with full precision but displayed as a rounded number, and then every subsequent calculation used the displayed rounded figure instead of the actual stored value. The fix was wrapping the PMT output in ROUND(,2) and adding a plug adjustment to the last row's principal column. Another subtle issue is the day-count convention. Most consumer loans use a 30/360 method, meaning every month is treated as thirty days regardless of actual calendar length. Mortgage loans sometimes switch to actual/360, which can shift your interest calculations by a day or two per quarter. If you're building a template for a specific loan product, confirm the convention first. A template that assumes 30/360 will produce slightly wrong numbers on an actual/360 loan, and the discrepancy compounds over time.
Advanced Features Worth Including
If you're going to spend the time building a template, add a cumulative interest column. This shows total interest paid year by year, which is the number lenders and tax professionals actually care about. It's one SUMIF formula per year referencing the interest column and checking whether the period falls within that calendar year. A principal breakdown chart is also useful. A simple clustered column chart plotting principal versus interest across all periods makes it immediately obvious how the payment composition shifts over the life of the loan. Early payments are almost entirely interest. The crossover point where principal exceeds interest happens somewhere around the middle for a standard thirty-year mortgage, but the exact timing depends on the rate and term. I once built a version that calculated the exact midpoint by solving for when the cumulative principal equals half the loan amount. It required an iterative approach using Goal Seek because there's no closed-form solution for arbitrary rates and terms. Not something you need for everyday use, but worth knowing exists.
When Excel Is Not the Right Tool
Amortization schedules in Excel work fine for straightforward fixed-rate loans. They break down when you introduce variable rates, balloon payments, or irregular payment dates. If the loan has an adjustable rate that resets quarterly based on an index plus a margin, you need a separate calculation block for each adjustment period. The template becomes unwieldy fast. Commercial real estate loans often have these complications. I've seen people try to force a CRE amortization schedule into a standard Excel template and end up with a spreadsheet that has more formulas than actual data. In those cases, a dedicated loan management tool or a short Python script using the numpy_financial library produces cleaner results with less maintenance. The same goes for amortization schedules with extra payments. If your borrower makes additional principal payments irregularly, the schedule needs to recalculate every period from that point forward. Excel can handle this, but it requires either a dynamic array setup or a lot of manual intervention. I usually just add a note in the template that says "add extra payments in column G and the schedule recalculates automatically from that row onward," which saves me from building something overly complex for a feature most users won't touch.
Getting Started With an Amortization Schedule In Excel Template
The fastest path is to start with a blank sheet, lay out your five input cells, build the payment row with PMT, IPMT, and PPMT, then drag the balance formula down for however many periods you need. Add conditional formatting to highlight the principal-versus-interest ratio shifting over time. Test it by plugging in a known example, like a twenty-thousand-dollar loan at seven percent over five years, and verify the output against a calculator you trust. If you want a starting point, Microsoft's own template library has a functional amortization schedule you can download and modify. It's not elegant, but it's correct and it gives you a reference for the formula structure. From there you adapt it to your specific use case, whether that's personal loan tracking, client deliverables, or internal analysis. The template approach works because once you've built it, you can reuse it across dozens of loans without rebuilding the logic each time. That's the actual value proposition. Not the schedule itself, but the fact that you never have to reconstruct the payment formulas from scratch again.