How Balloon Payment Amortization Actually Works
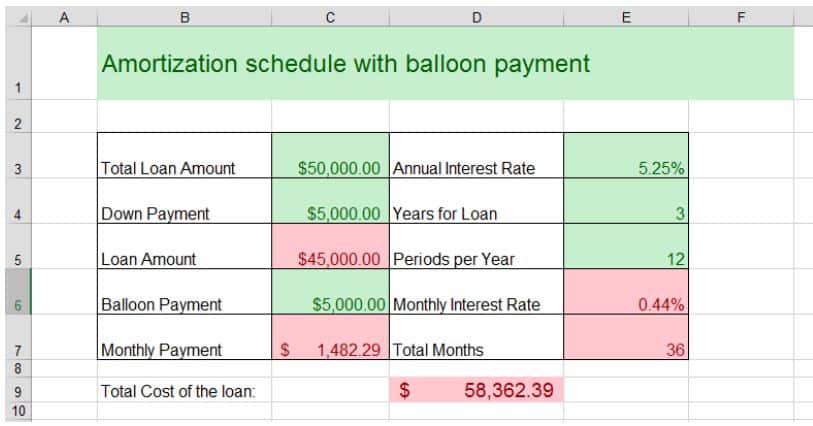
Most people misunderstand what happens at the end of a balloon payment loan. The standard amortization schedule you see month-to-month is calculated as if you're going to pay this off over the full term. But then, at a predetermined point—usually years before the loan would naturally be paid off—a massive lump sum comes due. That lump sum is the balloon payment, and it's not some mysterious extra charge. It's simply the remaining principal balance that was never amortized out. Here's what that means in practice. Say you take out a $200,000 loan at 6.5% interest for 30 years. Your monthly payment is calculated to pay that off over 30 years, which comes to roughly $1,264. But instead of actually making those payments for 30 years, you agree to pay off the entire remaining balance after seven years. Your monthly payment stays the same at $1,264 for those seven years. Then at the end of year seven, you owe whatever principal is left. In this case, after making 84 payments, you'd still owe approximately $172,000. That's your balloon. The calculator for this isn't particularly complex, but the way it structures the output matters a lot. A proper Amortization Schedule With Balloon Payment Calculator breaks down each payment period, showing how much goes to interest versus principal, and then flags the final balloon amount clearly. Without that clear visual separation, it's easy to miss just how much principal you've actually paid down—which, in the example above, is only about $28,000 after seven years of seemingly normal payments. That's the shock most borrowers don't expect.
Using the Amortization Schedule With Balloon Payment Calculator
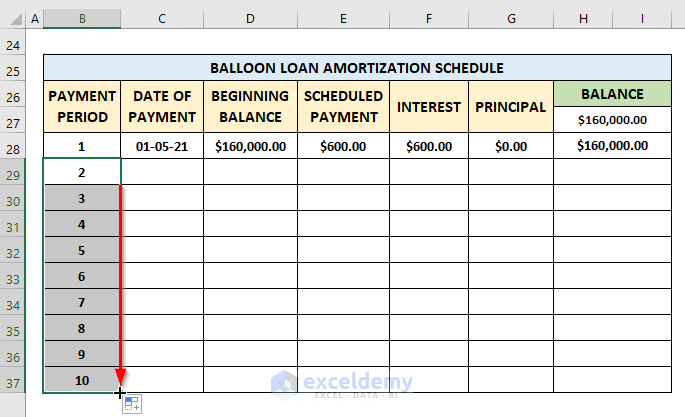
The inputs you need are straightforward. You'll enter the loan amount, the annual interest rate, the full amortization term (how long the loan would take to pay off at these payment levels), and then the balloon date—that's when the lump sum is due. Some calculators ask for this as a number of years or months until the balloon. Others let you pick the exact date. Both work, but the date picker is generally more reliable because it avoids off-by-one errors around leap years and payment schedules. Once you hit calculate, the output should give you two things: the regular monthly payment amount and the balloon payment amount. Beyond that, a good schedule shows every payment period with its interest portion, principal portion, and remaining balance. That's where the real value sits. The monthly payment number alone tells you almost nothing about whether this loan structure actually works for your situation. I once had a client who was working with a lender who only showed the monthly payment on a balloon loan without a full schedule. The payment looked reasonable—under what she could comfortably afford. But when I ran the numbers through a proper schedule, the balloon came out to over $140,000 after five years on a $195,000 loan. She'd been making payments that barely touched the principal. The lender framed it as "just refinance at that point," which is technically true but ignores the fact that refinancing requires equity, good credit, and a favorable market. Five years out, none of those were guaranteed.
That's the single biggest pitfall with balloon payment loans. Everyone focuses on the monthly payment because it's the number that fits in their head. Nobody wants to look at the balloon. But the balloon is the part that can actually destroy you. A well-structured balloon loan makes sense when you have a concrete plan to sell the asset or refinance within the balloon window. It falls apart the moment that plan becomes uncertain.
Get the Full Details
The Mechanics Behind the Numbers
Understanding the calculation helps you spot when a calculator might be giving you misleading results. The monthly payment on a balloon loan uses the standard amortization formula based on the full loan term, not the balloon term. So if the full term is 30 years and the balloon is due in 7, the payment is calculated as though you're paying for 30 years. The formula is the standard one: M = P [ i(1+i)^n ] / [ (1+i)^n – 1 ], where P is the principal, i is the monthly interest rate, and n is the total number of payments over the full amortization period. What most people don't realize is that the balloon payment amount isn't independently calculated. It's derived by running a full amortization schedule for however many periods you'll actually make payments, then reading off the remaining balance. That remaining balance is your balloon. Any discrepancy between what a calculator shows and what a bank's system shows usually comes from day-count conventions. Some lenders use 30/360, some use actual/365, and a few use actual/360. For a standard residential loan, 30/360 is by far the most common, but commercial loans sometimes shift to actual day counts, which can change your balloon by a few hundred dollars depending on the loan size and timing. Another thing that trips people up: the interest-only trap. Some balloon loans are structured so that payments are calculated on an interest-only basis for the entire balloon period. In that case, your principal never decreases during the payment window, and the balloon is essentially the full original loan amount plus any missed or deferred interest. These loans look deceptively cheap month-to-month. A $300,000 loan at 7% with interest-only payments for five years means you're paying $1,750 a month and still owe $300,000 at the end. That's a very different risk profile than a standard amortizing balloon.
When I'm reviewing a balloon loan schedule, I always check whether the payments are fully amortizing or interest-only. If the borrower thinks they're paying down principal when they're actually just paying interest, that's a mismatch that needs to be flagged immediately. The calculator output will show a declining balance for amortizing loans and a flat balance for interest-only. If neither matches your expectation, go back to the loan documents and check the payment structure before signing anything.
When Balloon Payment Schedules Make Sense and When They Don't
Balloon loans exist because they serve a specific purpose. They're commonly used in commercial real estate, construction financing, and situations where the borrower expects a liquidity event—sale of the property, refinancing into a conventional loan, or proceeds from a business deal. The shorter term means higher monthly payments than a comparable traditional loan, but the overall interest cost is usually lower because you're not paying interest for three decades. For an investor who plans to flip or refinance within five to seven years, that interest savings can be significant. They don't make sense when the borrower is using the low initial payment as the primary decision factor without a realistic exit strategy. I've seen this repeatedly in small business lending. A borrower qualifies for a balloon SBA loan because the payments are manageable, but they don't have a clear path to sell the business or refinance within the balloon window. Two years in, the market shifts, refinancing rates spike, and the balloon comes due with no way to pay it. The result is almost always distress sale or default. The stress test you should run on any balloon loan is simple. Take the balloon payment amount and ask: can I realistically generate this from the asset or my income within the balloon period? Not "might I," but "do I have a contract, a signed LOI, a confirmed refinance pre-approval, or a documented plan?" If the answer is vague, the loan structure is working against you.

There's also the refinancing risk to consider. Even if you have a solid plan today, interest rates move. A loan that looks attractive at 6.5% might need to be refinanced at 9% or higher when the balloon hits. That changes the math considerably. A good rule of thumb is to model your balloon refinance at a rate 200 to 300 basis points above your current rate. If the numbers still work at that higher rate, the loan structure is more resilient than it appears at first glance.
Common Errors to Watch For in Calculator Output
Not all online calculators for balloon payment amortization are built the same way. Some round aggressively, some use simplified formulas, and a few have bugs that become apparent only at certain input combinations. Here are the issues I've encountered most often. Rounding errors compounding over time. Some calculators round each monthly principal and interest figure to the nearest cent before carrying it forward. Others keep full precision and only round the final balloon amount. Over a 120-month payment window, the difference can add up to several hundred dollars. For most borrowers this doesn't matter, but if you're doing this for underwriting or legal purposes, you need a calculator that maintains full precision through the schedule. Wrong assumption about payment timing. Standard amortization assumes payments are made at the end of each period. Some calculators incorrectly model beginning-of-period payments, which shifts every balance figure by one period. The monthly payment amount stays the same, but the remaining balance at the balloon date will be off. This is harder to catch because the payment itself looks correct. Always verify by checking the first two rows of the schedule. If the interest in month one equals the principal times the monthly rate, it's end-of-period. If it's slightly less, payments may be modeled as beginning-of-period.
Ignoring fees in the total cost calculation. Many free calculators show you the balloon amount and the monthly payment but don't include origination fees, points, or closing costs in any total cost metric. If you're comparing a balloon loan against a conventional loan, those fees matter. A 1-point origination fee on a $250,000 loan is $2,500, and that's real money that affects your effective cost of borrowing. Factor it into your comparison, or you're comparing two loans on different terms. Mixing up the balloon term with the amortization term. This is the most common user error, not a calculator error. People enter the balloon period (say, 7 years) as the amortization term, which gives them a completely wrong monthly payment and an incorrect balloon amount. The amortization term is how long the payment schedule is calculated over. The balloon term is when the lump sum is due. They're almost never the same number. Always double-check which field is which before you trust the output.

A Practical Walkthrough
Let's walk through a concrete example so you can see what a proper schedule looks like and where things can go wrong. You're looking at a $450,000 commercial loan at 7.25% annual interest, fully amortizing over 25 years, with a balloon payment due after 8 years. The monthly payment calculation uses the full 25-year term, so n equals 300 months and the monthly rate is 0.6042% (7.25 divided by 12). That gives a monthly payment of approximately $3,047. Now you run the schedule forward 96 months—eight years of payments. Each month, the interest portion is the remaining balance times the monthly rate, and the principal portion is the payment minus that interest. Early on, the interest portion dominates. In month one, you're paying about $2,719 in interest and only $328 toward principal. By month 96, the interest portion has dropped to roughly $2,280 and the principal portion has risen to about $767. After 96 payments, the remaining balance comes out to approximately $417,000. That's your balloon. So you've made 96 payments totaling about $292,500, of which roughly $220,000 went to interest and $30,000 went to principal. You still owe $417,000. The effective cost of this loan structure depends entirely on what you do at the balloon date. If you refinance at the same rate into another 25-year loan, your payments stay similar and the cycle repeats. If you sell the property, the $417,000 needs to come from the sale proceeds. If rates have jumped to 10%, refinancing becomes significantly more expensive and may not be feasible depending on the property's cash flow.
The schedule itself is useful beyond just finding the balloon amount. It shows you the pace at which equity builds, which matters if you're planning to refinance based on appraised value rather than just cash flow. It also reveals whether the loan has any negative amortization, which some balloon structures include. If your payment is less than the interest due in any month, the unpaid interest gets added to the principal, and your balloon payment grows larger than it would have otherwise. That's a trap that's easy to miss if you only look at the summary numbers. If you're building your own calculation tool or evaluating one, make sure it outputs the full schedule, not just the summary figures. The schedule is where the risks and opportunities live. Summary numbers can hide the fact that you're barely making progress on principal, or that the balloon is larger than expected because of deferred interest, or that the effective annual rate is meaningfully higher than the stated rate once fees are included. A proper Amortization Schedule With Balloon Payment Calculator gives you all of that in one view, and it saves you from learning the hard way what the monthly payment number alone won't tell you.