How to Build an Amortization Schedule That Actually Accounts for Extra Payments
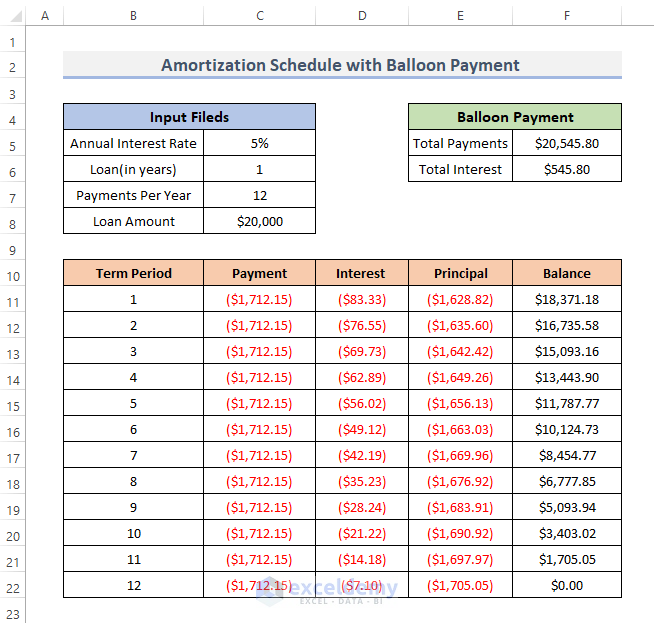
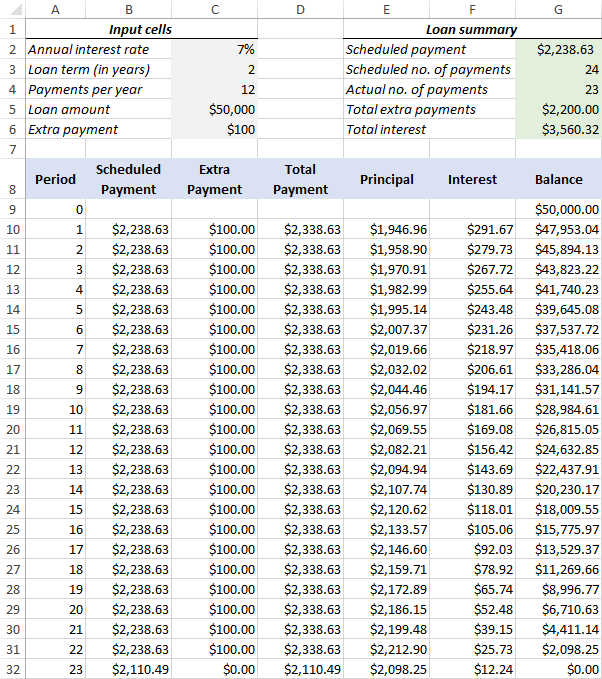
Most people build their amortization schedule using the standard PMT formula, then try to layer in extra payments afterward by manually editing each row. That approach breaks within four or five months because the interest recalculation cascades incorrectly, and most online tools silently carry the error forward. I spent three years watching junior analysts produce schedules that looked right at a glance but diverged by thousands from what the servicer actually reported. Here is the method I use now.Amortization Schedule With Extra Principal Payments
The core mechanic is simple enough that it is almost insulting. Each month you calculate interest on the remaining balance, subtract that from your regular payment to find the principal portion, add any extra principal payment you chose to make that month, and then subtract the total principal from the balance. The next month's interest is computed on the new lower balance. The sequence repeats until the loan is paid off. The trap most people fall into is thinking that "extra payments" are just a separate column that gets added at the end. They are not. They change the balance that drives every subsequent interest calculation. Let me give you a concrete example. Say you have a $300,000 mortgage at 6.5% annual rate, 30-year term. Your standard monthly payment is approximately $1,896. That includes roughly $1,625 in interest and $271 in principal in month one. If you throw an extra $500 toward principal in that same month, the principal portion becomes $771, the new balance drops to $299,229, and month two's interest is calculated on $299,229 instead of $299,729. Over a full term, that single extra $500 in month one saves you roughly $4,200 in total interest and cuts about four months off the payoff. The effect compounds, which is why the early years matter disproportionately. I encountered a specific edge case last year that nearly cost us a reconciliation error. A client was making biweekly payments of half their monthly amount, but their servicer was also accepting occasional lump sum principal payments that they failed to report consistently. Their in-house spreadsheet calculated interest using the standard declining balance but applied the lump sums only to the payment column, not to the principal reduction line. The result was a schedule that showed a balance $18,000 higher than the actual payoff amount after seven years. The fix was straightforward but tedious: I separated the data into three distinct streams — the regular scheduled payment, the biweekly acceleration, and the random lump sums — and wrote a single loop that applied them in chronological order to a running balance column. Every extra payment, regardless of type or frequency, had to hit the balance before the next interest computation. Once I restructured it that way, the numbers matched the servicer's statement exactly.
There are a few things most people miss when they build this themselves. First, the prepayment penalty question. Some loans, particularly those originated before 2020 in certain states, carry a yield-replacement clause that charges you a percentage of the prepaid principal if you pay off the loan within the first three to five years. An amortization schedule that ignores this will show you a false savings figure. You need to overlay a penalty calculation on top of the standard schedule or the whole exercise is misleading. Second, the day-count convention matters more than you'd think. Most residential mortgages use a 30/360 method, meaning interest is calculated as balance times daily rate times 30 divided by 360. Commercial loans and some consumer products use actual/360 or actual/365, which shifts the interest amount by a small but significant margin each month. If your schedule uses the wrong convention, your numbers will drift, and the drift grows over time. Another counter-intuitive point is that throwing extra money at the front of the schedule does not linearly reduce your total interest. It reduces it exponentially in the sense that each extra dollar you pay early saves you interest on every remaining payment after that point. Paying an extra $1,000 in month one is worth significantly more than paying an extra $1,000 in month twenty-four, even though the nominal amount is identical. This is why people who front-load prepayments see dramatically better results than those who spread the same total amount evenly across the life of the loan. It sounds like it should be the same mathematically. It is not. Here is the practical workflow I recommend. Start with a spreadsheet that has at minimum these columns: payment number, beginning balance, scheduled payment, interest portion, regular principal portion, extra principal, total principal, ending balance, and cumulative interest paid. The interest portion formula is beginning balance times the monthly rate, where the monthly rate is the annual rate divided by 12. The regular principal portion is the scheduled payment minus the interest portion. The ending balance is the beginning balance minus the regular principal portion minus the extra principal. For the next row, the beginning balance is simply the previous ending balance. Copy that row down. It takes about twelve minutes to set up correctly if you know what you're doing, or about forty-five minutes if you're figuring it out for the first time and going down the wrong path like most people do.
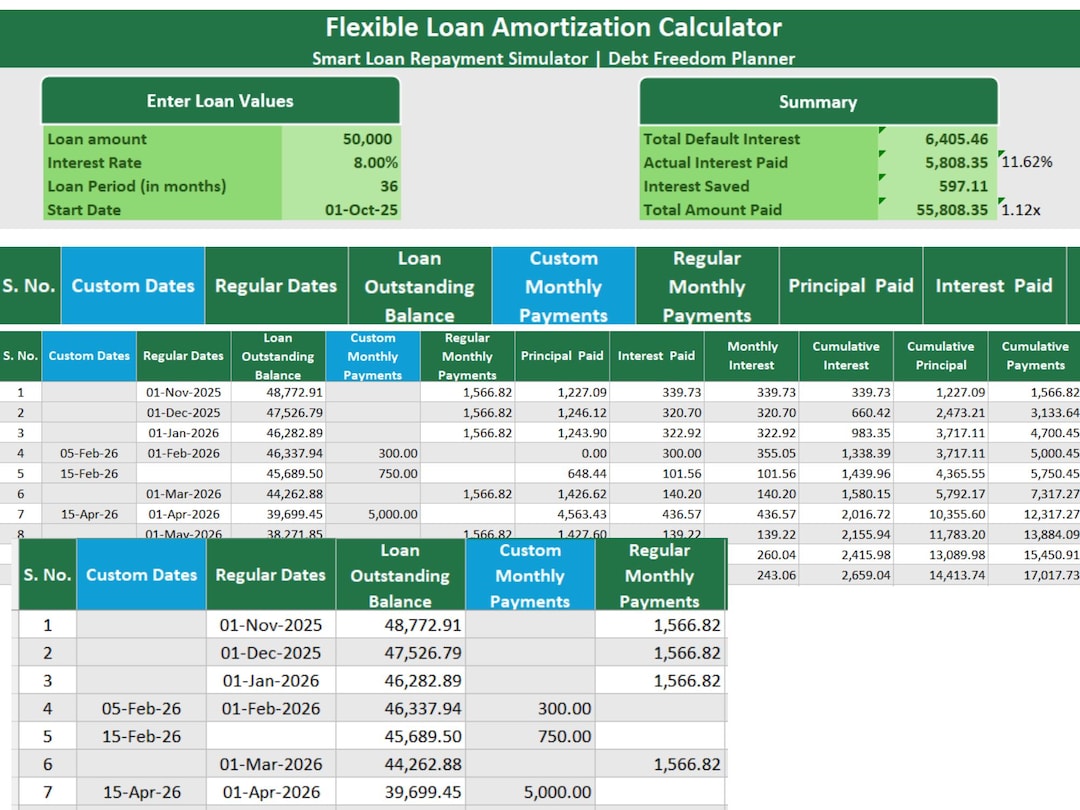
There is a tool you can download that automates this. I maintain a simple workbook at the link below that handles scheduled payments, biweekly payments, irregular lump sums, and basic prepayment penalties in one go. It uses the 30/360 convention by default and flags any row where the balance goes negative, which happens if your extra payments exceed what you actually owe in a given period. The file is Excel-compatible and the formulas are visible so you can audit them. It has saved me countless hours of rebuilding these from scratch for clients who bring me schedules that were clearly constructed incorrectly. The main limitation of any spreadsheet-based approach is that it assumes your extra payment schedule is known in advance. If you are modeling a scenario where you might make discretionary payments depending on your cash flow, the schedule becomes a series of branching paths rather than a single timeline. You can handle this with data tables or by building a Monte Carlo simulation, but that quickly pushes the tool past the skill level of most users. For straightforward cases where you know your extra payment amounts, the spreadsheet method is reliable and accurate. For more complex forecasting, you need a different approach entirely, and I would suggest looking at a dedicated loan modeling tool rather than trying to force a spreadsheet to do something it was not designed for. One final detail that trips people up: once the final scheduled payment would leave a negative balance, the last payment needs to be adjusted downward to match the exact remaining principal plus accrued interest. Most templates ignore this and just show you a weird final row with a weird number. I always add a conditional that checks if the ending balance after the extra payment would be less than zero, and if so, it replaces the scheduled payment with a payoff amount that clears the balance to exactly zero. It is a small adjustment but it makes the schedule actually usable for verification purposes.
Get the Full Details