Understanding Amortization Schedules and How to Actually Use Them
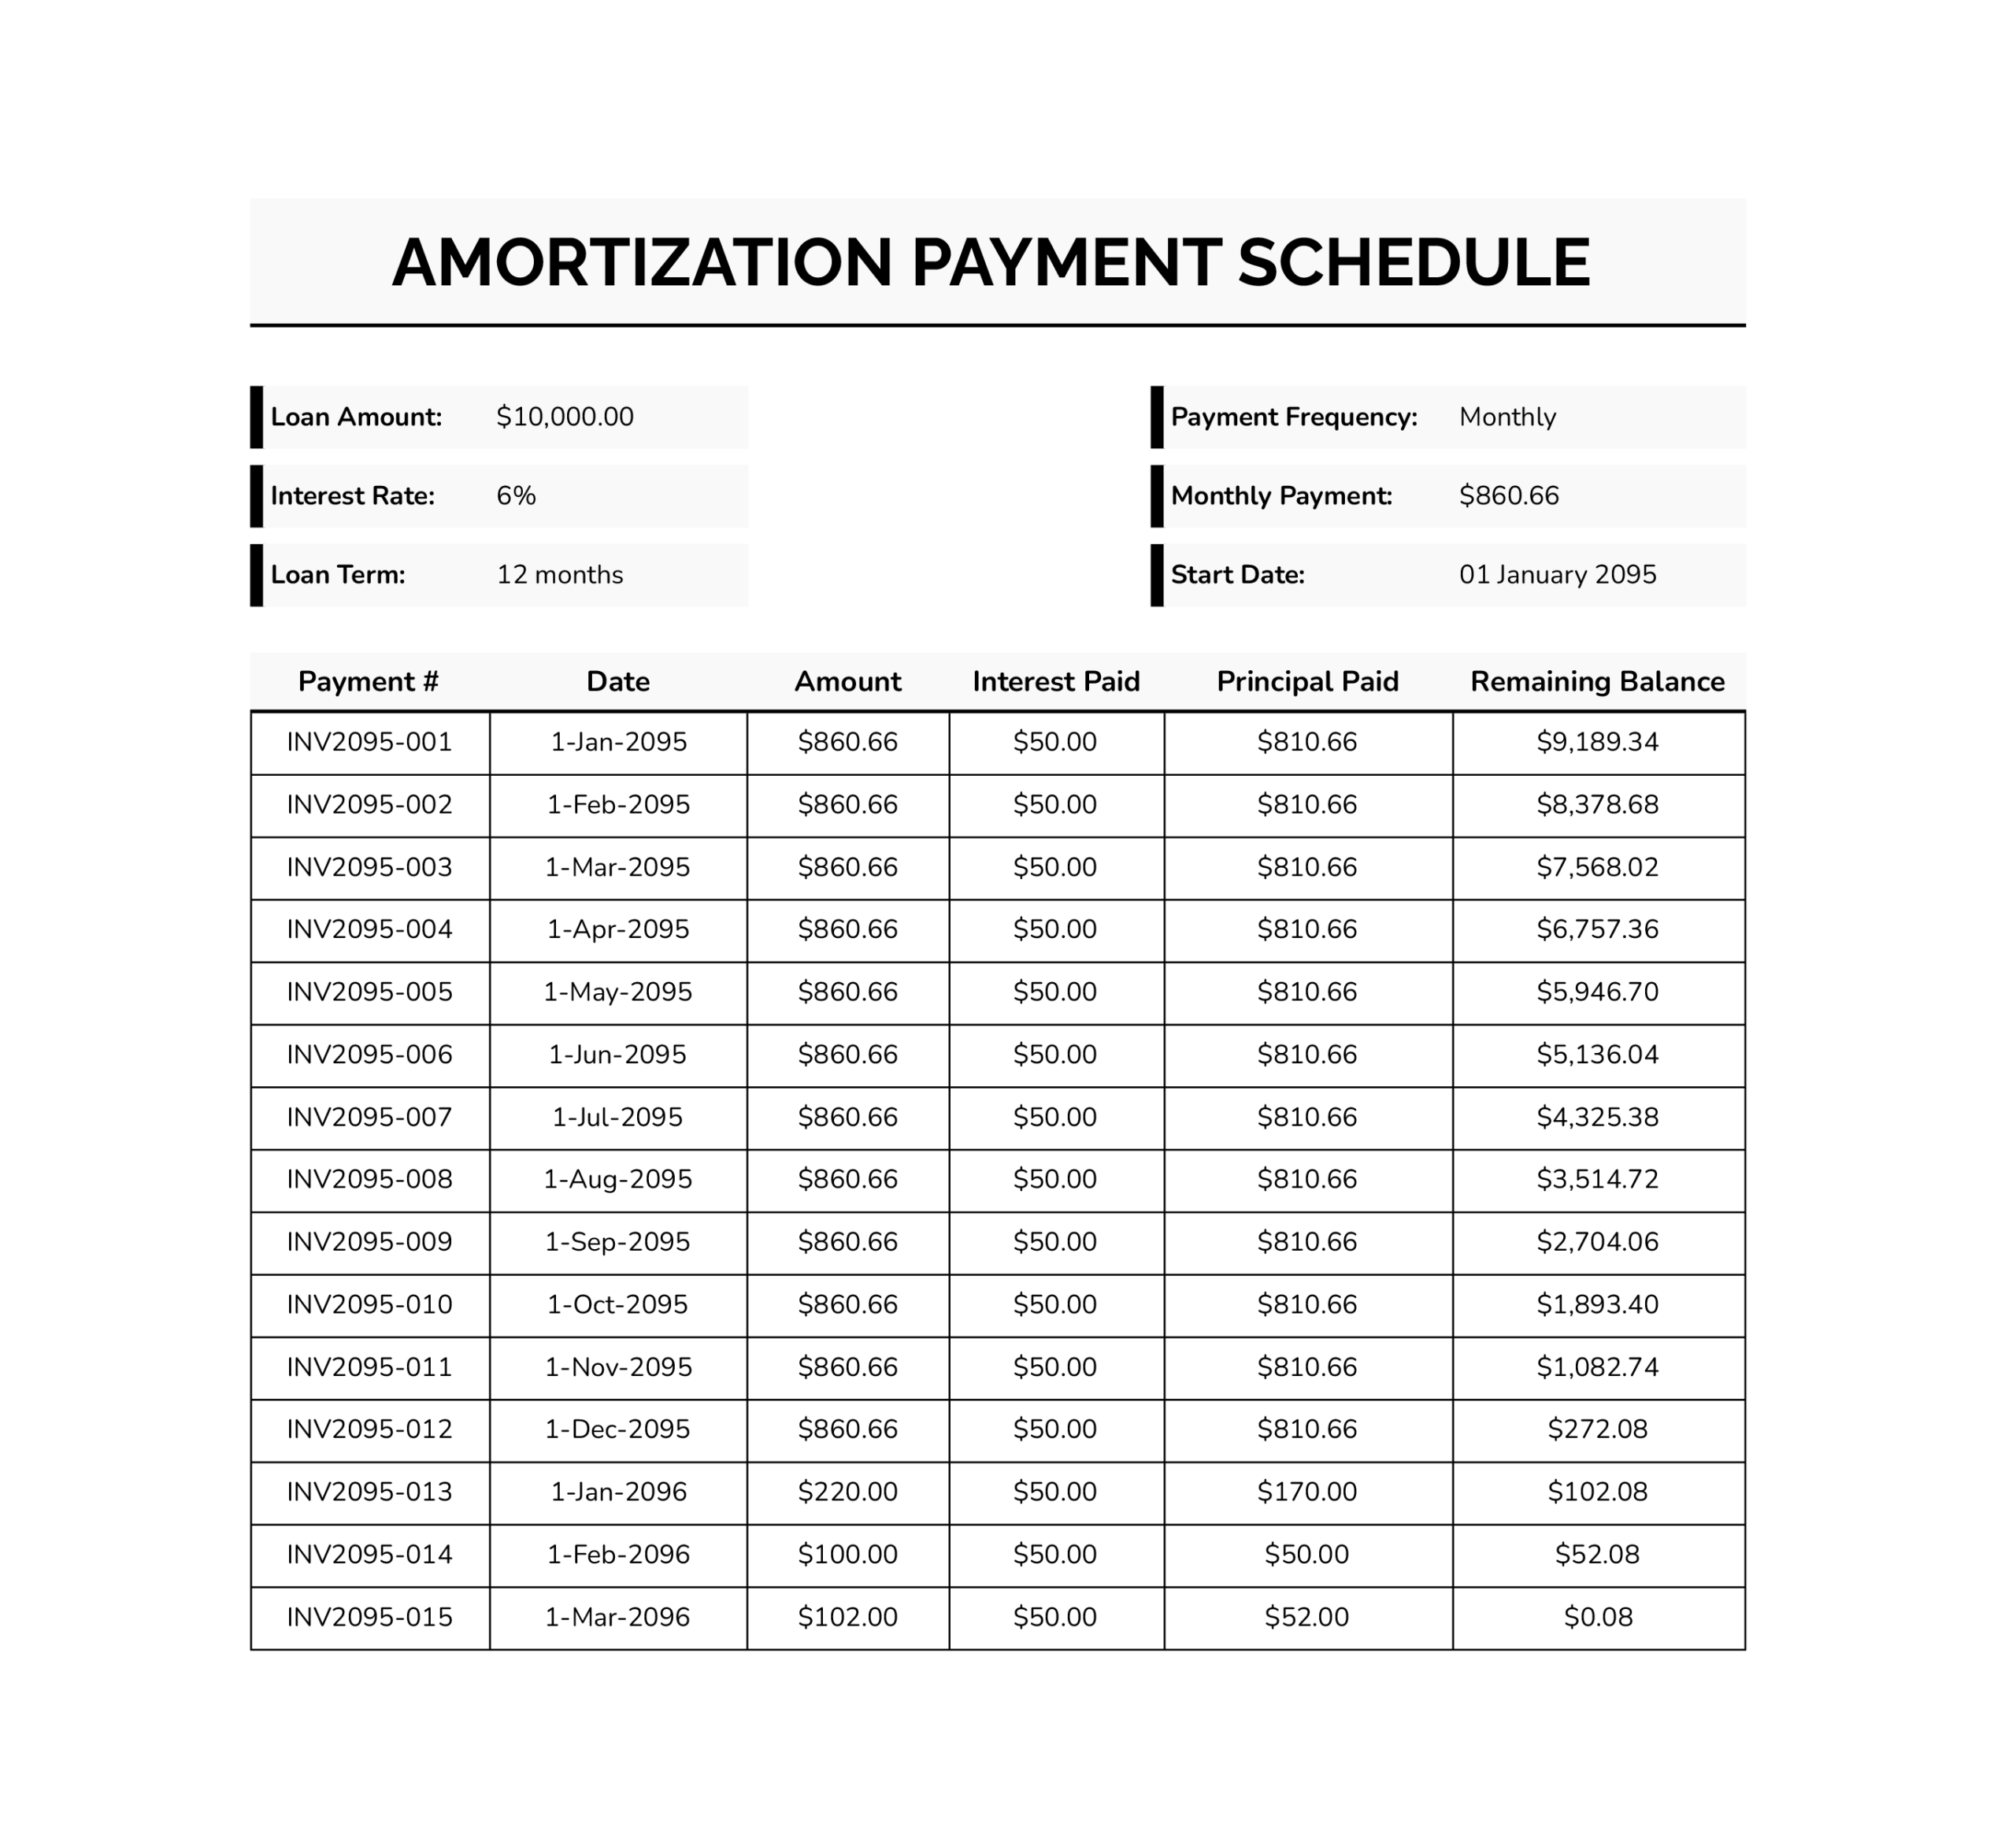
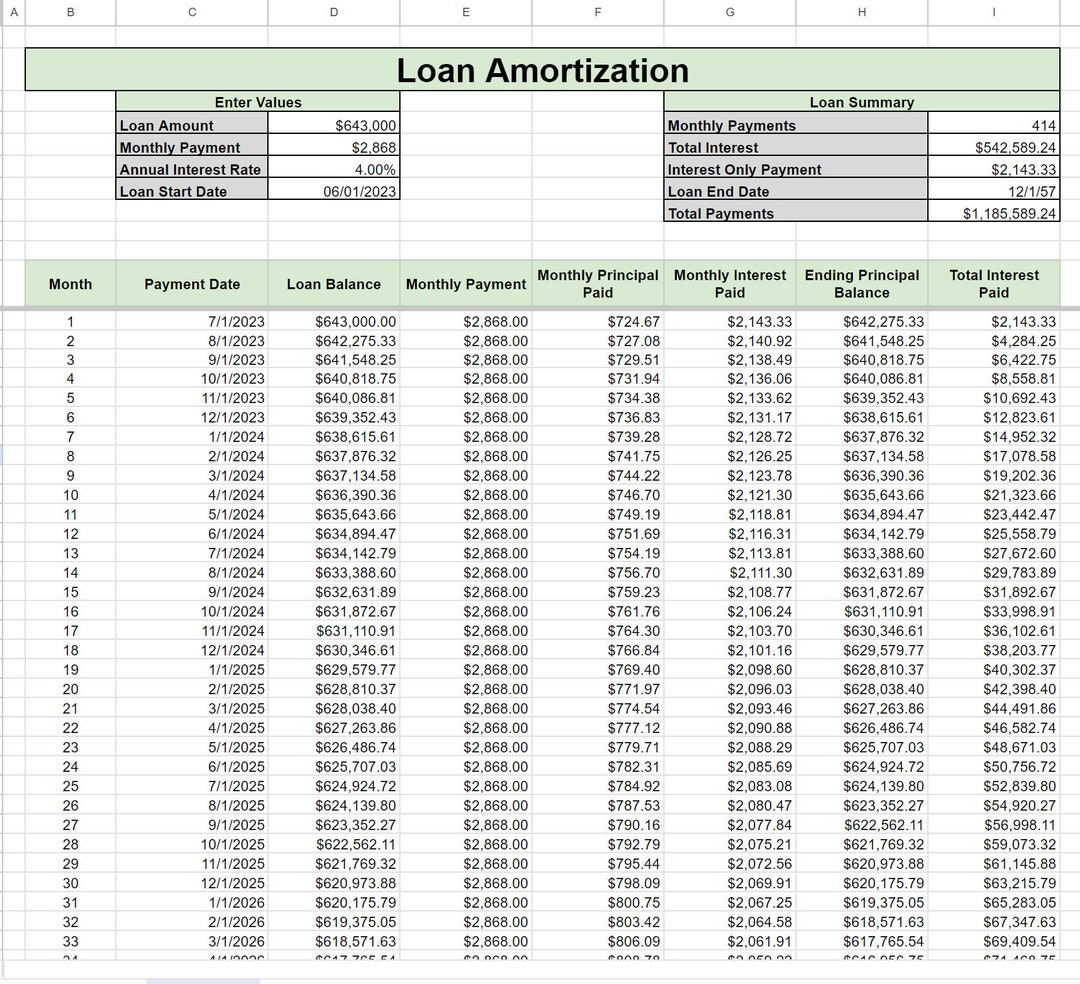
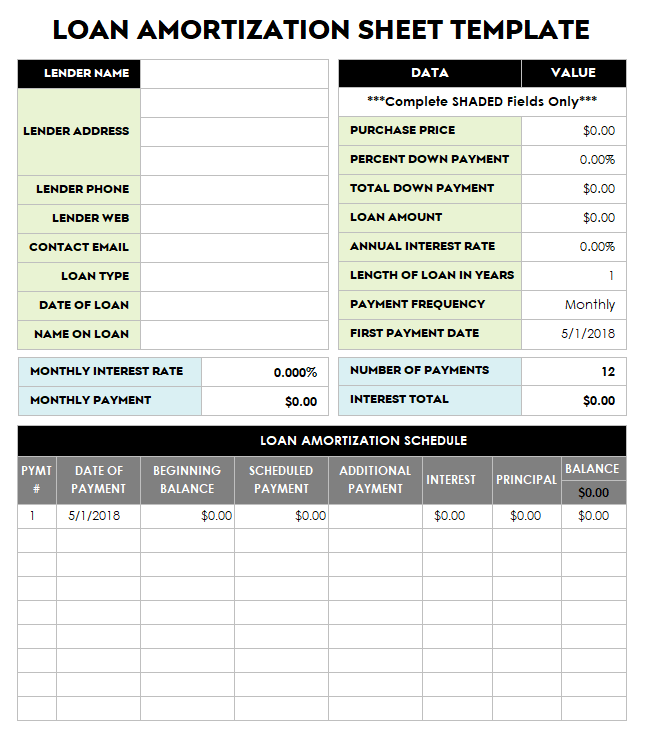
An amortization schedule is just a table showing how each payment on a loan splits between interest and principal over time. That's it. Most people downloading one just want to see their payoff date or figure out total interest paid. The reality is a bit messier than that spreadsheet you're about to pull up. There are two ways to get this. You can build it yourself in Excel or Google Sheets using PMT, IPMT, and PPMT functions, or you can use a dedicated amortization sheet download tool online. I've done both, and honestly, the online tools save about 20 minutes for a standard loan but fall apart quickly if your terms aren't conventional. Here's what most people miss when they download these: the output format matters more than the calculation itself. A poorly structured CSV from a free online generator will eat your afternoon when you try to import it into accounting software. Look for one that exports with consistent column headers like Payment Number, Beginning Balance, Payment Amount, Interest Portion, Principal Portion, and Ending Balance. I spent a Tuesday afternoon wrestling with a downloaded schedule that had rounding discrepancies accumulating to $47 over a 30-year term. The generator was using banker's rounding at each step instead of standard arithmetic rounding on the final payment. My workaround was simple: I took the last row, recalculated the remaining principal balance directly, and replaced the interest and principal values for that final entry. After that, the schedule balanced perfectly. Don't skip checking the ending balance against your loan payoff amount before you trust anything.
The Math Behind the Table
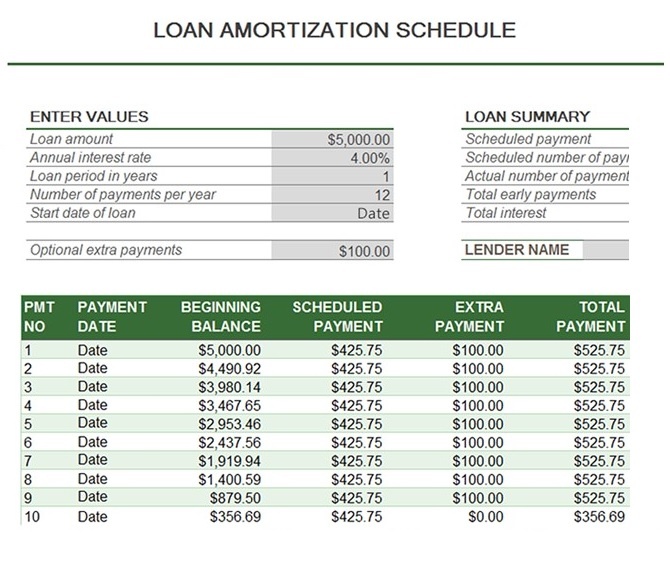
The monthly payment formula is M = P × [r(1+r)^n] / [(1+r)^n - 1], where P is principal, r is the monthly interest rate, and n is the total number of payments. It sounds intimidating but any decent calculator handles it in two seconds. What's more important is understanding what happens after you get the schedule, because the numbers it spits out don't tell the whole story. Here's something most amortization sheet download pages won't mention: the schedule assumes perfect, on-time payments every single month. In practice, that assumption breaks down the moment you make an extra principal payment, skip a month, or deal with a variable-rate loan. Most free generators don't have a recalculation feature that accounts for mid-loan changes. If you're planning to throw extra money at the principal, you need a schedule that lets you input prepayments, or you're looking at a significantly longer payoff timeline than the default output shows. I ran into this with a commercial real estate loan last year. The standard amortization sheet download gave me a clean 60-month schedule, but the loan had quarterly escrow adjustments I hadn't factored in. The interest calculations were off by about $120 per quarter once I included the escrow component. I ended up building a custom version in Sheets that pulled the base amortization and then added a separate column for escrow variations. It took me about 45 minutes to set up but saved me from relying on numbers that were technically correct for the loan but practically wrong for my actual cash flow picture.
What to Look For Before You Download
Not all amortization schedules are created equal. A good one includes a year-by-year summary column that totals your interest and principal payments annually. This is essential if you're filing taxes and need to report mortgage interest deductions or plan depreciation schedules for investment properties. Without annual summaries, you're looking at manually adding up 12 rows per year, which is tedious and error-prone for anything beyond a short-term loan. Another thing worth checking: does the tool let you input the loan start date? A lot of generators assume month-one starts on the first day of a generic month, but your actual payment date shifts the entire interest accrual curve slightly. On a $500,000 loan at 6.5% over 30 years, starting payments on the 15th instead of the 1st can shift your total interest by roughly $200 over the life of the loan. It's a small difference on a consumer mortgage but significant if you're running projections for a portfolio of properties. Also verify whether the schedule accounts for your compounding frequency. Some loans compound monthly, others daily. Daily compounding means your interest accrues slightly faster between payments, and a schedule built for monthly compounding will understate your actual interest cost. I once caught this on a construction loan where the amortization sheet download was based on monthly compounding but the note specified daily. The discrepancy was about $340 in interest over the first year alone. Not catastrophic, but enough to throw off your budgeting if you don't notice it early.
Get the Full Details
Common Mistakes People Make
The biggest one is treating the downloaded schedule as a binding commitment rather than a projection. Lenders use these for qualification purposes, but the actual statement you receive monthly might show different numbers due to how they handle partial periods, fee assessments, or escrow shortfalls. Always reconcile your downloaded schedule against your first two or three actual statements. If there's a consistent variance, the generator may be using a different day-count convention than your lender. A second mistake is ignoring the front-loading effect. In the early years of a standard amortization schedule, roughly 60 to 70 percent of each payment goes toward interest. People see this and panic, thinking they're not building equity fast enough. They're not. That's just how amortization works. The equity curve isn't linear; it's exponential. You'll notice the acceleration around year seven or eight when the principal portion finally overtakes the interest portion. If you need to understand when that crossover happens for your specific rate and term, a good amortization sheet download will show it in the early rows without you having to do the math yourself. Sometimes the tool itself is the problem. Free online generators vary wildly in quality. I've seen ones that cap out at 600 payments, which is fine for a 50-year loan but useless if you're looking at something longer. Others don't handle adjustable-rate mortgages at all and just flatten the rate across the entire term, which completely misrepresents your payment trajectory. If your loan has any unusual features like interest-only periods, balloon payments, or negative amortization, you're better off building the schedule manually or finding a tool specifically designed for complex loan structures.
When to Build vs. When to Download
If you're dealing with a standard fixed-rate mortgage or auto loan under 10 years, an amortization sheet download will get you where you need to go in about five minutes. For anything more complex, the time you save downloading is usually eaten back by the corrections you need to make. I keep a personal template in Google Sheets that handles prepayments, rate changes, and annual summaries out of the box. It takes me about ten minutes to populate with new loan data versus hunting through multiple online generators to find one that won't give me garbage output. The template approach also means you own the file. Downloaded schedules from free websites often come with watermarks, limited functionality, or terms that restrict commercial use. If you're using this for a business decision, that restriction can bite you later. A self-hosted spreadsheet doesn't have that problem, and you can add whatever columns you need without waiting for a tool update. One more thing: if you're comparing multiple loan options side by side, putting them all in the same spreadsheet makes the comparison immediately obvious. Downloaded schedules tend to live in separate files, which means manual cross-referencing. I've lost count of the number of times I compared interest totals from two different PDFs and realized I'd been looking at schedules with different start dates. Having everything in one sheet eliminates that risk entirely.