Building an Amortization Table in Excel That Actually Works
Most free amortization calculators you find online are garbage. They use rounded numbers that drift apart after month 24, they break when you switch to monthly compounding instead of annual, and half of them don't handle late payments or extra principal correctly. I spent about three hours last year debugging a client's spreadsheet where the interest calculation was off by $47 over a 30-year loan term because someone had used a simplified interest approximation instead of the standard amortization formula. Fixed it by rebuilding the schedule from scratch. The core problem with downloaded templates is that they're often built for a single use case. A standard fixed-rate mortgage table won't work for a home equity line of credit. An auto loan template assumes payments happen on the first of the month. If your actual payment date shifts even slightly, the interest accrual throws off the entire schedule.Amortization Table Excel Download
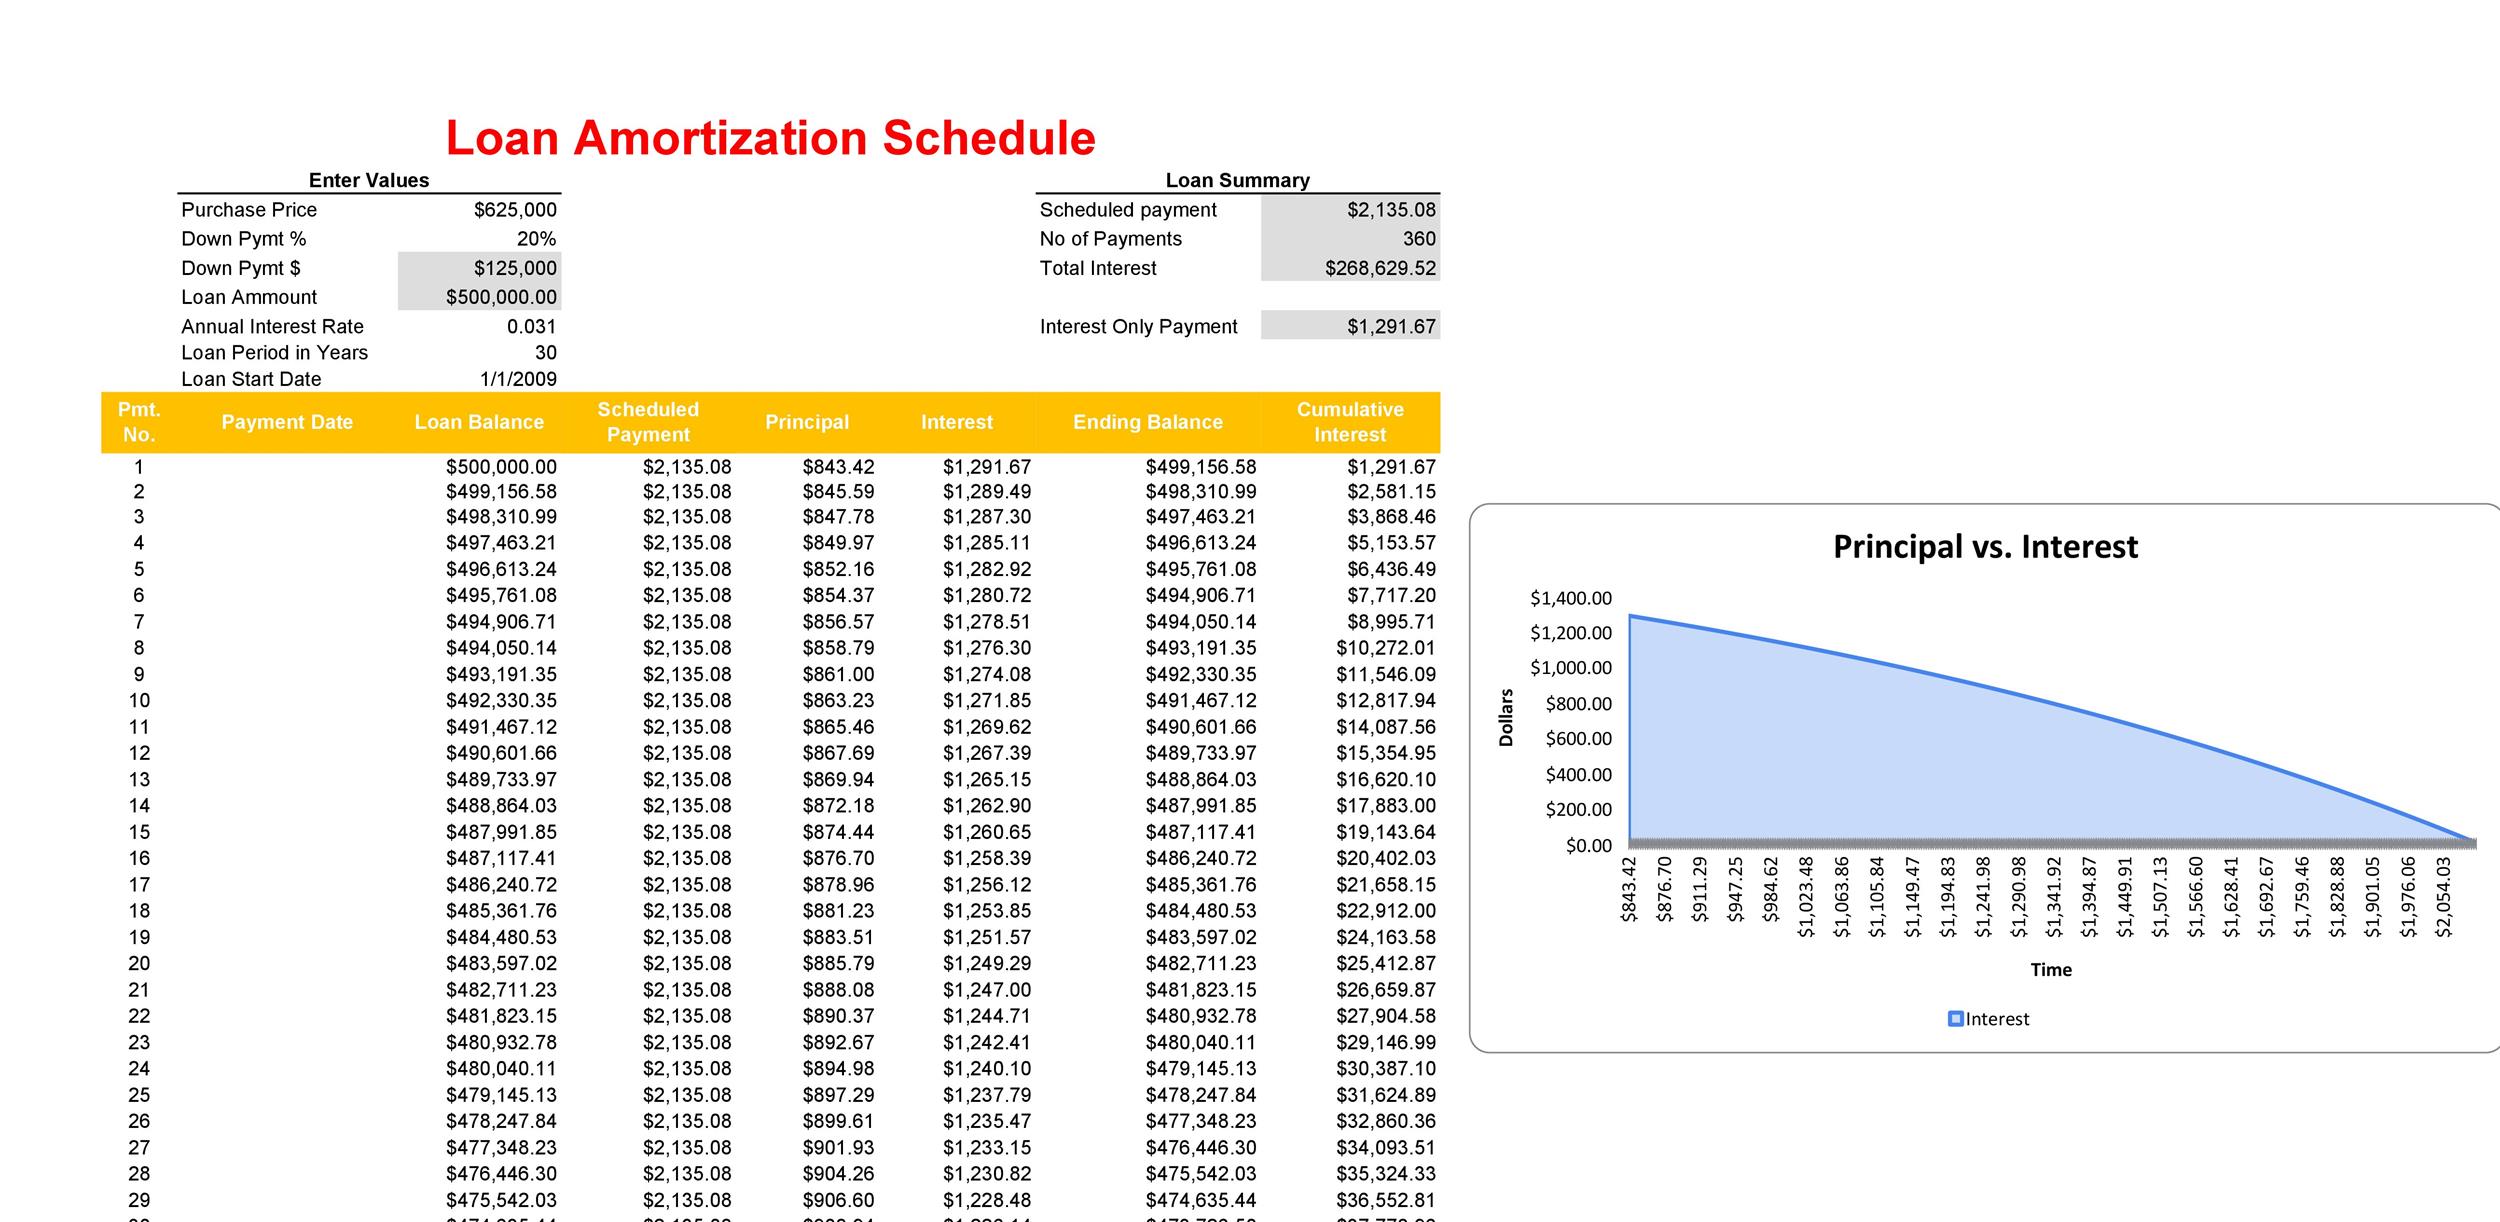
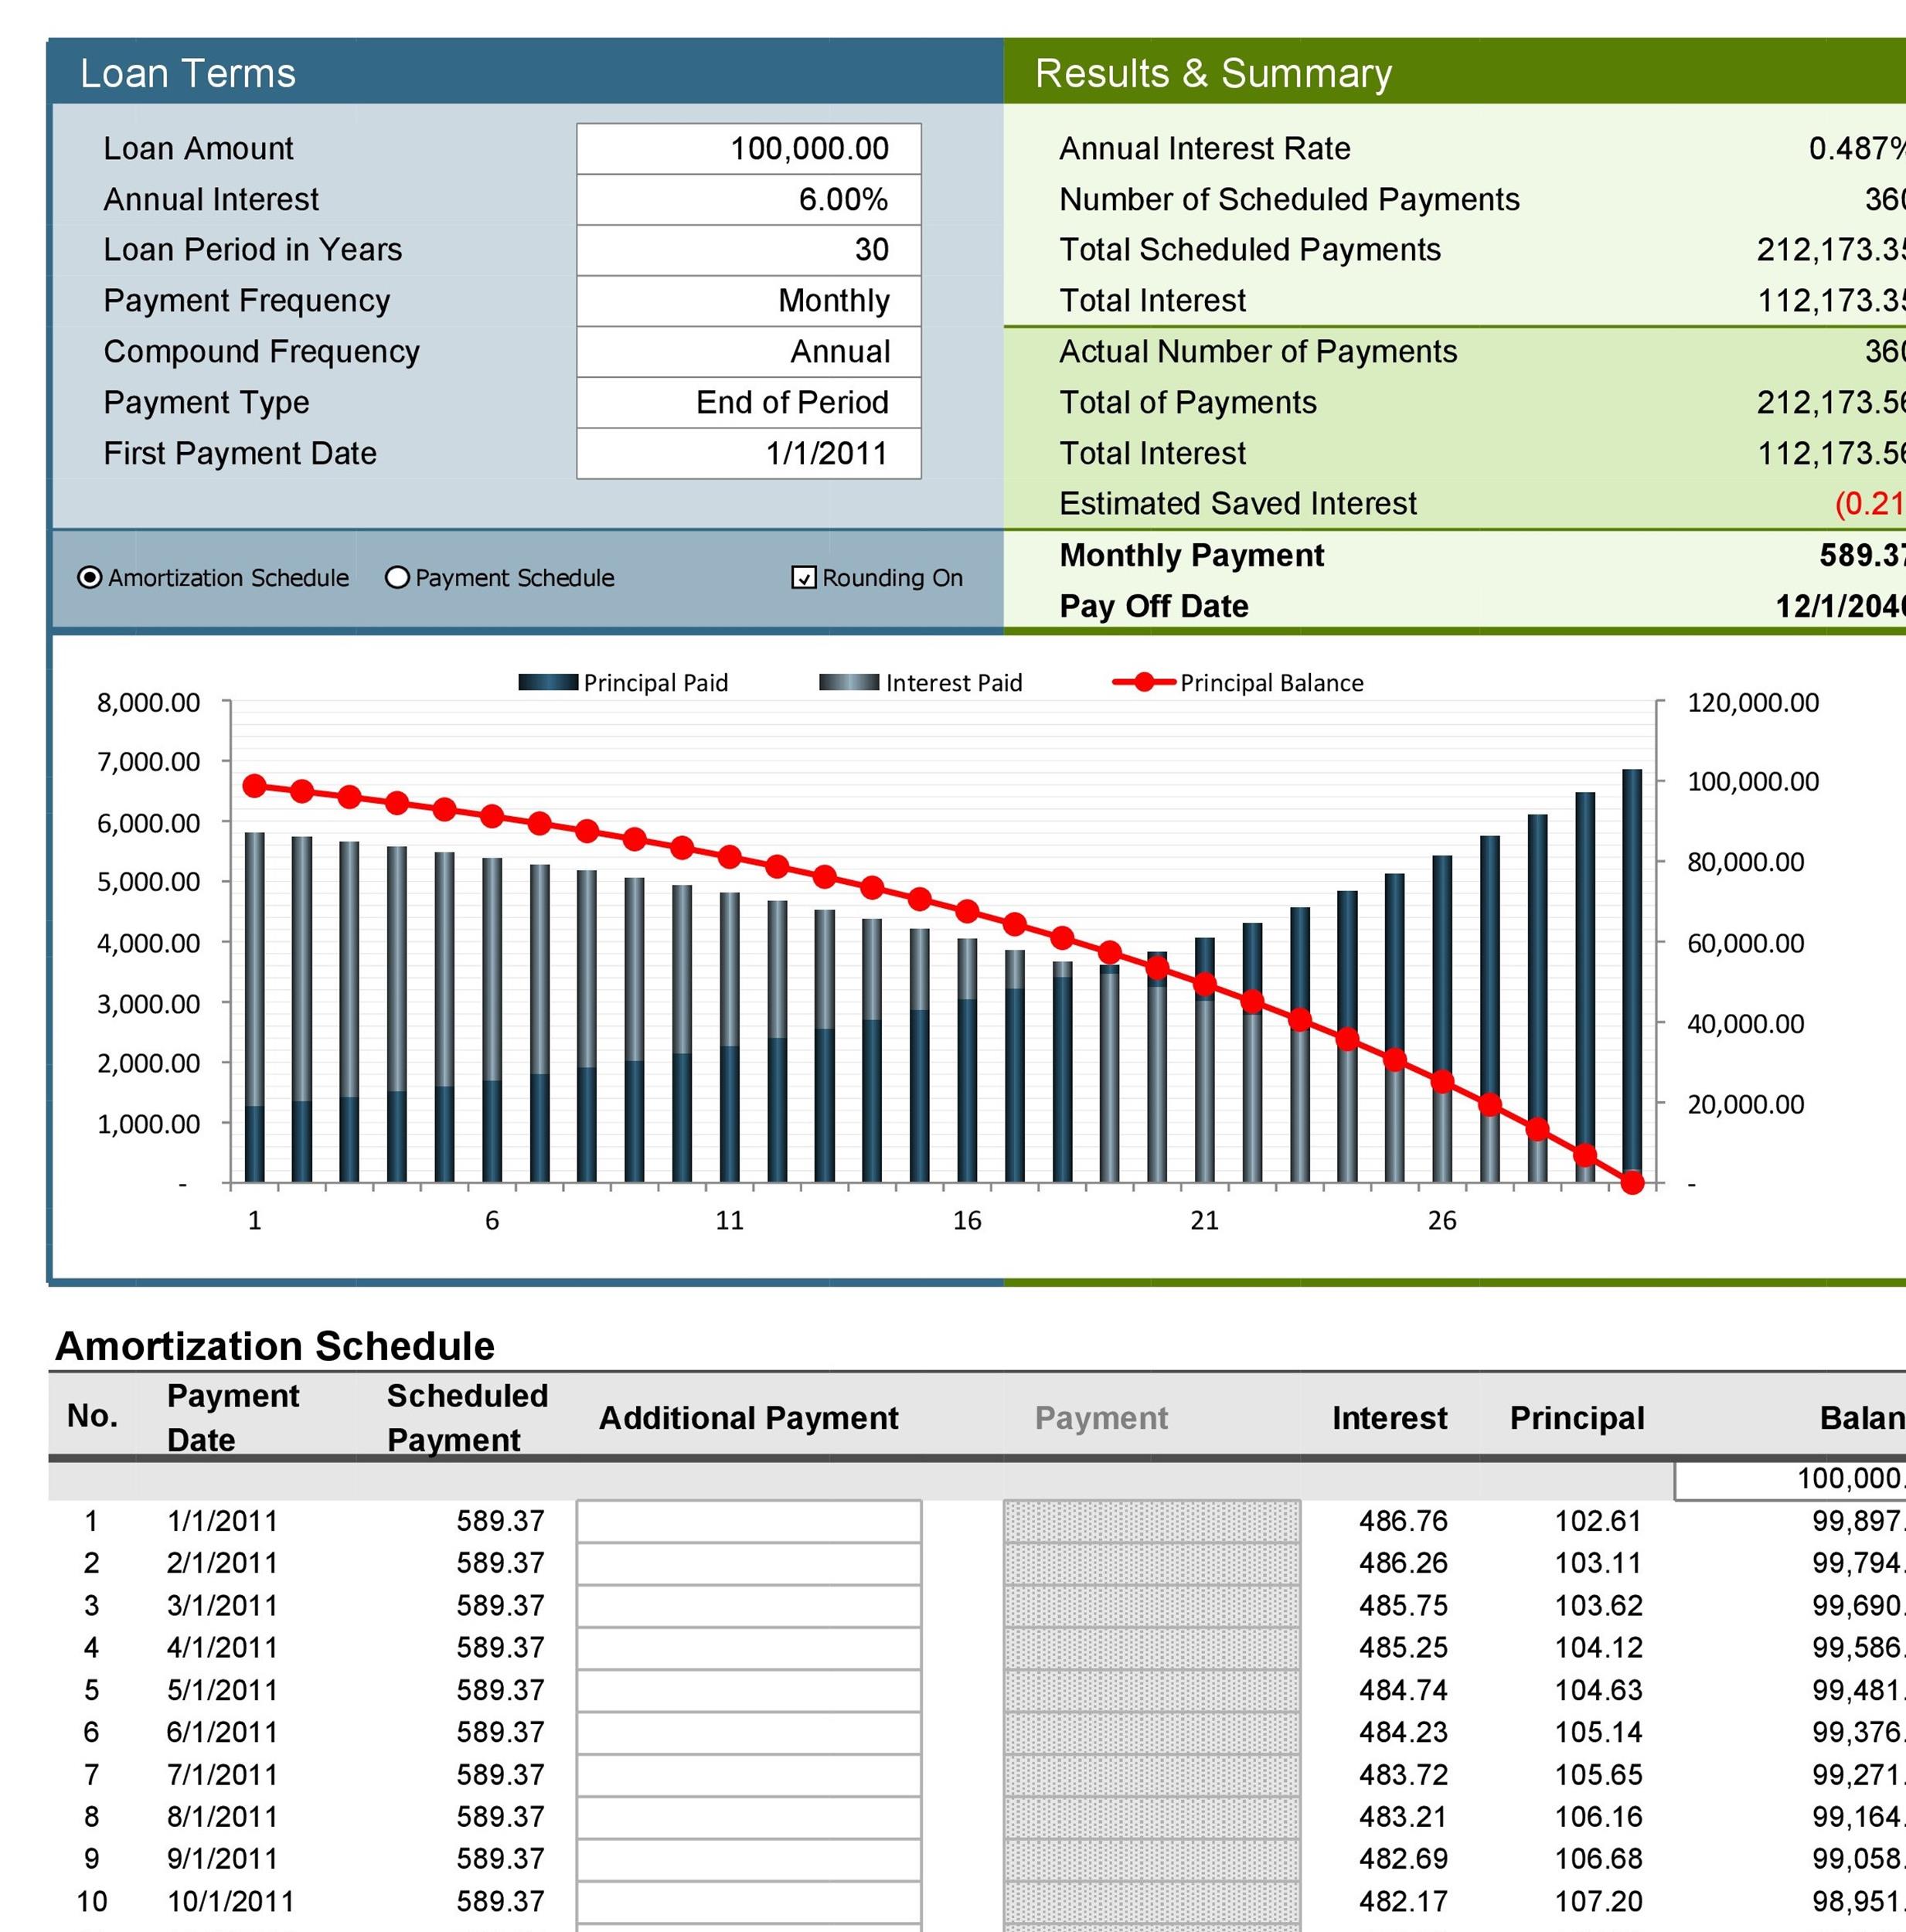
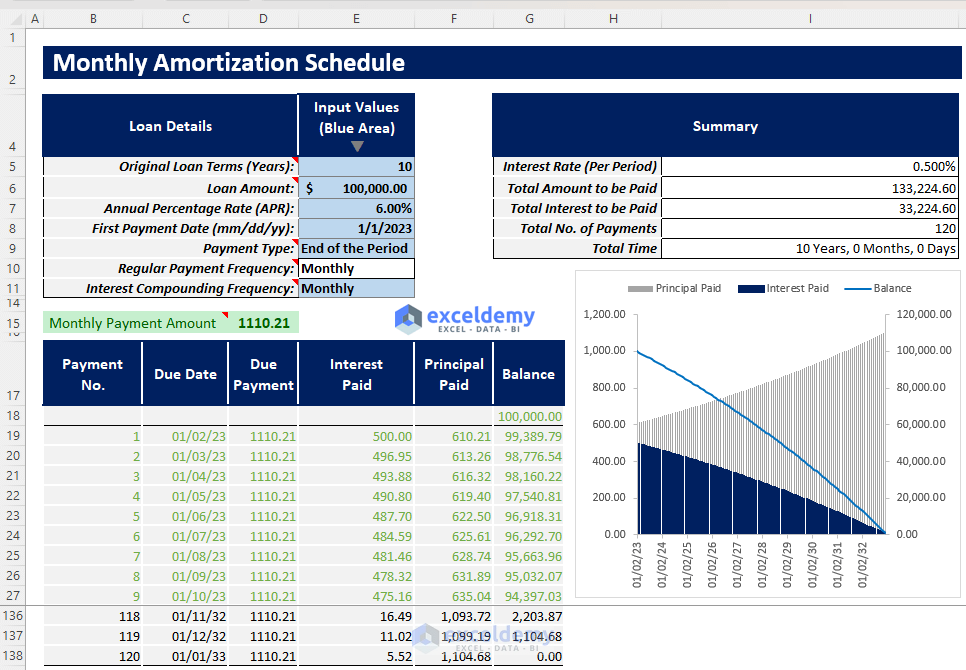
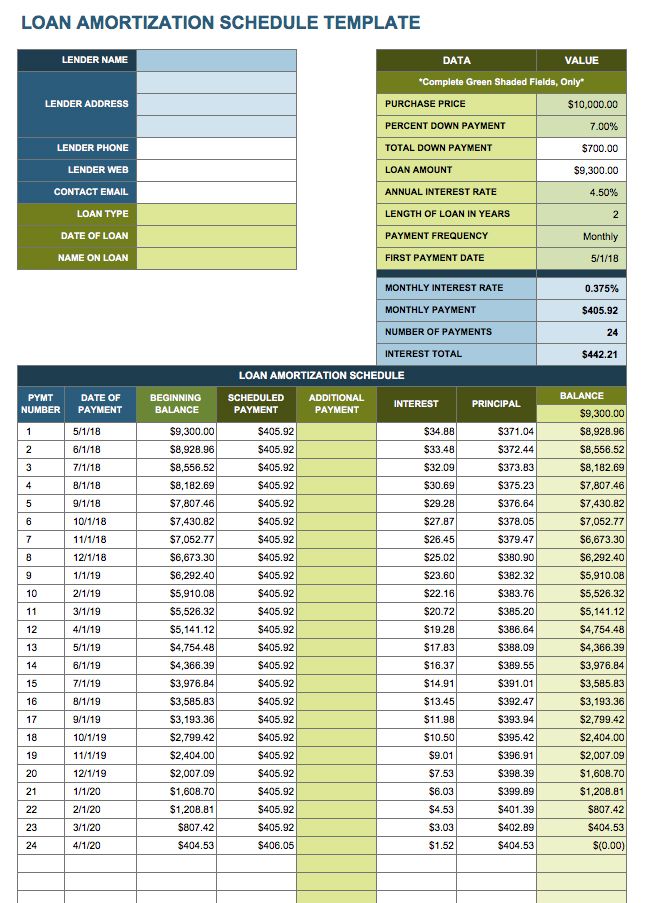
When you're looking for a reliable Amortization Table Excel Download, you need something that at minimum handles the PMT, IPMT, and PPMT functions correctly. These are Excel's built-in financial functions and they do exactly what you need. The PMT function calculates your payment amount given a rate, number of periods, and present value. IPMT gives you the interest portion of any specific payment. PPMT gives you the principal portion. Together they build the table. Here's how you actually set one up properly. Column A is the payment number. Column B is the payment date. Column C is the beginning balance. Column D is the payment amount using =PMT(rate/12, nper, -pv). Column E is the interest payment using =IPMT(rate/12, period, nper, -pv). Column F is the principal payment using =PPMT(rate/12, period, nper, -pv). Column G is the ending balance using =C-E. The rate should be your annual percentage rate divided by 12 for monthly payments. Nper is the total number of payments. Pv is your loan amount, entered as a negative so the payment comes out positive. This convention matters. If you enter pv as positive, your payment will be negative and everything downstream gets confusing fast. I ran into a situation where a client had an adjustable-rate mortgage and wanted the table to reflect rate changes at specific intervals. Standard templates don't handle this. You have to recalculate the payment at each adjustment point and then carry the new payment forward using the remaining balance as the new present value. The trick is splitting the table into sections, one per rate period, and linking the ending balance of section one to the present value of section two. It took me about twenty minutes to restructure their file, but once it was done it updated automatically whenever they changed the rate assumption.Common mistake: people forget to adjust the nper parameter when the rate changes. The remaining number of periods must decrease accordingly, or your final payment will be wrong.
There's a subtlety most people miss with the IPMT and PPMT functions. They assume payments are made at the end of each period by default. If your loan structure calls for payments at the beginning of the period, you need to add a third argument of 1 to each function. Without it, your first payment's interest calculation will be off by a full period's worth of accrual. That sounds minor but over 360 months it compounds into real dollar differences. Another thing nobody warns you about is floating point rounding. Excel handles the math fine, but if you're pulling these numbers into a report or sharing the table with an auditor, the tiny rounding discrepancies between calculated values and what appears on screen can look like errors. Always format your interest columns to two decimal places and consider adding a rounding column that feeds back into your balance calculation. Otherwise the ending balance might show as $0.03 instead of exactly zero. For a straightforward fixed-rate loan, this setup takes about five minutes to build and maybe ten to customize with your actual terms. A downloaded template might seem faster until you discover it can't handle your specific situation and you spend an hour trying to force it to work or replacing it entirely. Building it yourself means you understand every cell, you know where the assumptions live, and you can modify it without tearing it apart. One more note on Excel's PMT function specifically. It assumes a zero future value. If your loan has a balloon payment or any remaining balance at the end, you need to add that as the fv argument. A standard fully amortizing loan doesn't need this, but if you're modeling a bond or a loan with a final lump sum, omitting it will give you the wrong payment amount every time.