Building an Amortization Table from Scratch
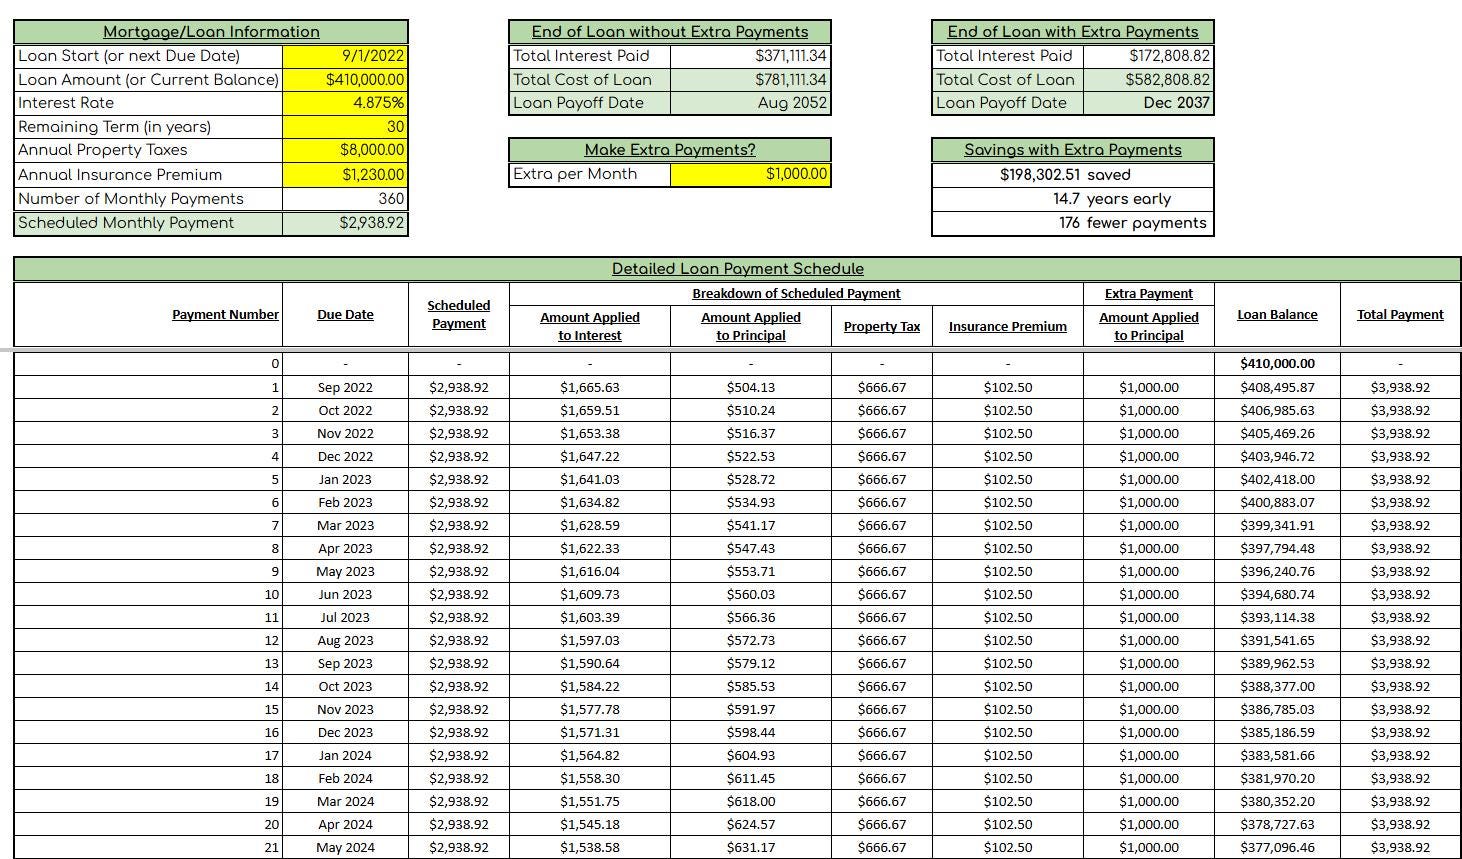
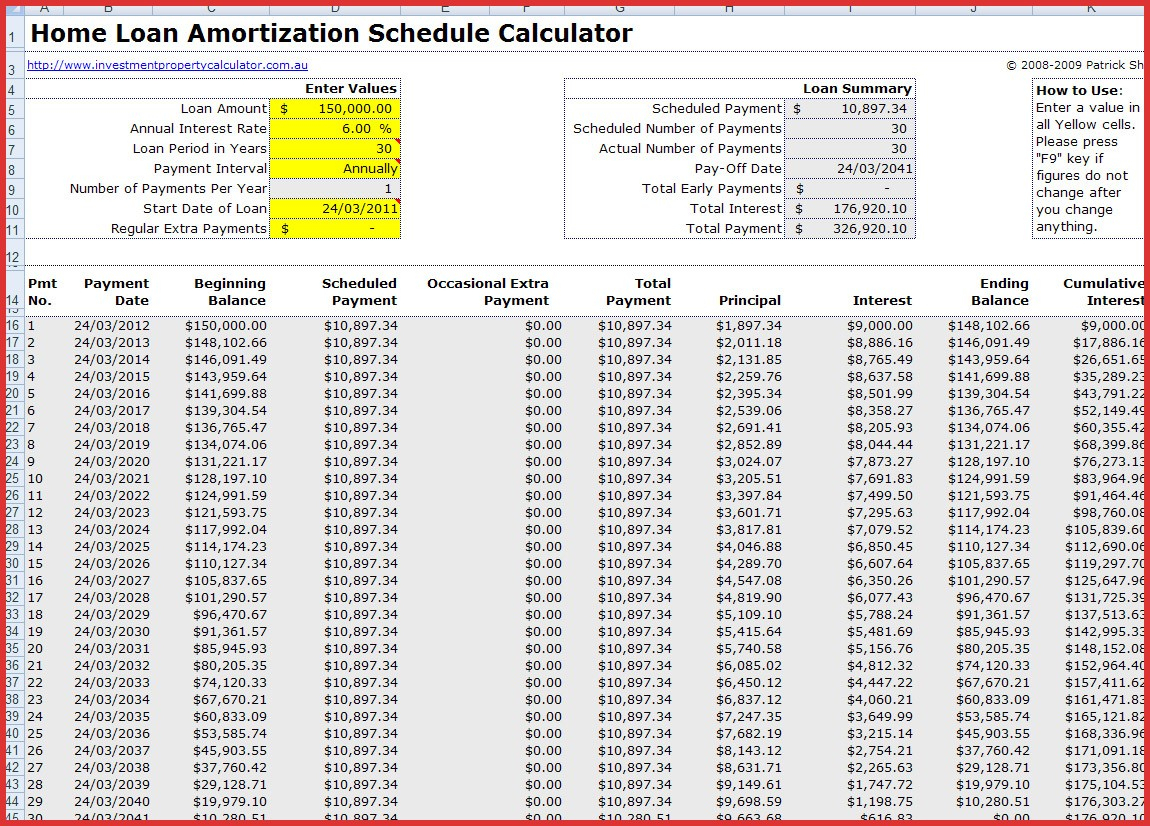
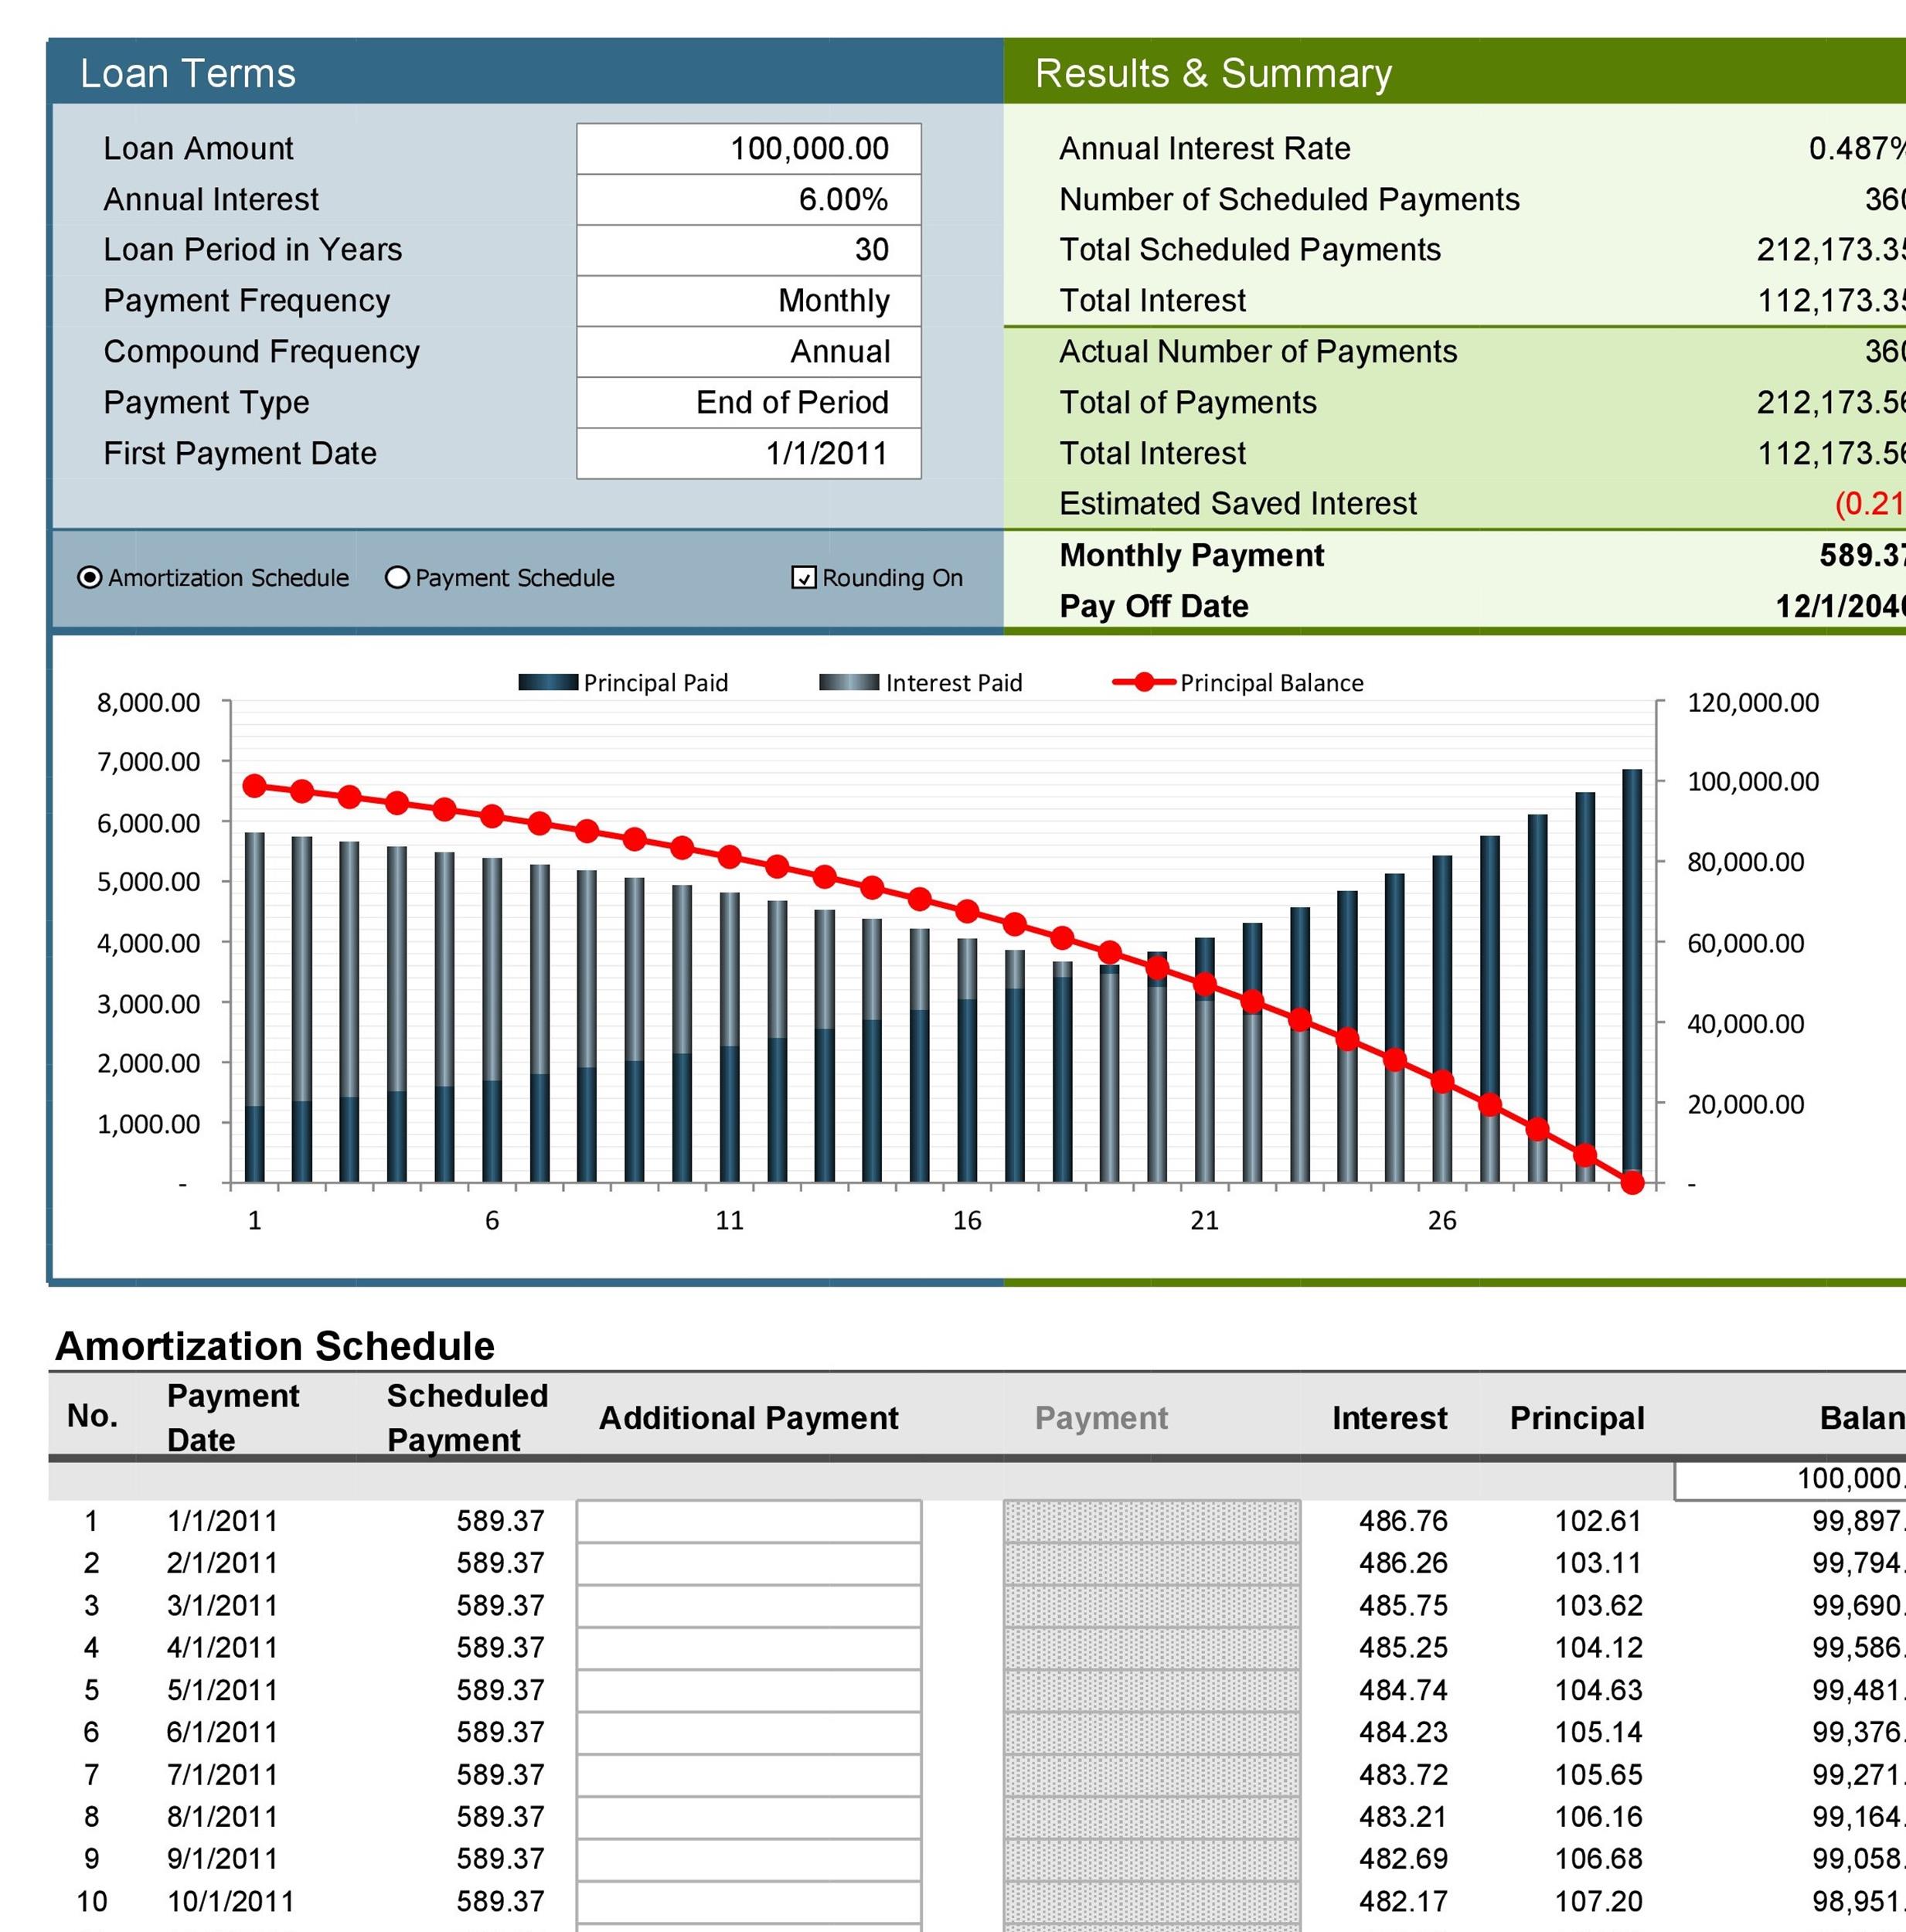
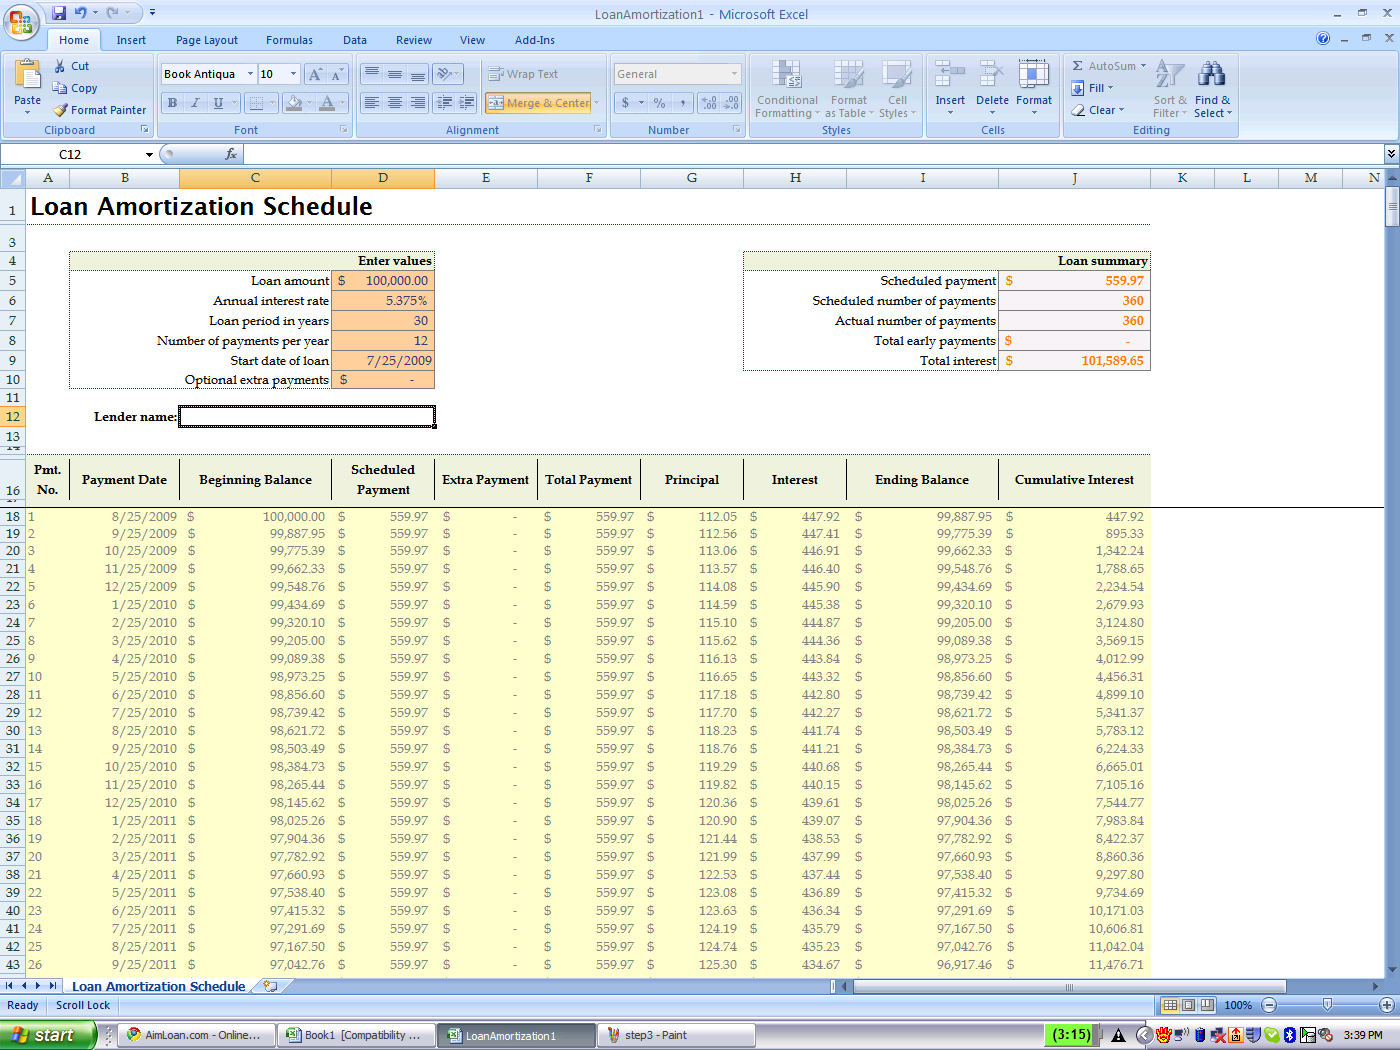
Most people don't need a fancy app for this. A spreadsheet with the right formulas will handle a standard loan schedule faster than any web tool. Here is how I set one up. Start with a clean sheet. In the top rows, list your inputs: principal amount, annual interest rate, and total number of payments. Label them clearly so you aren't guessing what each cell means six months later. The monthly payment formula is where most people go wrong. Use the PMT function, not a hardcoded calculator result. The syntax is =PMT(rate, nper, pv, [fv], [type]). Rate is your annual percentage divided by twelve. Nper is total months. PV is the principal, entered as a positive number. FV and type are optional for a standard loan. Set up columns for Payment Number, Date, Beginning Balance, Payment Amount, Principal Portion, Interest Portion, and Ending Balance. The first row's beginning balance is your principal. Each row's interest portion is =Beginning_Balance * Monthly_Rate. Principal portion is =Payment_Amount - Interest_Portion. Ending balance is =Beginning_Balance - Principal_Portion. The next row's beginning balance is simply the previous row's ending balance. Drag it down. I have seen spreadsheets that break around payment 47 when someone copies the absolute reference instead of keeping it relative. That creates a cascade where every balance after that point is wrong, and nobody notices until the borrower asks why their final payment is $0.12 off.
Common Pitfalls When Building an Amortization Table Spreadsheet
The most frustrating edge case I ran into involved a commercial loan with a balloon payment structure. The standard PMT function assumes equal payments throughout, which was fine for the interim months but completely ignored the balloon at the end. I spent about an hour rebuilding the bottom rows manually instead of dragging the formula across. The workaround was to calculate the regular payment using PMT, then in the final row override the ending balance to zero and adjust the principal portion to absorb the remaining balance. This ensures the schedule zeros out cleanly without manual adjustments later. Another issue that catches people off guard is floating point precision. Excel stores numbers to about 15 decimal places, which means rounding errors accumulate over hundreds of rows. Your final payment might come out as $1.47 instead of $1.46 because the tiny decimals keep shifting. The fix is simple. Round the interest portion to two decimals each row, and let the final payment absorb the difference. I usually add a note in the last row that says "Final payment adjusted for rounding." This way auditors don't flag it. Sometimes a simple Amortization Table Spreadsheet isn't the right tool. If you are dealing with variable-rate loans, early paydowns, or irregular payment schedules, the straight PMT approach falls apart quickly. In those cases, I switch to a more flexible setup where the payment amount is user-input each period rather than formula-driven. It takes longer to build but handles real-world complexity without breaking.
The spreadsheet version of an amortization schedule gives you full control over formatting, validation, and integration with other models. Online calculators look cleaner but they lock you into their assumptions. Once you have the template built, copying it for a new loan takes maybe five minutes.
Get the Full Details