How balloon payments actually work in practice
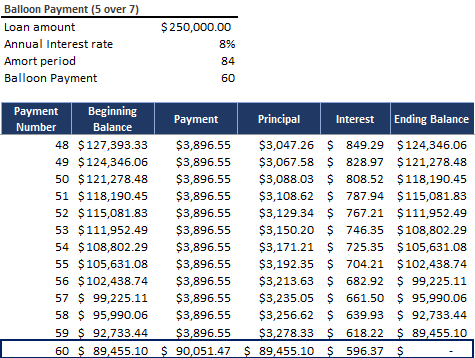
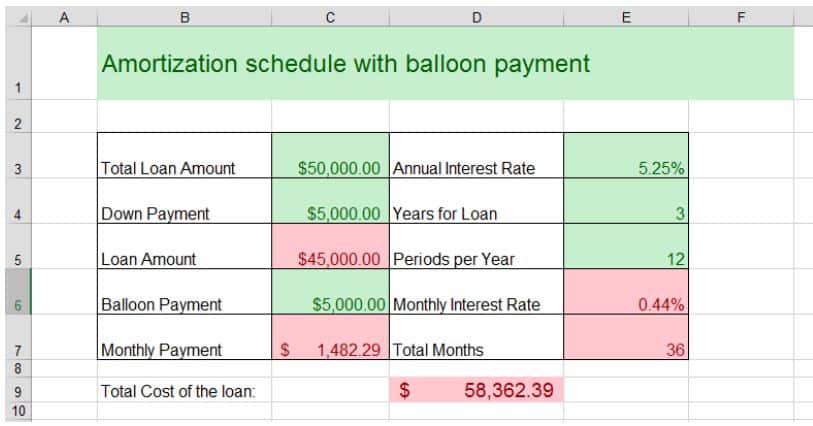
A balloon payment is just a large lump sum due at the end of a loan term. The monthly payments are calculated as if the loan will be fully paid off over the schedule, but the final payment is much larger than the others because most of the principal was never amortized. That's the whole mechanism. Everything else is just implementation detail. The standard spreadsheet approach uses a fixed number of periods, like 60 months, to calculate the monthly payment. Then you subtract each payment from the remaining balance until month 60, where instead of a normal payment the balance gets paid down to the pre-set balloon amount. The monthly payment itself stays the same throughout. People often get confused here and think the payment changes near the end. It doesn't. Only the final row looks different. Here is how I set this up. Start with a principal amount, an annual interest rate, and a balloon payment amount. Calculate the monthly rate by dividing the annual rate by 12. Then use the standard annuity formula to find the payment, treating the balloon as a future value that must remain at the end. In Excel or Google Sheets that formula looks like:
=PMT(rate, nper, -pv, -balloon) Where rate is the monthly rate, nper is the total number of periods, pv is the present value (the loan amount), and balloon is the future value you want left at the end. The minus signs are there because Excel treats cash inflows and outflows as opposite directions. If you get a negative payment back, flip the signs. This took me about three minutes to get right after the first time. Once you have the payment, build the table row by row. For each period, calculate the interest portion as the previous balance times the monthly rate. Subtract that interest from the payment to get the principal reduction. Subtract the principal reduction from the balance to get the new balance. On the final row, replace the normal payment with the balloon amount and adjust the interest and principal columns accordingly. The balance should hit zero or your target number exactly.
What most people miss about these calculations
The biggest practical issue is rounding. If you round each monthly interest calculation to two decimal places, your final balance might be off by a few cents. I had a case once where a commercial loan with a 500000 dollar principal and a 100000 dollar balloon at 7.5% for 36 months ended with a balance of 100000.03 instead of 100000. Exactly three cents. That sounds trivial until your auditor asks you to explain it. The workaround is simple: in the final row, force the balance to equal exactly the balloon amount and back-calculate the principal and interest from there. Never let the math drift into the last row. Adjust the last payment slightly if needed, or adjust the principal column so everything reconciles cleanly. Another thing people overlook is the difference between a fully amortizing schedule and a partially amortizing one. A balloon loan is by definition partially amortizing. The payment you calculate does not reduce the balance to zero over the stated term. It reduces it only to the balloon amount. Some lenders try to present this as a standard loan and bury the balloon in the fine print. If someone sends you a monthly payment figure without specifying the balloon, verify the remaining balance after the last scheduled payment. If it is not zero, you are dealing with a balloon structure.
Get the Full Details
The edge case nobody talks about
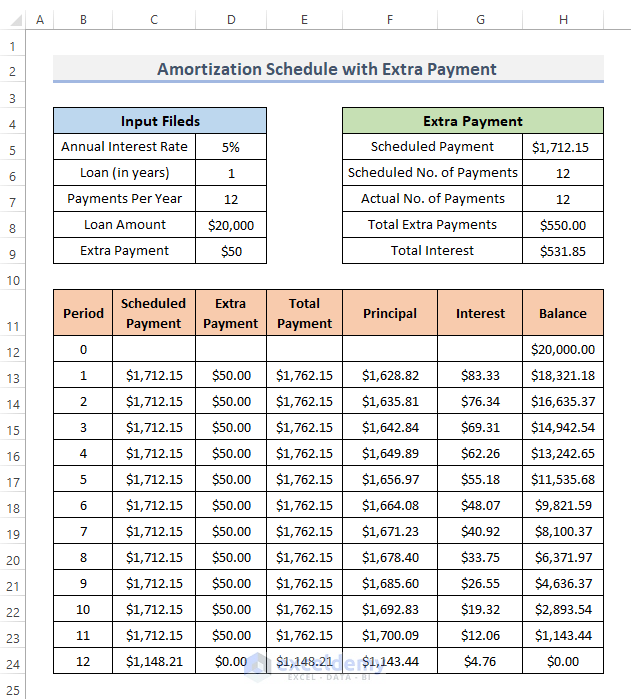
I worked on a project where the borrower wanted to make a partial prepayment mid-term, say in month 18, and still have the balloon at the end. Most amortization calculators just keep the payment the same and adjust the balance, which throws off the balloon because the balloon was calculated based on the original amortization path. The correct approach is to recalculate the remaining monthly payment from month 19 onward, using the new remaining balance and the original balloon amount as the future value. In formula terms, you take the updated balance at month 18 and solve PMT with the new remaining nper and the same balloon figure. This keeps the payment realistic and the balloon intact. If you are building a tool for this, you need to handle the recalculation path explicitly. Do not assume the balloon is static after the initial setup. Prepayments change everything about the schedule.
Limitations you need to know about
An amortization table with a balloon payment has real limitations. First, it assumes a fixed rate throughout the entire term. If the loan has an adjustable rate or an interest-only period followed by amortization, the table structure changes significantly and you need separate phases with different calculation rules. Second, the balloon amount itself creates refinancing risk. A borrower might qualify for the monthly payment but not have the liquidity to cover the balloon when it comes due. The table shows the numbers correctly but says nothing about whether the borrower can actually execute the balloon payment. Third, some jurisdictions require specific disclosures for balloon loans that a standard amortization table does not address. If you are building this for a lending platform, regulatory compliance is a separate layer you cannot skip. For adjustable-rate scenarios, a better approach is a phased table with separate PMT calculations for each rate period. The output is less elegant but more accurate. I used a hybrid method where the table had distinct sections for the fixed period and the balloon period, with a clear separator row. It added about 20 percent development time but eliminated the confusion that came from trying to force everything into one section.
Where to find or get the template
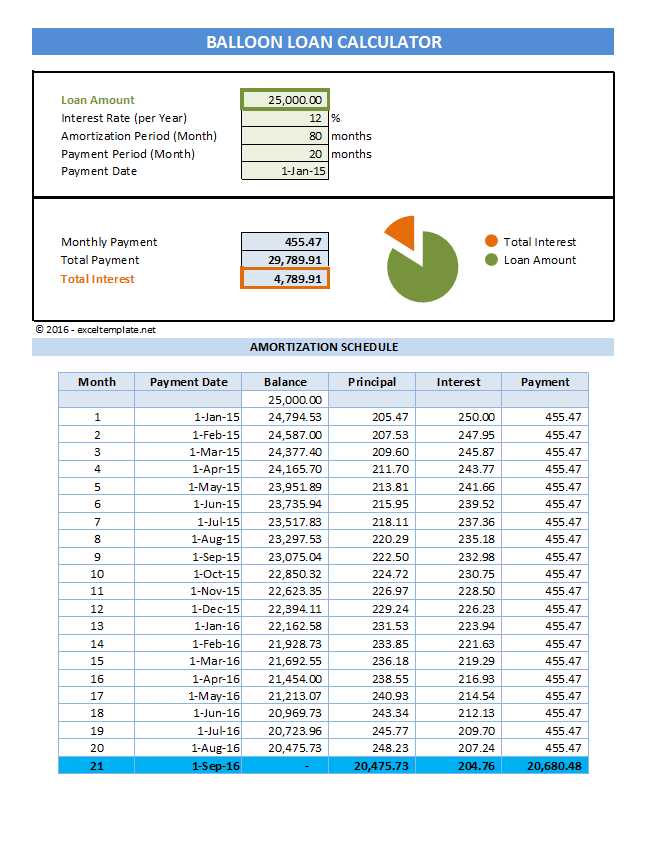
There is no single official source for a balloon amortization template because the structure varies so much by use case. The core logic fits in a single spreadsheet. I typically distribute mine as a Google Sheets file with input cells in blue, calculated cells in white, and a warning row in yellow that flags any balance variance greater than one cent. You can build the same thing from scratch in about 15 minutes. Copy the PMT formula, set up a column for period number, a column for payment, a column for interest, a column for principal, and a column for remaining balance. Link each row to the previous one. Add the balloon adjustment in the final row and you are done. If you want a downloadable version, I maintain a shared Sheets link in my public resources. It includes the partial prepayment recalculation logic and the rounding correction automatically applied. No macros, no external dependencies, just formulas. That matters because macros break when people copy the file to their own sheets.

When this method breaks down completely
Do not use a standard balloon amortization table for loans with grace periods, deferred interest, or capitalization of interest during the early term. The math diverges sharply from what the PMT function assumes. In those cases, you need a custom iteration or a Goal Seek approach to find the correct payment. I encountered a bridge loan where interest was capitalized for the first six months and the borrower made no payments. Running a standard PMT on that structure gave a payment that was off by nearly eight percent because the principal base was wrong from the start. The fix was to accumulate the capitalized interest into the principal balance before starting the amortization schedule, then calculate PMT on the adjusted principal. Always verify the principal balance at the start of the payment phase before plugging anything into PMT. A balloon amortization table is a straightforward tool for a straightforward loan structure. It becomes unreliable the moment the loan terms introduce variable rates, prepayments, or deferred interest without explicit handling. Know where the boundary is and stay on the right side of it.