When you are looking at loan structures, amortization with balloon payment is one of those terms that comes up frequently in commercial lending and certain consumer financing scenarios. I have dealt with enough of these loans across different industries to give you a straightforward breakdown of how they actually work and what to watch out for.
The basic setup is simpler than most people expect. You take out a loan where the monthly payments are calculated as if you will be paying it off over a long period, maybe fifteen or twenty years. But instead of actually making payments for that full term, there is a large lump sum due at the end, typically after five to seven years. That final payment is the balloon, and it is usually the majority of the original principal.
How Amortization With Balloon Payment Actually Works
Let me walk through a concrete example because the numbers reveal the mechanics faster than any definition will. Say you borrow two hundred thousand dollars on a seven-year balloon loan with a thirty-year amortization schedule at six percent interest. Your monthly payment gets calculated based on that thirty-year timeline, which works out to roughly one thousand one dollars per month.
Over those seven years, you make eighty-four payments of one thousand one dollars. A significant portion of each payment goes toward interest in the early years because that is how amortization works regardless of the balloon structure. By the end of year seven, you have paid down maybe twenty-five to thirty thousand dollars of principal, but not much more. The remaining one hundred seventy thousand dollars or so becomes due all at once.
I encountered a specific issue with this during a commercial property transaction a couple years back. The borrower had been making perfect payments for six years on their balloon loan, expecting to refinance before the due date. The problem was that the amortization schedule showed they had only reduced the principal by eighteen percent, not the twenty-five percent they assumed. They were short by about forty thousand dollars when the balloon came due, which forced them into a rushed refinance at less favorable terms.
The workaround I used was straightforward but often overlooked by borrowers. I had them pull a payoff statement from the lender three months before the balloon date. This revealed the exact remaining balance, including any prepayment penalties or fees that might apply. Most standard amortization calculators do not show these details, so the borrower was never prepared for the true cost of exiting the loan early.
There are some counter-intuitive aspects to this structure that beginners consistently miss. First, the interest savings from the shorter term are minimal compared to what most people assume. Even though you are only holding the loan for seven years instead of thirty, the monthly payment calculation means you are paying interest on the full balance for those seven years regardless. The total interest paid over the life of the balloon period is actually quite similar to what you would pay on a standard fifteen-year loan, just with a large principal balance still outstanding.
Second, the tax implications can be confusing. In many jurisdictions, the interest deduction on the monthly payments is available throughout the loan term, but when you pay off the balloon, you might lose certain deductions depending on how the loan was structured and what the funds were used for. I have seen borrowers treat the balloon payment as a simple refinancing event without realizing they might trigger recapture provisions or lose depreciation benefits tied to the original loan structure.
When This Structure Makes Sense and When It Does Not
Balloon payments work best when you have a clear exit strategy. The classic example is a commercial real estate investor who knows they will sell the property within five to seven years, either through appreciation or value-add improvements that increase the rental income. The lower monthly payments during the hold period preserve cash flow for renovations or other investments, and the sale or refinancing at the end covers the balloon.
I would not recommend this structure if you are relying on steady income to cover the balloon payment without a guaranteed source. The risk of not being able to refinance or sell when the balloon comes due is real, and the consequences can be severe. You might face foreclosure, a rushed sale at below-market prices, or a refinancing option with terms that leave you worse off than when you started.
The main downside that everyone underestimates is the refinancing risk. Lending standards change, property values fluctuate, and your personal financial situation might not look as strong in five years as it does today. I have seen perfectly creditworthy borrowers lose their refinancing options because the property did not appraise at the expected value or because the lender changed their debt-to-income ratio requirements.
Another practical concern is the impact on your credit utilization and debt-to-income ratios during the balloon period. Even though the monthly payment appears reasonable based on the long amortization, the looming balloon payment should be factored into any future borrowing decisions. Some lenders do consider the balloon as a contingent liability, which can affect your ability to qualify for additional financing when you need it most.
Calculating Your Actual Cost and Risk
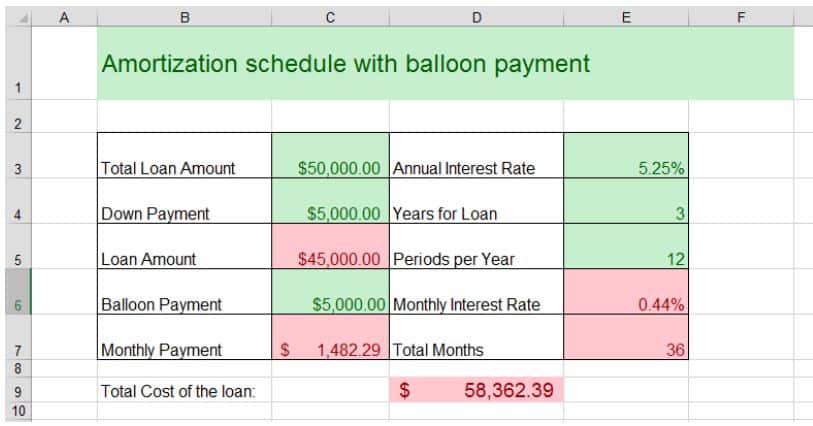
To properly evaluate this structure, you need to look beyond the monthly payment and calculate the total cost including the balloon. Take the monthly payment amount, multiply it by the number of payments in the balloon period, then add the balloon payment itself. This gives you the total cash outflow over the life of the loan.
Compare this to alternative financing options. A standard fifteen-year loan will have higher monthly payments but will eliminate the balloon risk entirely. A five-year home equity line of credit might offer more flexibility but comes with variable rate risk. The right choice depends on your specific situation, cash flow projections, and how confident you are in your exit strategy.
I always recommend running sensitivity analysis on your refinancing assumption. What happens if the property value drops ten percent? What if interest rates rise by two points? What if your income changes? These scenarios matter more than the base case numbers because they determine whether the balloon structure helps you or hurts you when conditions change.
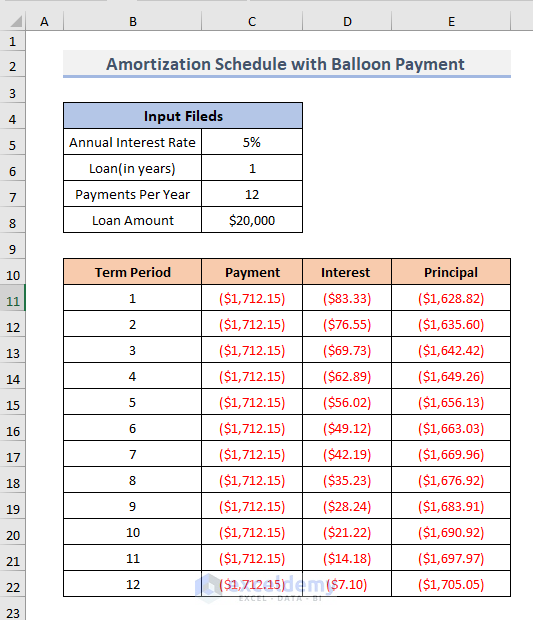
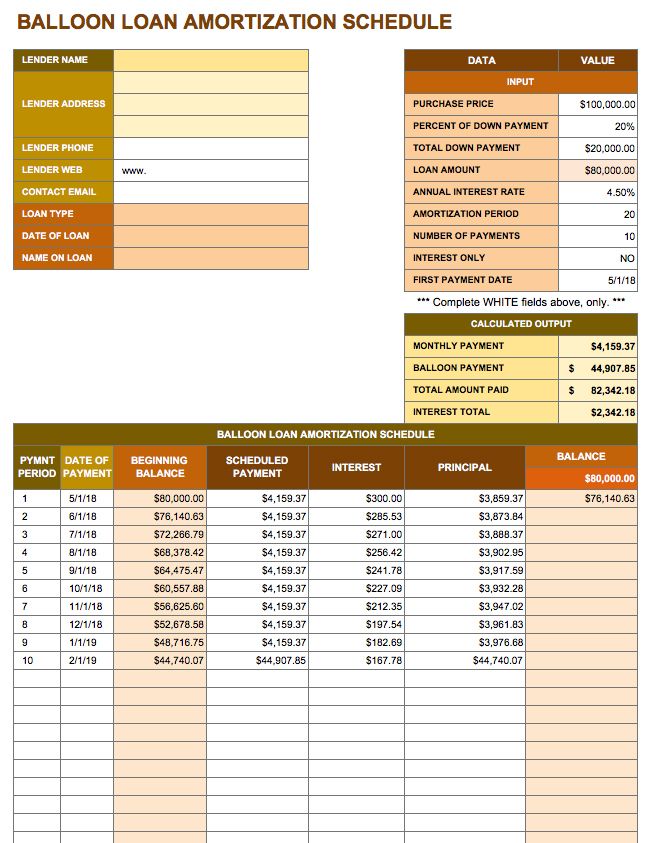
The amortization schedule for a balloon loan follows the same mathematical formula as any standard loan, but the key difference is the maturity date and the large payment at the end. Most lenders will provide this schedule upfront, but you should verify it independently using a spreadsheet or calculator to ensure there are no hidden fees or miscalculations that could affect your planning.
Practical Steps Before Committing
Before signing any balloon loan agreement, get a current payoff statement and verify the exact balloon amount. Some loans have prepayment penalties that can add several percentage points to the cost, while others might include yield spread premiums or other fees that are not immediately obvious. These details matter significantly when you are calculating your true exit cost.
Talk to multiple lenders about your refinancing options before you close the initial loan. Having pre-approval or at least a preliminary commitment from a second lender gives you a fallback position if the first lender changes their mind or if market conditions shift during the loan term. This step takes an afternoon but can prevent a much more difficult situation later.
Monitor your equity buildup and property values regularly throughout the loan term. Most people check their amortization schedule at closing and never look at it again, but tracking your actual equity position helps you identify when to start the refinancing process. Ideally, you should begin that process four to six months before the balloon is due, giving you time to address any issues without panic.
I have found that many borrowers make the mistake of assuming the balloon payment is just another refinancing event. It is not. The timing, market conditions, and your financial position all converge at a specific point in time, and missing that window can have serious consequences. Planning ahead and understanding the full cost structure is the only way to avoid unpleasant surprises.
Common Mistakes to Avoid
One frequent error is miscalculating the balloon payment amount based on an outdated amortization schedule. Loan terms can change, fees can be added, and the actual payoff figure might differ from what you estimated. Always pull an updated payoff statement within thirty days of your planned refinancing or sale date.
Another mistake is ignoring the tax implications of the balloon payment and the interest deductions. Consult with a tax professional who understands commercial lending structures, especially if you are using the property for business purposes. The interaction between mortgage interest deductions, depreciation recapture, and the balloon payment timing can be complex.
Borrowers also tend to overestimate their ability to refinance under adverse conditions. Interest rates might rise, property values might decline, or your income might change. Running stress tests on your refinancing ability before you close the original loan helps you prepare for these scenarios and avoid being caught off guard.
Final Considerations
Amortization with balloon payment is neither good nor bad in isolation. It is a tool that works well in specific situations and poorly in others. The key is understanding exactly how it works, calculating your true costs, and having a realistic exit strategy before you commit.
I have seen this structure save investors thousands of dollars in carrying costs and enable deals that would not have been possible with traditional financing. I have also seen it trap borrowers in difficult positions when refinancing options disappeared or property values declined unexpectedly. The difference usually comes down to preparation and realistic expectations rather than the loan structure itself.
If you are considering a balloon loan, take the time to understand every detail of the amortization schedule, verify the balloon amount independently, and have a clear plan for the end of the loan term. The monthly payment numbers are only part of the picture, and the balloon payment is the part that matters most when the loan matures.
Gallery Amortization With Balloon Payment
Amortization Schedule with Balloon Payment: Using Excel To Get Your ...
Amortization Schedule with Balloon Payment and Extra Payments in Excel
Excel Interest Only Amortization Schedule with Balloon Payment Calculator
Amortization Table With Balloon Payment Excel | Cabinets Matttroy
Free printable amortization schedule with balloon payment, Download ...