The mechanics are simpler than most lenders want you to think
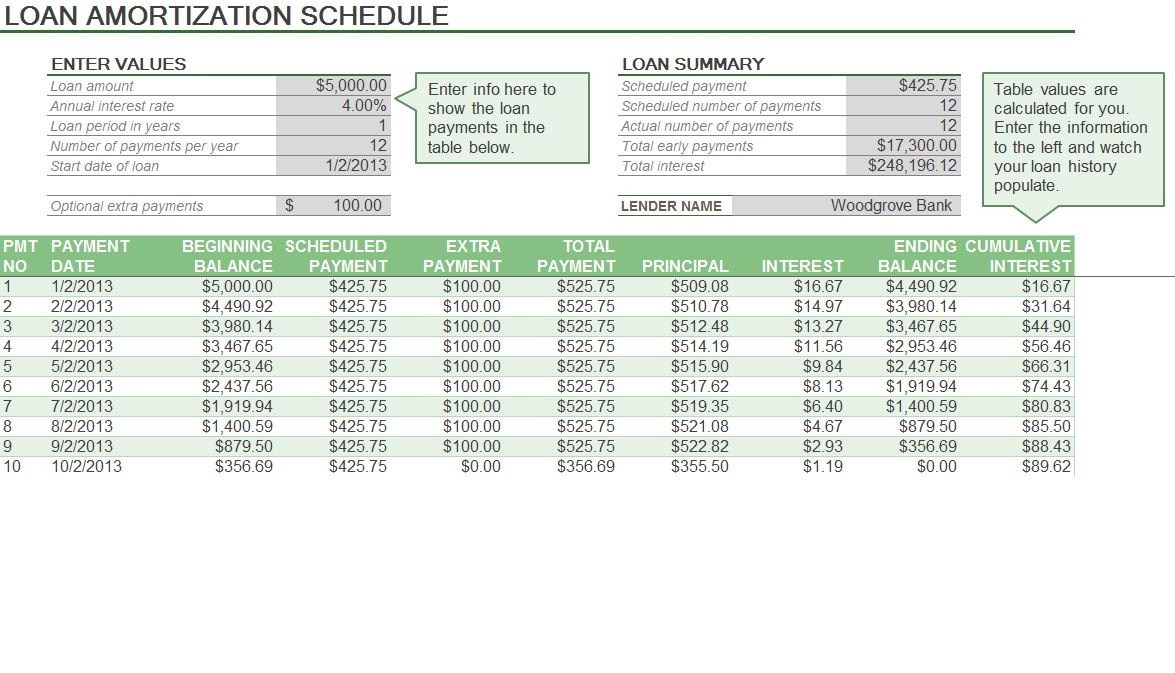
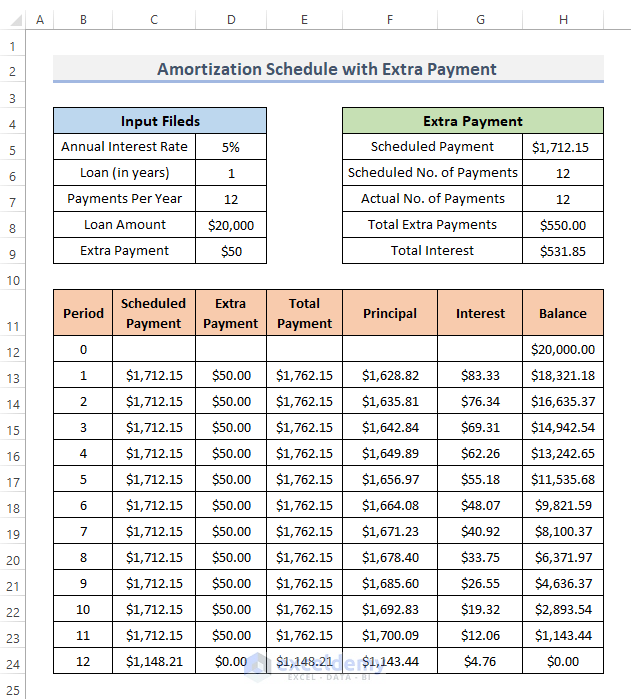
When you make an extra payment on a loan, the amortization schedule doesn't automatically restructure itself. Most people assume the payment shortens the loan term by a predictable amount, but the reality depends entirely on how your servicer applies the funds. Some recalculate monthly from the next statement. Others only adjust at year-end or when refinancing. I've watched clients lose thousands in savings simply because their lender treated a mid-month extra payment as a prepayment of a future installment rather than a direct principal reduction. The most useful tool I've used for modeling this is a simple spreadsheet-based scheduler. You build a standard amortization table, then layer in your additional principal columns and let Excel recalculate. What beginners miss is the interest savings formula: it equals (original total interest minus new total interest), and that number only holds if the extra payment hits the principal balance before interest accrues on the next cycle. If your lender applies it after the interest calculation date, you've already lost a month's worth of potential savings on that chunk. I ran into a concrete problem a while back working with a borrower who had a government-backed loan. He thought every extra dollar was going straight to principal. The loan documentation said something different. The servicer processed the payment, but a portion was routed to escrow for property taxes and insurance because of how the account was structured. This is a common edge case with FHA and VA loans where your monthly payment includes PITI, and the "principal and interest" portion is only part of the whole thing. The workaround was straightforward but tedious: I asked the borrower to submit a separate, explicit "principal-only" payment via a distinct payment channel. Lenders are required by regulation to accept these and apply them to principal immediately. The paperwork took about three weeks, but once confirmed, we tracked the impact month by month.
The counter-intuitive part nobody talks about is this: making one large extra payment toward the end of a loan's life is almost pointless. By that point, the amortization schedule has already shifted so much interest into the early periods that the remaining principal is small relative to what's left. A $10,000 extra payment in year two of a thirty-year mortgage is vastly more impactful than the same payment in year twenty-five. The math is brutal and linear. Each extra dollar at the front of the schedule eliminates future interest calculations across many remaining periods. The same dollar at the back barely moves the needle.
Building a custom amortization model
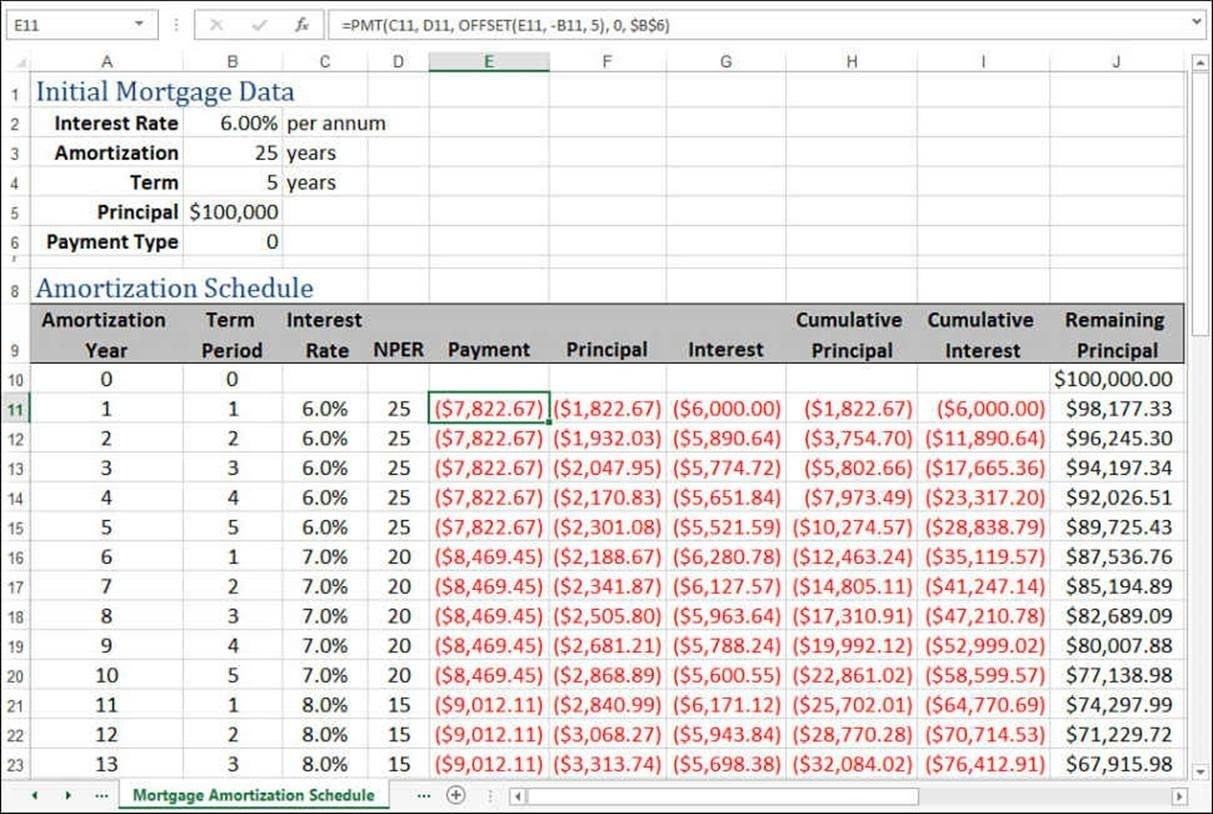
A basic Excel setup works like this. Column A holds the period number. Column B is the beginning principal balance. Column C is the regular monthly payment. Column D calculates the interest portion using =ROUND(B10*($C$1/12),2) where the rate is annual and divided by twelve. Column E is principal = C minus D. Column F updates the balance. From there, add a column for your extra principal, subtract that from F, and chain the rest down. I keep the loan terms and rate in a separate section at the top so I can swap scenarios without rebuilding the sheet. For a downloadable template, you can find free Amortization With Extra Payments tools on a number of personal finance sites, or search the Sapiens AI resources page for a pre-built sheet that handles the escrow trap I described. The key features to look for: a column that flags whether each extra payment is applied before or after the interest cutoff, and a comparison view that shows total interest under both the standard schedule and your modified one. There are real limitations here that most guides gloss over. If your loan has a prepayment penalty clause, those extra payments might trigger fees for a set window, often the first two to five years. I've seen penalty structures that charge three months' interest on the amount prepaid, which completely wipes out the math for modest extra payments. Always read the note before you start sending money. Another frequent issue is that some lenders will apply extra payments proportionally across all loans if you have multiple balances with them. That means paying extra on your car loan also reduces your mortgage less than you'd expect, because the system treats it as a blanket payment rather than a targeted one. The fix is making separate payments for each account and referencing the account number in the memo line.
Get the Full Details
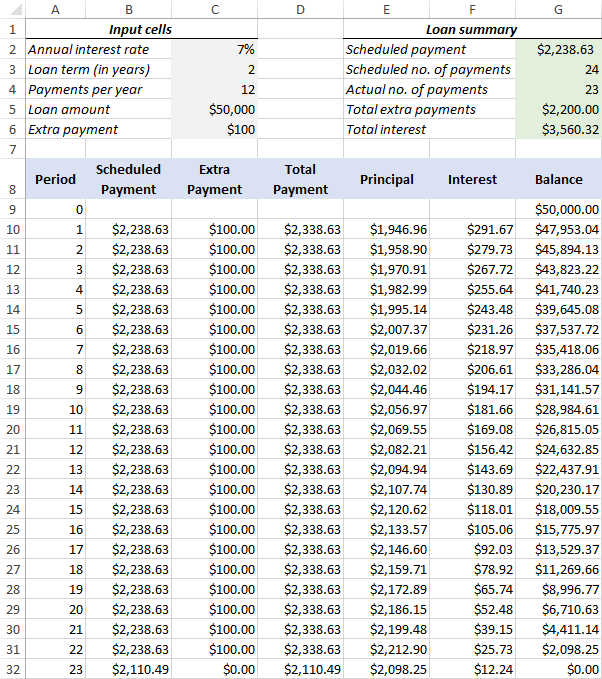
For people who just want numbers without building anything, online Amortization With Extra Payments calculators exist. They're fast but they almost never model the escrow misapplication problem or prepayment penalties. They give you a best-case scenario that looks like a straight-line reduction. In practice, you'll get maybe sixty to eighty percent of the projected savings after the lender's quirks are factored in. If you're dealing with a large extra sum and the loan is significant, spending an hour on a custom spreadsheet will give you a clearer picture than any web calculator, and the difference is usually measured in hundreds rather than tens of dollars on a typical residential mortgage.