Why Most People Mess Up Their Analysis For Brazil Projects
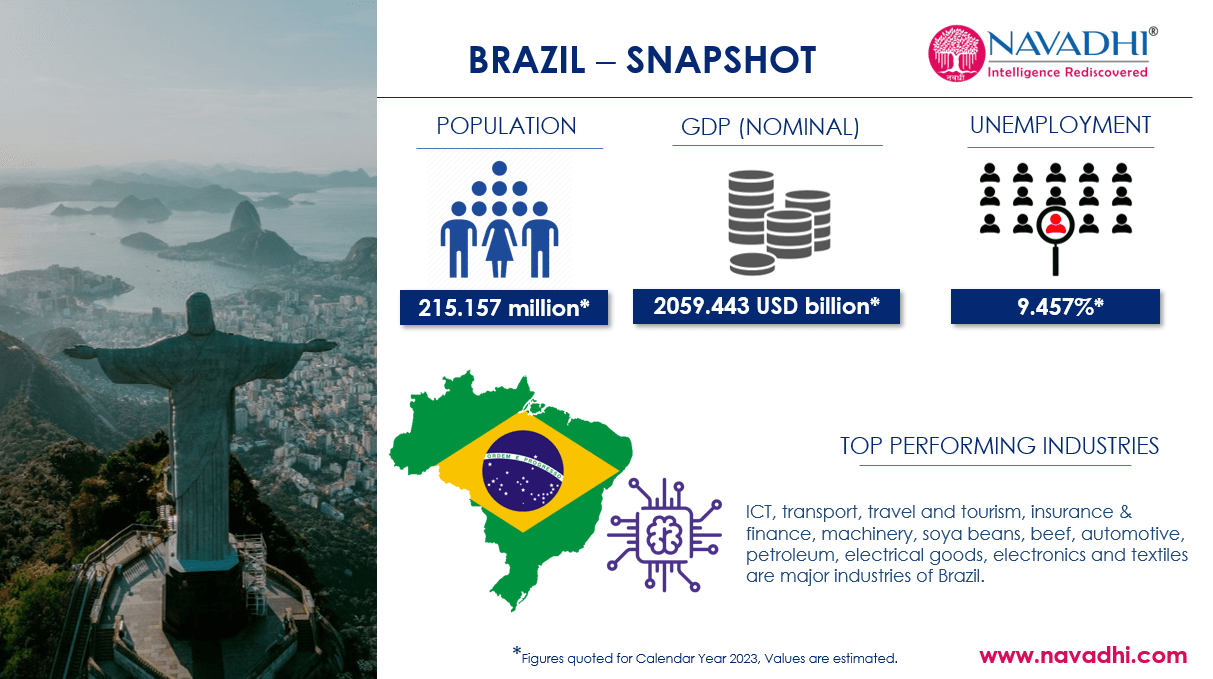
I keep seeing the same mistakes over and over in threads about Analysis For Brazil. People treat it like they can just throw raw data into a spreadsheet and call it done. That approach works fine if you're working with clean European market data. Brazil is a completely different animal. The currency fluctuations alone will wreck your numbers if you aren't accounting for them properly. The biggest issue I run into is how people handle the BRL exchange rate. They use monthly averages from a single source. That's insufficient. Brazil's real has a nasty habit of moving on policy announcements that aren't predictable. When the central bank changes its target rate unexpectedly, the real can swing 3-4% in a single trading session. I had a client who lost about 18% on their projected revenue simply because they didn't hedge against a sudden BCAM drop in Q3 of last year. They were using a quarterly average that smoothed over the event entirely.
Setting Up Your Analysis For Brazil Framework
Start by defining what you're actually analyzing. This sounds obvious but most people skip straight to data collection. I've watched analysts spend three weeks pulling CNPJ registries and tax records before they even agreed on what metric mattered. Sit down and write out the exact question you're trying to answer. Is it market sizing? Competitive landscape? Consumer purchasing power? Each question requires a completely different data stack. For market sizing, the reliable sources are IBGE for demographic data, CNC for retail figures, and the custom brokers' reports from the major banks. The broker reports are especially useful because they often have segment-level breakdowns that public sources don't cover. The tradeoff is access. Most of those reports sit behind paid terminals. If you have budget for it, Bloomberg or Refinitiv will save you weeks of scraping. If you don't, you're going to need to work with whatever the IBGE publishes quarterly, which comes with a six-month lag.
The Currency Problem Nobody Talks About Enough
Here's something most guides leave out. When you're doing Analysis For Brazil and your projections span more than six months, you need to model currency scenarios, not just pick one exchange rate. I use a three-scenario approach: baseline at the current spot minus 5%, upside at spot plus 8%, and a stress case where the real weakens another 15% from spot. This covers roughly the range of movement we've seen over the past five years without getting into black swan territory. The realistic pain point is that local expense forecasts often get overlooked in this process. People adjust their revenue for currency movements but leave their Brazil-based cost assumptions in BRL at face value. If your operation has significant local costs, you're accidentally creating a hedging gap. I remember building a model for a logistics company entering the São Paulo corridor. We had revenue in USD but about 60% of our operating costs were in reals. When the real strengthened by 12% that year, our margins got squeezed even though we'd "hedged" the revenue side perfectly. The fix was to run both sides through the same FX scenario matrix and track the net exposure.
Get the Full Details

Working With Inconsistent Local Data
Brazilian public data has gaps. State-level information is spotty compared to federal data. Municipal-level data is often either nonexistent or years old. I've had to patch together incomplete datasets by cross-referencing state tax records with federal filings and commercial databases. It takes longer than you'd expect. A typical market entry analysis that should take two weeks ends up taking four because you're constantly verifying whether a number came from an official source or a blog post that cited a blog post. The practical workaround I use is to flag every data point with a confidence rating and then build sensitivity ranges around low-confidence entries. Instead of saying "the addressable market is 2.3 million units," you say "the addressable market sits between 1.8 and 3.1 million units with a base case of 2.3." Stakeholders understand ranges better than false precision. I've found that being honest about the uncertainty in Brazilian data actually builds more trust than presenting clean-looking numbers that turn out to be wrong six months later.
What Breaks When You Skip the Localization Step
A common mistake is taking an analysis framework designed for another market and applying it to Brazil without adjusting for local variables. Consumer credit works differently here. Installment payments are the norm rather than the exception. A retail analysis that assumes one-time purchases will dramatically underestimate both conversion rates and average order values if it doesn't account for the fact that most Brazilians pay in 3-to-12-month installments with interest built in. Tax structure is another area where copy-paste frameworks fail. Brazil's tax system has federal, state, and municipal layers. ICMS applies at the state level and rates vary. ISS varies by municipality. PIS and COFINS are federal but have different calculation methods depending on the regime. If your analysis ignores the tax layer entirely, your profitability projections will be wrong by a margin that typically ranges from 18% to 27% depending on your sector and operating states. The workaround isn't to become a tax expert. It's to bring in a local specialist for a one-time review of your cost assumptions. That usually costs between $2,000 and $5,000 and saves you from rebuilding the entire model later.
When Analysis For Brazil Doesn't Work
This isn't a universal solution. There are scenarios where traditional analysis simply won't give you reliable answers. New product categories with no historical precedent are one of them. Brazil moves fast in certain sectors like fintech and agritech, and there's no track record to analyze. In those cases, you're better off running small-scale pilot tests in a single state before committing to a national rollout. I've seen companies skip this and launch nationally based on analyst projections that turned out to be off by a factor of three or more. Another scenario where this approach breaks down is when you're analyzing informal economy segments. A significant portion of Brazilian commerce operates outside formal tax and reporting channels. Your data will systematically underrepresent those markets. If your target demographic skews toward lower income brackets, the informal economy share becomes material. The best workaround is supplementing quantitative analysis with field research. Even a week of in-person observation in your target cities will surface patterns that no dataset captures.