What Actually Goes Into One
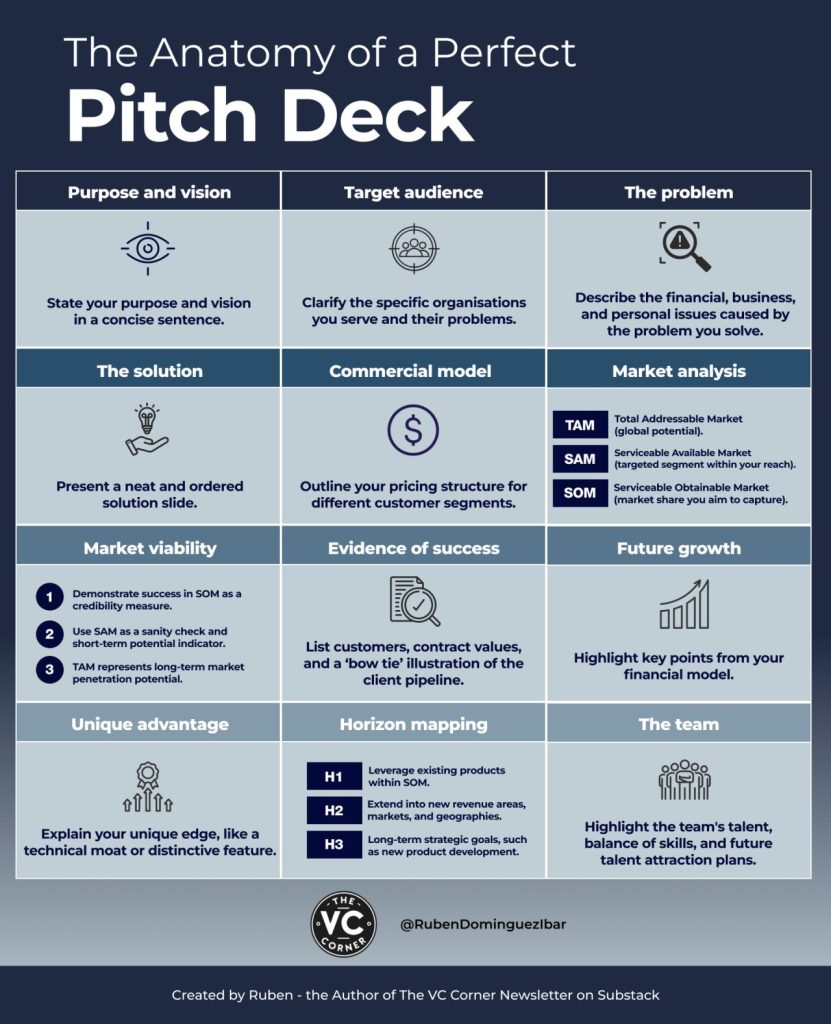
A pitch deck is just a slide presentation you hand to investors before a meeting. Ten to fifteen slides, maybe twenty if you're showing off. The most common mistake I see people make is building a deck that reads like a company history rather than a sales document. It needs to work as a standalone artifact AND as a conversation starter. Those are two different things. The standard sequence runs like this: problem statement, solution, market size, product demo or visuals, business model, traction so far, competitive landscape, team slide, financial projections, and the ask. That's the template. Most decks follow it. Some of them still get thrown in the trash because the content inside those boxes is generic fluff.
Anatomy Of A Pitch Deck: The Slides That Actually Move
Here's what each section is supposed to do, not what beginners think it's for. The problem slide should establish that you're solving something real and expensive. Not something inconvenient. Something that costs people money or time at scale. I once had a founder show me a deck where the problem was "people don't have enough entertainment options on weekends." We stared at it for forty-five seconds and I said nothing. She understood. The problem needed to be quantified and specific, not existential. The solution slide is where most decks get too vague. Don't describe features. Describe the outcome. What changes after someone uses your product? A SaaS company replacing a spreadsheet workflow is infinitely more compelling than a company that "empowers users to collaborate in real time." One tells me the job. The other sounds like marketing copy.
The market slide is where I see the worst abuse of TAM, SAM, and SOM terminology. Bottom-up sizing beats top-down every time. If you claim a seven billion dollar market because "there are 80 million dog owners in America," nobody will take you seriously. If you claim four hundred million dollars because you know you can sell thirty thousand units at roughly thirteen dollars per month to a specific segment you've already validated, that's a number someone can argue with. Arguable numbers build trust. Round optimistic numbers destroy it. Traction is the single most important section, yet people treat it like an afterthought. Revenue charts, user growth curves, pilot commitments, waitlist numbers. Put it first if you have it. VCs don't care about your vision. They care that someone else already agrees with your vision enough to give you money or data. A deck with strong traction and mediocre slides will get replies. A deck with weak traction and beautiful slides goes into the "we'll circle back" folder, which means never. The business model slide needs to answer one question plainly: how do you make money? Subscription, transaction fee, licensing, advertising, services? If you need three paragraphs to explain it, you probably don't have a clean model yet, and that's worth admitting on the slide itself. "We're figuring out monetization" is not a business model. It's a research phase.
Get the Full Details

Competition doesn't require a grid. A two-by-two matrix with you in the top right corner is the laziest thing in venture capital. Show who your actual alternatives are. Include indirect competitors. The spreadsheet your customer currently uses is a competitor. The do-nothing option is a competitor. Listing them shows you understand the landscape. The team slide is not a resume dump. Two lines per person. Relevant experience, previous exits or notable achievements, and why this team together is the right one. I've seen decks with six founders and a paragraph about each. Cut it in half. The slide should make me want to Google the people, not read their LinkedIn summaries. The financials slide doesn't need five years of line-item detail. Three years. Revenue, gross margin, and headcount. Show that you understand unit economics. If you can't explain your CAC payback period in one sentence, don't put a five-year projection on the slide. It will look like fiction, because it is.
The ask should state the amount, the instrument, and what the money buys you. "Raising two million on a safe with a five million cap to reach twelve months of runway and hit fifty thousand active users." That's clear. "Raising funds to grow the business" is a paragraph that goes nowhere. I spent two weeks rewriting a client's deck last quarter. Their original version had seventeen slides and a narrative problem that took eight minutes to read. We cut it to eleven. The core change was moving their product demo from slide four to slide three and merging their market analysis into the problem section. The version we sent out got threeterm sheet requests in the first week. The previous version had gotten polite rejections for four months straight. The content was the same. The structure forced investors to engage with the actual product earlier instead of wading through context. Another thing nobody tells you: your deck format matters. PDF is standard. PPTX raises questions about whether it opened correctly on their machine. Keynote is fine if they're Apple users but looks broken otherwise. I always send a PDF and a Google Slides link as a backup. Takes thirty seconds and prevents one class of avoidable embarrassment where an investor opens the file and sees everything shifted to the wrong aspect ratio.
The biggest blind spot I see is the assumption that a deck is a document to be consumed in one sitting. It's a teaser. You should be able to summarize it in three minutes if someone asks. If it takes ten, the deck is doing too much work. Every slide should survive a rapid verbal walkthrough. That means minimal text, visual clarity, and data points that hold up under scrutiny. If you've got traction, lead with it. If you don't, lead with the problem and the depth of your insight into it. Those are the two paths that work. Everything else is decoration.