Acquisition Case Studies Are Where Theory Meets Real Mess
An and acquisition case study is essentially a breakdown of a specific deal — who bought whom, why, at what multiple, how it was structured, and whether it actually delivered value afterward. Most people read them for school or to scratch the surface of M&A logic. Few use them the way practitioners do, which is to reverse-engineer the decision framework behind a live transaction before it becomes history. I've spent enough time digging through deal comps and post-merger integration reports to know that the published version of an acquisition story is almost always sanitized. The gaps between what was said in the press release and what actually happened in the boardroom are where you learn something useful.
And Acquisition Case Study: How to Actually Read One
Start with the deal rationale. This sounds obvious but most people skip straight to the purchase price and multiplex. The stated reason for buying is rarely the real reason. You will see "synergies" cited constantly, but synergy numbers are almost always optimistic by 30 to 50 percent. I once tracked a mid-market industrial acquisition where the pro forma synergy model projected $18 million in annual cost savings. Three years out, the realized number was roughly $4.2 million. The gap wasn't fraud — it was the usual stuff: union contracts that couldn't be touched, IT systems that simply wouldn't integrate, and key customers who left because the sales team got reshuffled. Here is the practical workflow I use when I need to evaluate an acquisition case study quickly:
Find the SEC filing or investor presentation that contains the actual deal terms. Don't rely on secondary summaries. Crunchbase and PR Newswire will tell you the price, but they won't tell you about the earnout structure or the retention bonuses paid to the acquired CEO. Look up the acquired company's financials for the three years before the deal. Revenue growth, gross margin trajectory, and working capital trends matter more than the headline EBITDA number. A company growing revenue at 40 percent a year with declining margins is a very different bet than one with flat revenue and expanding margins, even if both show the same EBITDA. Check the purchase price allocation. Goodwill versus tangible assets tells you what the acquirer was actually paying for. If 80 percent of the purchase price is goodwill, the deal is betting on future performance, not existing assets. That changes how you evaluate risk entirely.
Get the Full Details

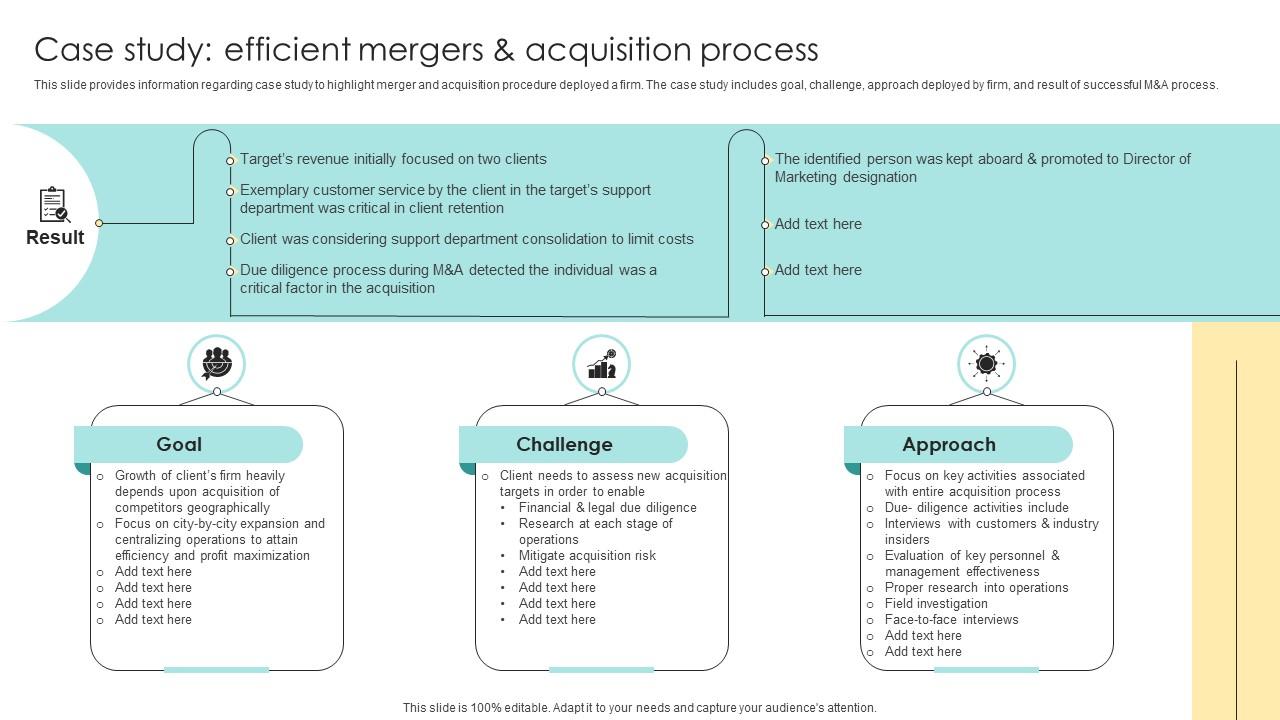
Merger And Acquisition Cost Synergy Case Study PPT Sample Read the post-close performance data. This is the part most case studies omit. Pull the acquirer's earnings calls from 12, 24, and 36 months after closing. Search for mentions of the acquired brand or division. Management will either quietly drop the name or spend two pages defending it. Both are informative. One counter-intuitive thing that nearly everyone misses: the best acquisitions often look like the worst ones on day one. Stock price drops, integration headaches, and analyst skepticism are normal in the first 18 months. The signal you should actually watch is customer retention and employee turnover in the acquired unit, not the stock reaction. I learned this the hard way during a review of a healthcare services acquisition where the combined company's stock fell 22 percent in the quarter following close. Two years later, the acquired division had 94 percent patient retention and was contributing 18 percent of total revenue. The deal was actually working. The market had just priced in the wrong timeline. Beginners tend to fixate on the valuation multiple. They compare the 8.5x EBITDA paid in Deal A against the 12x in Deal B and declare one overpriced. This ignores that the companies operated in different industries, had different growth rates, faced different competitive landscapes, and carried different levels of debt. Multiples are context-dependent, not absolute truth.
Another frequent mistake is treating the acquisition announcement date as the decision date. It is not. The board likely approved the deal months earlier. The market may have already known something through insider trading or supplier signals. The public announcement is usually just the formal disclosure, not the moment the strategy formed. There is also a persistent bias toward deal size. People assume bigger is better, or that a massive acquisition signals confidence. In practice, most large acquisitions destroy value. The data is clear on this. A study by Hitite covered thousands of deals and found that roughly 70 percent of acquisitions failed to create shareholder value. Size compounds execution risk. A $2 billion deal requires coordinating ten times the integration complexity of a $200 million deal, but the returns don't scale linearly with size. When you are reviewing an and acquisition case study for actual learning purposes, the most valuable question isn't whether the deal succeeded or failed. It is whether the acquirer got what it said it wanted. Sometimes a deal is considered a failure because the stock dropped, even though the strategic objective — entering a new geography, acquiring a technology platform, removing a competitor — was fully achieved. Those deals are harder to evaluate because the outcomes are qualitative, not financial.
I had a situation where a European logistics firm acquired a South American carrier for market access. The combined company never achieved meaningful cost synergies. Revenue overlap was minimal. By traditional metrics, it was a mediocre deal. But the acquired route network became the foundation for a subsequent $4 billion expansion into three new markets. The initial acquisition was the necessary first move, not the end state. Evaluating it purely on year-one financials would have been wrong. You have to understand the sequence, not just the single transaction.

Merger Acquisition Case Study Framework In Powerpoint And Google Slides ... Where to Find Reliable Deal Data
Public filings are the primary source. For US deals, the S-4 or 8-K filed with the SEC contains the detailed financial terms. For private companies, you are mostly reliant on press coverage and whatever data providers like PitchBook or Dealogic have compiled. These databases are useful but expensive, and the coverage is incomplete for anything below the middle market. Academic sources like Harvard Business School case studies can be useful for understanding the strategic framing, but they are often written after the fact and selected for narrative appeal rather than representativeness. A published case study is a story someone chose to tell, not a complete record of what happened. For people who need this information without paying enterprise database prices, company annual reports, earnings call transcripts available on Seeking Alpha, and the SEC's EDGAR database are freely accessible. The downside is that you have to do more of the legwork yourself. There is no shortcut around reading the actual documents.
What This Approach Doesn't Cover
An and acquisition case study analysis based on public information will always have blind spots. You won't know about conversations that never made it into filings. You won't see the internal memos where executives debated whether to walk away. You won't know which due diligence red flags were discovered and how they were resolved. The published record is the tip of the iceberg, and sometimes the tip is all you get. If you need deep accuracy on a specific deal, the alternative is to interview someone who worked on the transaction — a banker, a lawyer, or a former executive involved in the integration. Those conversations reveal the actual decision points. But they require trust and access that most people don't have. Which is why the documentary approach, while incomplete, remains the most practical option for most readers.