On Approximations in Maths
I spent way too many hours working through floating-point precision problems in numerical computation before I really understood what approximations actually mean in practice. Everyone learns about Taylor series and error bounds in undergrad, but the gap between textbook examples and real engineering work is substantial. This is about how approximation actually works when you're building something that needs to produce correct results under constraints. Approximation in mathematics refers to finding a value or function that is close enough to the true solution for practical purposes, while accepting some quantified error. The core idea isn't just getting close; it's knowing how far off you are and whether that deviation matters for your application. A numerical method might give you a result accurate to five decimal places, but if your system requires twelve, you've got a problem regardless of how elegant the math looks. The distinction between an approximation and an exact answer is rarely binary. It's a spectrum measured in error bounds. What counts as acceptable depends entirely on context. A 0.1% error in a financial model might mean the difference between profit and loss. A 0.1% error in simulating particle trajectories might be perfectly fine. You need to know the tolerance before you pick a method.
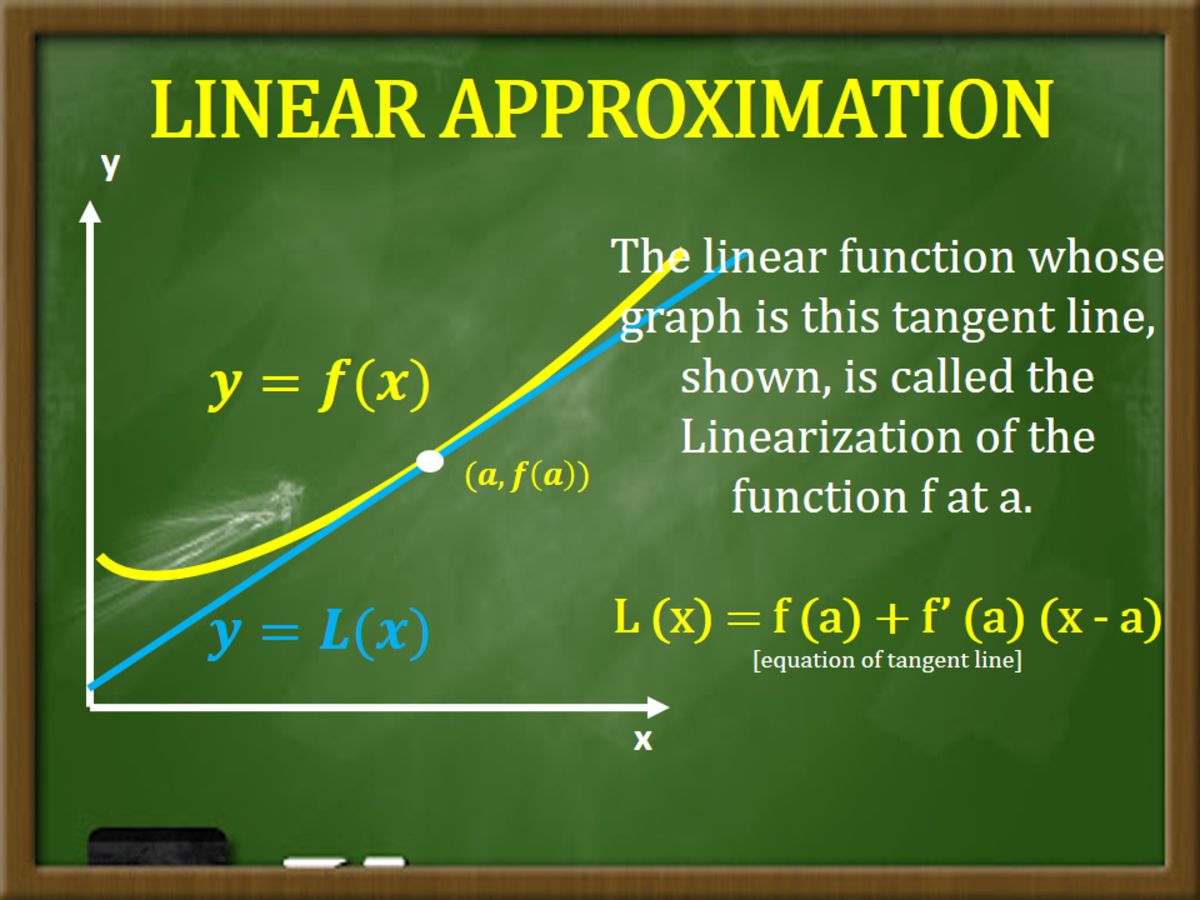
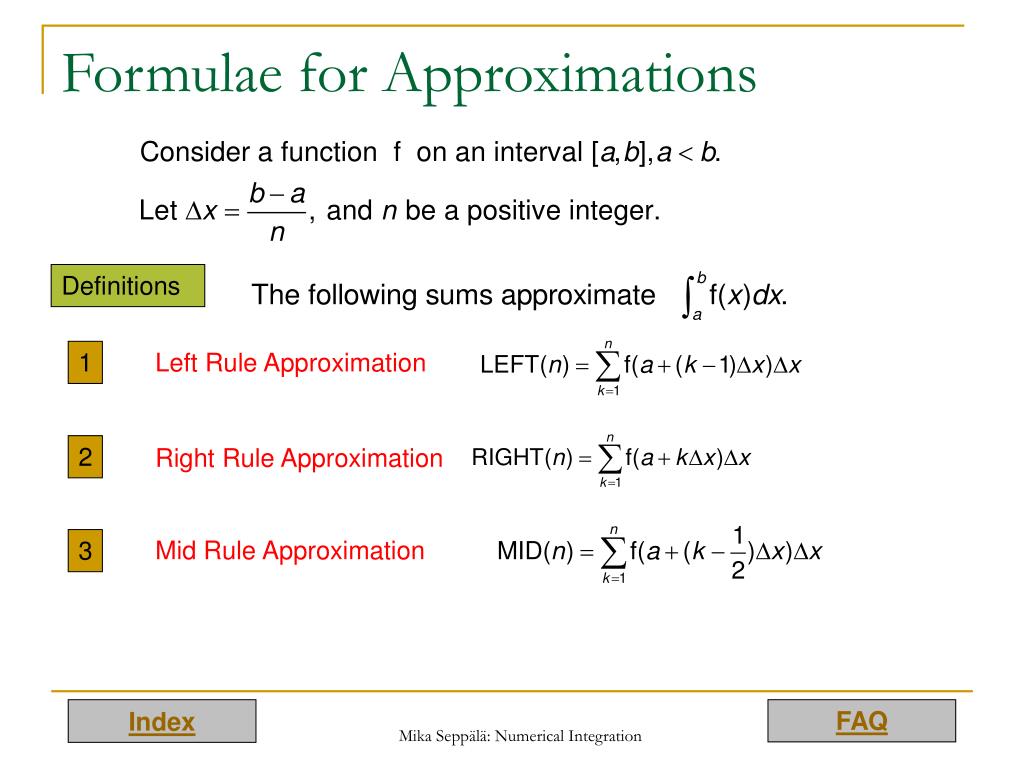
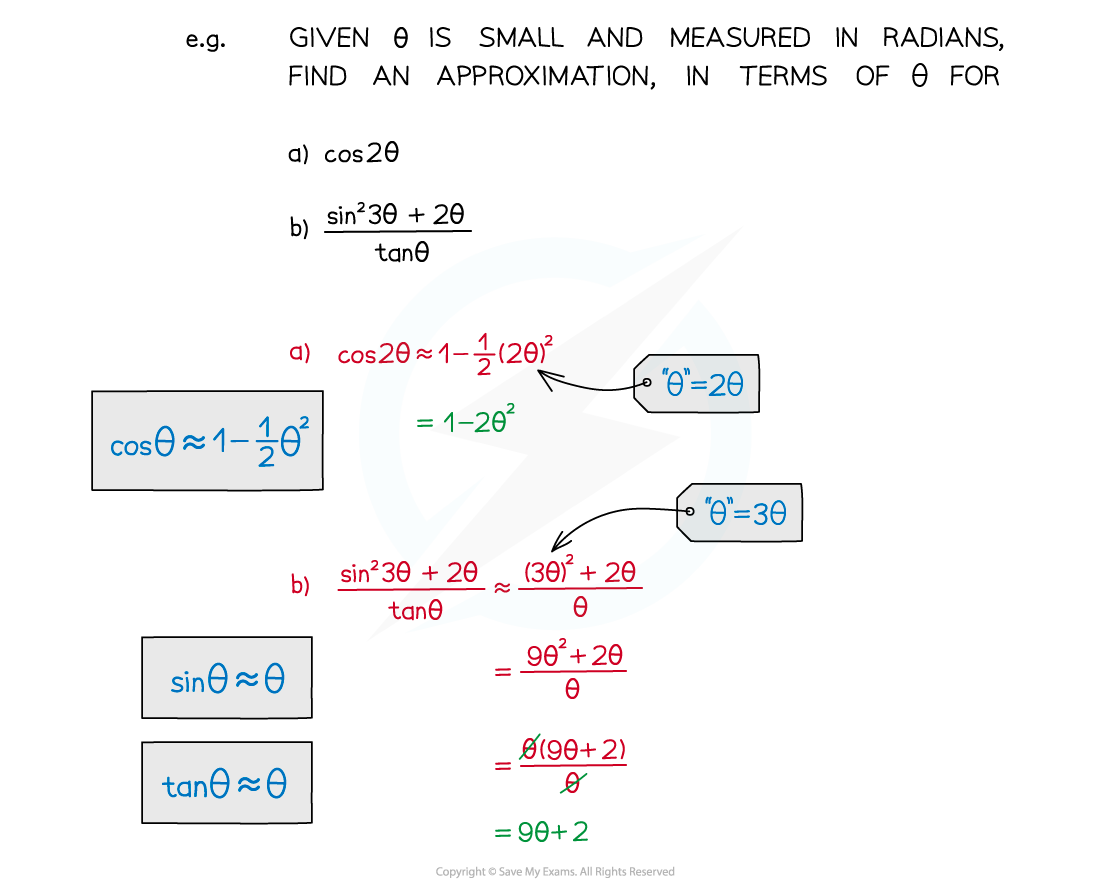
Common approximation categories: Series approximations use truncated Taylor or Fourier expansions to represent functions. Numerical integration replaces definite integrals with finite sums, typically using quadrature rules like Simpson's method or Gaussian quadrature. Interpolation estimates unknown values between known data points using polynomial or spline bases. Iterative methods converge toward solutions through repeated refinement, like Newton-Raphson for root-finding. Each category has tradeoffs in accuracy, computational cost, and implementation complexity.
Working with Approximations in Practice
Here is how I approach this, and it's not particularly elegant. I start by identifying what I'm trying to approximate and what the error budget is. Then I pick the simplest method that stays within that budget. Most people default to the most sophisticated tool available, which is usually unnecessary and introduces failure modes you don't need. I once had to approximate the integral of a oscillatory function over a large domain for a signal processing application. Standard quadrature methods failed because the integrand changed frequency faster than the adaptive step could resolve it. The function looked like sin(x^2) scaled by a slowly varying envelope, which is basically a chirp signal. I spent about three days trying to make adaptive Simpson's rule work before I realized the issue wasn't the method, it was the sampling density relative to the oscillation frequency. The workaround was to use stationary phase approximation, which is a technique from asymptotic analysis. Instead of numerically integrating the full function, I approximated the integral by examining where the phase function's derivative is zero. This reduced a computation that would have required millions of function evaluations down to about forty. The error was controlled by tracking higher-order terms in the asymptotic expansion. I validated the result against a brute-force numerical integral at a handful of test points to confirm the approximation held. It took me about two hours to implement after the insight, versus roughly sixteen hours of failed debugging on the standard approach.
Get the Full Details
Pitfalls That People Miss
The first thing beginners get wrong is conflating accuracy with precision. You can have a very precise approximation that is systematically biased. A truncated series might consistently overestimate by a small margin across the entire domain. That error compounds differently than random numerical noise, and standard error analysis sometimes doesn't catch it because it's looking at the wrong kind of deviation. The second mistake is ignoring the domain of validity. Taylor series approximations work well near their expansion point, but they can become wildly inaccurate far from it. I've seen engineers use a third-order Taylor expansion of a transcendental function across a range where the fourth derivative alone exceeded the function value itself. The result looked reasonable at first glance until you compared it against a direct evaluation at a single point. Always verify your approximation across the full domain you intend to use it in. Error propagation is another area where people get burned. When you chain multiple approximations together, their errors combine in ways that aren't always obvious. Adding two approximated values doesn't just add the errors linearly. Multiplying them can amplify relative errors. If you're approximating intermediate steps in a calculation, track both absolute and relative error bounds through each operation. A simple Monte Carlo perturbation of your inputs can reveal sensitivity that analytic error bounds miss.
When Approximations Fail Completely
There are situations where approximation methods break down or give misleading results, and it's important to recognize those early. Stiff differential equations are one class. The timescales involved vary so dramatically that explicit numerical methods require impossibly small steps to remain stable. Implicit methods help but introduce their own convergence issues. If your problem has this characteristic, approximation isn't the right framing. You need specialized solvers or reformulation. Another failure case is extrapolation beyond the range of your data or expansion point. Interpolation between known points is generally reliable with adequate data density. Extrapolation beyond them is unreliable almost always, and polynomial interpolation can produce Runge's phenomenon with wildly oscillating results between points. If you must extrapolate, use the simplest model possible and quantify the uncertainty explicitly. Don't pretend the result is anything more than an informed guess.
A Note on Verification
No approximation is useful unless you can verify it. The standard approach is to compare against a known exact solution when one exists, or against an independent higher-accuracy method when it doesn't. I typically run a baseline at high precision using arbitrary-precision arithmetic or a finer discretization, then measure the deviation of my approximation method across a grid of test cases. This takes time, usually anywhere from thirty minutes to an hour for a moderately complex problem, but it prevents the embarrassing situation of deploying a silently wrong result. The best approximations come from understanding both the mathematics and the specific constraints of your problem. The worst ones come from applying the first method you remember from a textbook without considering whether it fits. Start with the error budget. Pick the simplest method that satisfies it. Verify it. Move on.