The Problem With APR Calculation
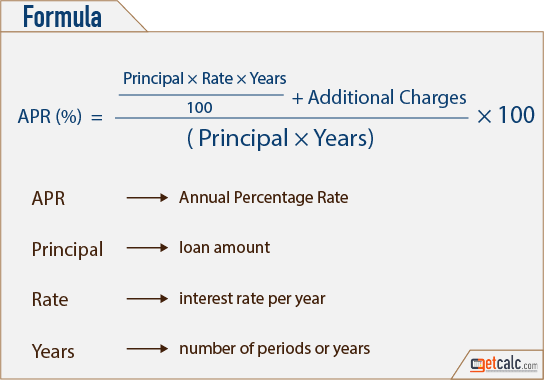
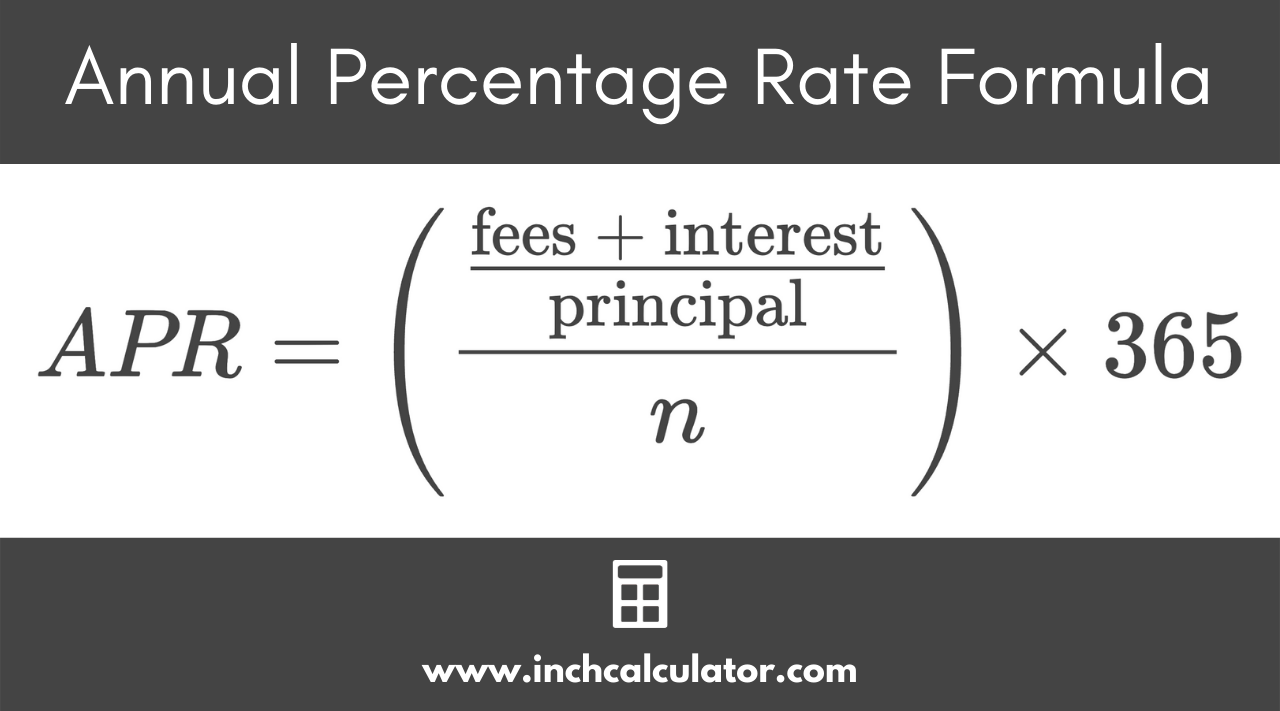
Most people try to calculate Annual Percentage Rate manually and get tangled in compounding periods, fee structures, and payment schedules that don't align with the nominal rate. I spent a couple of years working with loan origination systems before I learned to stop fighting the math and just use the right approach. The actual formula is straightforward, but the implementation is where things fall apart for most people.Annual Percentage Rate Formula Breakdown
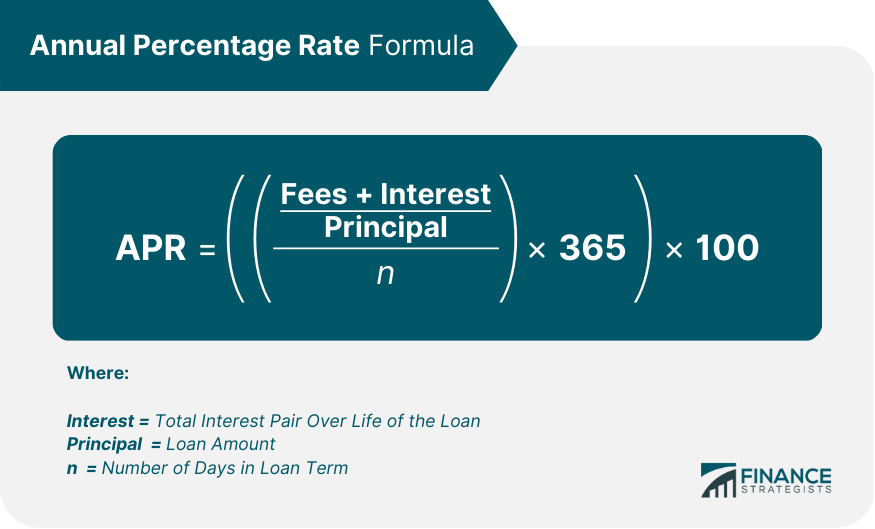
The standard formula is: APR = (1 + r/n)^(n) - 1 Where r is the nominal interest rate and n is the number of compounding periods per year. This is the basic version. In practice, you need to adjust it for fees and the timing of cash flows, which is why lenders are required by law (Regulation Z in the US) to use the actuarial method or the United States Rule for disclosures.
I used to work with a spreadsheet that calculated APR using the simple formula above and sent it back to us every time we needed to validate a loan file. It was consistently off by 0.12% to 0.34% on any loan that had points or origination fees folded into the cost. That gap looked small until you were dealing with a $2 million portfolio and a compliance officer who actually knew how to read the regulations. The fix was switching to an iterative solver. You set up the cash flow equation where the present value of all payments equals the amount financed, then solve for the rate using Newton-Raphson or bisection. Most people don't have a financial calculator lying around, so the spreadsheet approach with the Goal Seek or Solver function works fine if you structure the cash flows properly.
How to Actually Calculate It
Here is the step-by-step that I ended up using instead of whatever the textbook version says: Step one: Determine the total amount financed. This is the principal minus any fees the borrower pays upfront. If the borrower pays points at closing, those get subtracted from the loan amount for APR purposes. I found this out the hard way when a borrower came back to us claiming their APR was higher than what our system showed. They had paid $3,500 in discount points we hadn't included in the calculation. Once I added that to the cost side, the numbers matched. Step two: Map out every payment date and amount. This includes principal, interest, and any recurring fees that are part of the loan cost. Late fees don't count unless they are mandatory and structured into the repayment schedule.
Get the Full Details
Step three: Use the present value equation. The sum of all discounted payments at the unknown rate must equal the total amount financed. This is a polynomial equation and there is no closed-form solution for most real-world scenarios, which is why iterative methods exist. Step four: Run the iteration. Start with an estimate close to the stated rate and let the solver converge. The Newton-Raphson method usually finds the answer in three to five iterations if your starting point is reasonable. I set up a template that does this automatically and it cuts the calculation time from maybe twenty minutes to about ninety seconds.
Pitfalls That Come Up
One thing nobody tells you: the APR formula breaks down completely when a loan has negative amortization. If the minimum payment doesn't cover the accrued interest, the payment pattern becomes irregular and the standard formulas assume something that isn't true. I had to manually adjust the cash flow schedule to reflect the actual payment amounts before running the solver, or the APR would come out negative, which is impossible and should trigger a red flag immediately. Another issue is when fees are structured as recurring charges rather than upfront costs. The APR regulation requires certain fees to be included regardless of when they are paid. Origination fees, processing fees, and certain administrative charges all get folded into the calculation even if they are billed monthly instead of at closing. Most people miss this distinction and end up with an APR that is too low because they excluded recurring fees that the law requires them to include. The compounding frequency matters more than people realize. A loan with monthly compounding at 6% nominal rate has a different effective APR than one compounded quarterly. The difference is small on short-term loans but compounds over time, especially on longer maturities like mortgages. If you are comparing two loans from different institutions, make sure you are looking at the actual APR figures, not just the nominal rates. Two loans can have the same 7% rate but very different AP Rs depending on how the fees are structured and when they are charged.
What To Do When The Formula Doesn't Work
When the standard APR formula produces impossible results or inconsistent numbers across different tools, switch to a dedicated calculator or regulatory compliance software. I stopped trying to build custom solutions for anything beyond simple consumer loans after I discovered that the Treasury yield curve methodology handles multi-period cash flows more accurately than any spreadsheet template I could construct. For commercial lending and complex structures, the regulatory software path is worth the licensing cost because the alternative is doing manual calculations that will get flagged during an audit anyway. If you need a free resource, the Federal Reserve publishes APR calculation guidance and examples that cover most common scenarios. The Consumer Financial Protection Bureau also has a comparison tool that shows exactly how different fee structures affect the final rate. I reference these when I need a quick sanity check on my own work rather than trusting a third-party calculator without verification.