Using the Solutions Manual Without Cheating Yourself Out of Learning
The textbook by Hill, Griffiths, and Lim is dense, and the selected exercises answers are one of the most downloaded academic PDFs on the internet. I have seen students use them correctly and I have seen them use them in ways that make the semester take twice as long. This is about the practical side of working with those solutions, not a debate about academic integrity, because that is already written into stone at every institution. The solution manual covers roughly a third of the end-of-chapter problems in the standard editions. Chapter 1 through Chapter 10 of the later printings have selected answers, with more coverage in Chapters 2 through 5 where the core regression machinery lives. The remaining problems are left without worked solutions unless you track down supplementary materials from the companion website, which changes from edition to edition and has been taken down several times over the years. Here is how I actually approached it when I was teaching undergraduates and when my own students came to me frustrated after getting a problem wrong.
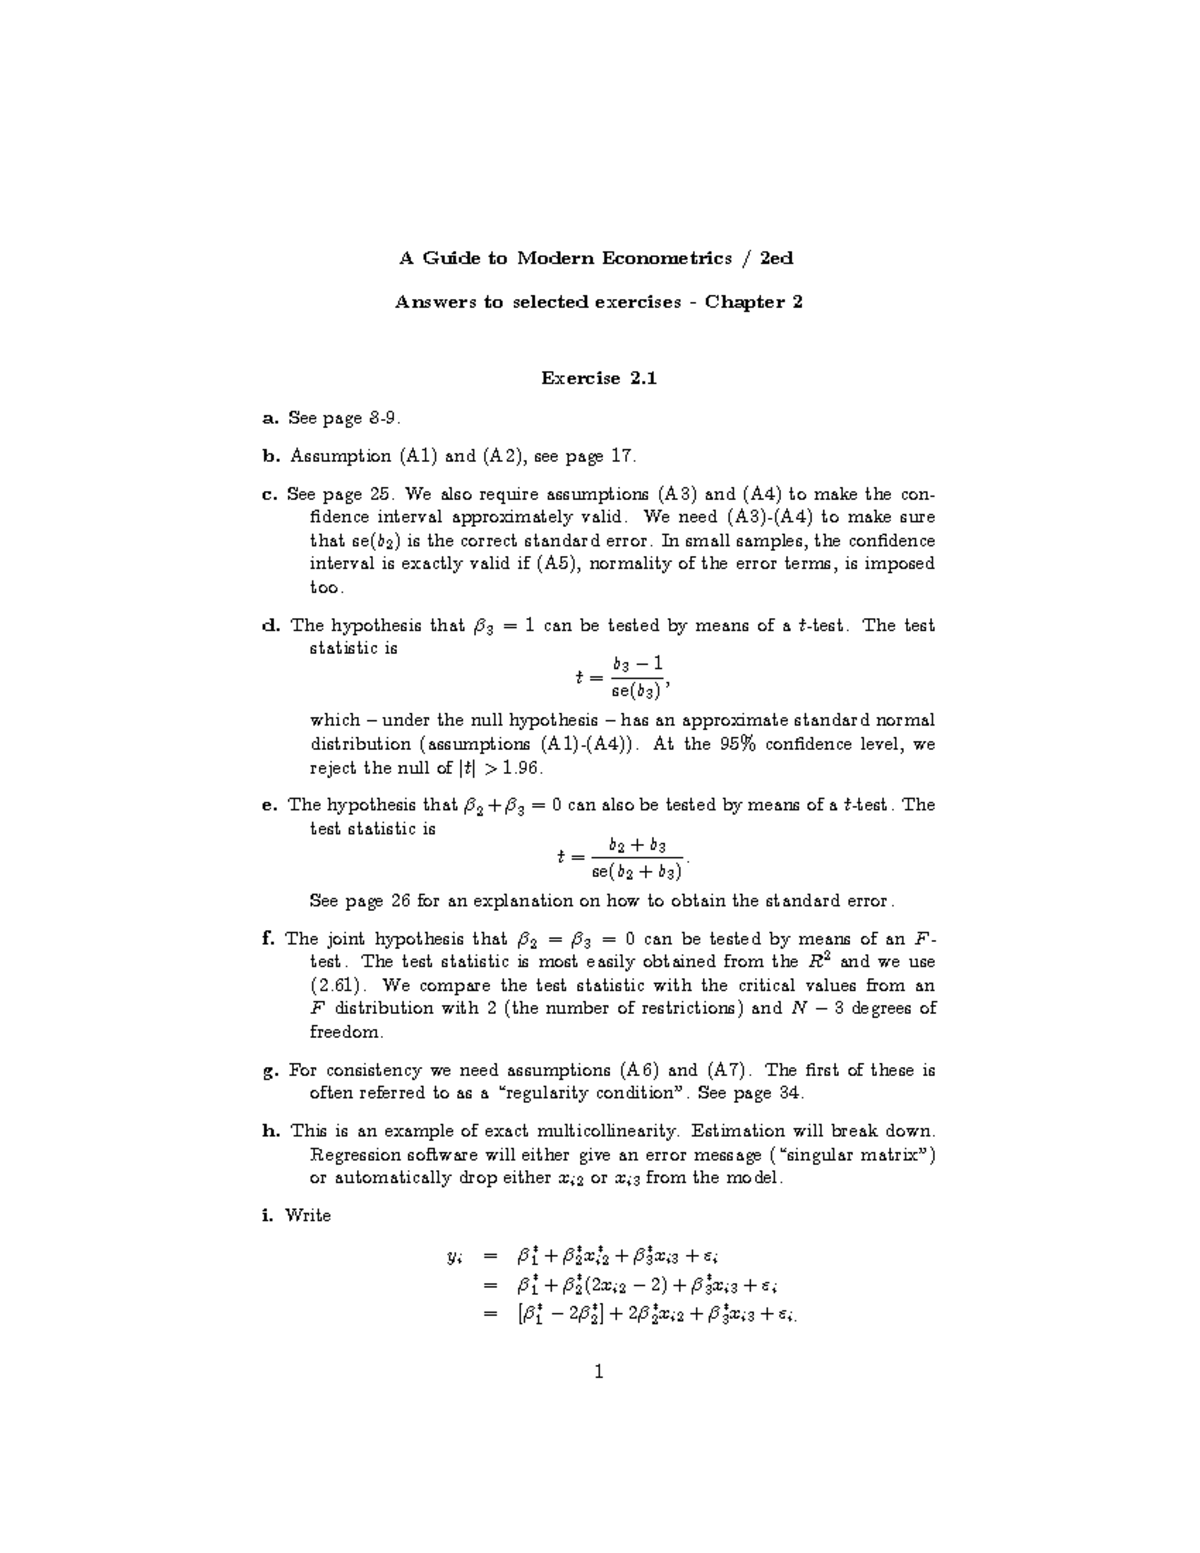
Start by attempting the problem blind. Write down what the question is asking, list the relevant formulas from the chapter, and work through it on paper before you ever look at the manual. The process takes longer, but it reveals exactly where your gap is. If you look at the solution first, you tend to recognize the steps and think you understand them, which is a false sense of competence. That pattern showed up repeatedly in my office hours. When you do open the solution manual, read it actively. Do not just scan the answer and move on. Cover the next step, try to derive it yourself, then uncover the manual to check. This turns the manual from a cheat sheet into a practice partner. I once had a student who was consistently losing points on Chapter 4 problems involving heteroscedasticity. The manual showed a GLS transformation, but he kept trying to apply OLS formulas directly. We went through three problems where he covered the transformation steps first and only revealed the answer after deriving it. He stopped making that mistake for the rest of the term. One thing the manual does not always make clear is when it skips steps. Several editions omit intermediate algebra, especially around matrix derivations in the later chapters. If you get stuck on a line that seems to appear out of nowhere, check whether the authors compressed the derivation. The missing algebra often involves premultiplying by a weighting matrix or applying the chain rule to a log-likelihood. I keep a separate notebook for these gaps and fill them in by going back to the chapter's theoretical sections. It takes about ten to fifteen extra minutes per problem, but it prevents the confusion of thinking the math is magic rather than mechanical.
Another issue is notation drift across editions. The third edition and the fifth edition use slightly different symbols for the variance-covariance matrix and for the explained sum of squares. If you are cross-referencing solutions from a different edition than your textbook, you will misidentify variables. I ran into this myself when a graduate student showed me a solution that did not match their homework assignment. The mismatch was purely notational, not conceptual. The fix was to map each symbol to its definition rather than assuming they looked identical.
Get the Full Details
Where to Find the Solutions
The official companion website for the textbook has shifted ownership and access multiple times. Wiley, which publishes the book, used to host downloadable solution files, but they have moved many of these behind a faculty access wall in recent years. The PDF that circulates widely online is usually a pre-release or instructor copy. It is accurate, but if you are an individual student without course credentials, you may encounter broken links or watermarked pages that are harder to read. University libraries sometimes have a copy in their reserves section. This is the cleanest route if your campus holds one. The physical copy avoids formatting issues, and you can flip between chapters without reloading files. I recommend checking the library catalog for the specific edition you are using, since the exercise numbers do not always align perfectly between editions.
Common Mistakes When Working Through the Manual
Students often treat the selected answers as exhaustive, which they are not. Many problems have multiple valid approaches, and the manual only shows one. If your method leads to the same final result through a different path, it is still correct. I have seen students discard valid work because it did not match the manual's sequence, which wastes time and confidence. Another frequent error is skipping the interpretation step. The manual frequently gives numerical outputs without writing out what they mean in context. A coefficient estimate of 0.47 with a t-statistic of 2.3 is not a complete answer. The exercise is also asking whether the effect is statistically significant at the chosen level and what the economic interpretation is. Leaving out the verbal explanation is where points disappear on exams. Matrix-based problems in the later chapters are another weak spot. The manual sometimes presents results in compact matrix form that assumes familiarity with partitioned inversion and the Frisch-Waugh-Lovell theorem. If you are not comfortable with those tools, the solution will look impenetrable. I suggest reviewing those proofs in the chapter appendix before relying on the manual for Chapters 8 and beyond.
What the Manual Cannot Do For You
It cannot replace understanding the assumptions behind each estimator. The exercises test your ability to identify violations of the classical linear regression model, to choose the right diagnostic test, and to interpret output correctly. If you memorize the manual's answers without grasping why a particular test applies, you will struggle with any problem that shifts the scenario slightly. That happens constantly on midterms and finals. The manual also does not cover software implementation. Most courses now require Stata, R, or EViews output as part of the exercise set. The solution manual gives the theoretical and numerical answers, but it rarely walks through the commands. You will need to supplement it with course notes, tutorial sheets, or practice sessions in the lab. This gap is consistent across all editions I have reviewed.
A Practical Routine That Works
Work the problem on paper first. Attempt the full derivation and calculation. Check your final answer against the manual. If you disagree, trace your steps and find the divergence point. If the manual skips an algebraic step, fill it in yourself. Then write a two-sentence interpretation in plain language. Repeat this cycle for at least three problems per chapter before moving on. This routine takes longer than skimming solutions, but it produces a durable understanding that lasts through the exam period. The alternative is short-term familiarity that evaporates within a week. The manual is a tool, not a shortcut. Used correctly, it cuts review time significantly and clarifies where your reasoning went wrong. Used carelessly, it creates the illusion of competence that collapses under any modified question. The difference is whether you engage with the steps or just read the destination.