AP Macro Unit 4 Financial Sector — What Actually Shows Up
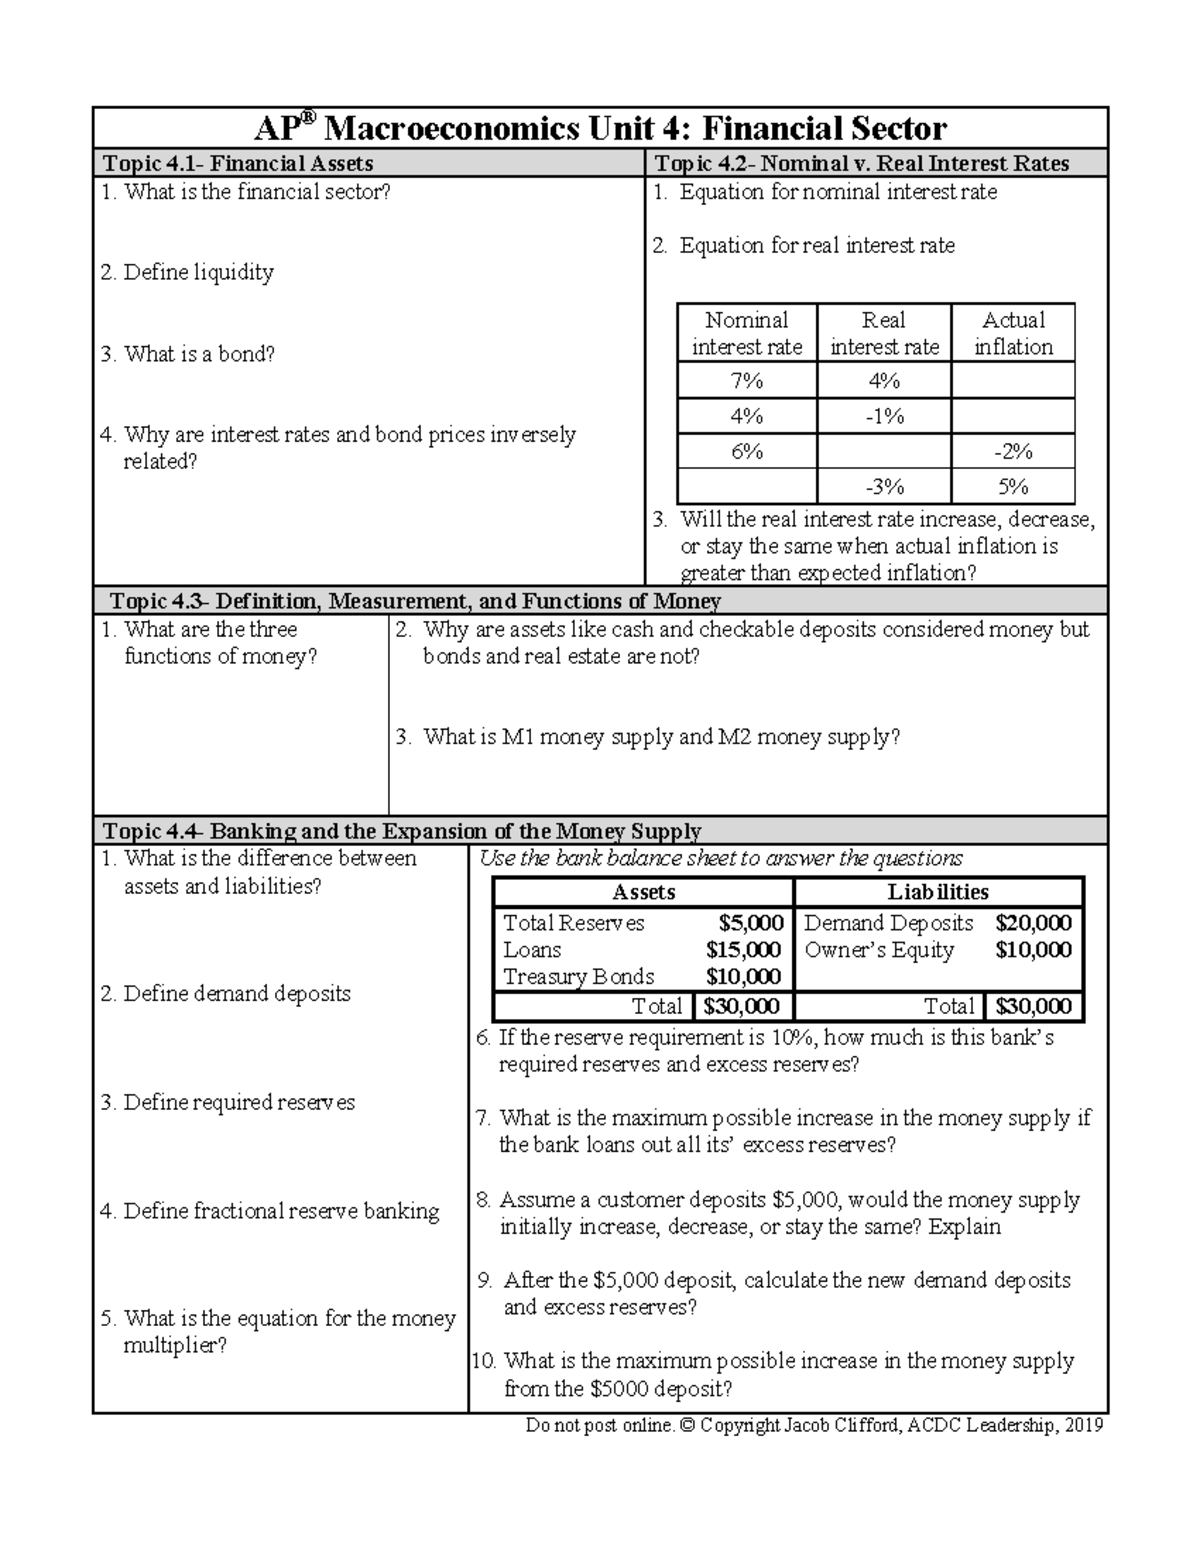
The financial sector unit is one of those sections where students can either coast or get immediately lost. It depends on whether you understand how money creation actually works or whether you just memorized a list of definitions. The AP exam does not reward memorization here. It rewards the ability to trace the flow of money through banks, reserves, and the Fed. Most of the questions in this unit revolve around three things: the money multiplier, the Fed's three tools (open market operations, discount rate, reserve requirement), and how changes in monetary policy ripple into aggregate demand. If you can diagram the chain of events—Fed buys bonds bank reserves rise lending capacity expands money supply grows interest rates fall investment rises AD shifts right—then you are already ahead of half the class.
Where the Ap Macroeconomics Unit 4 Financial Sector Answer Key Helps
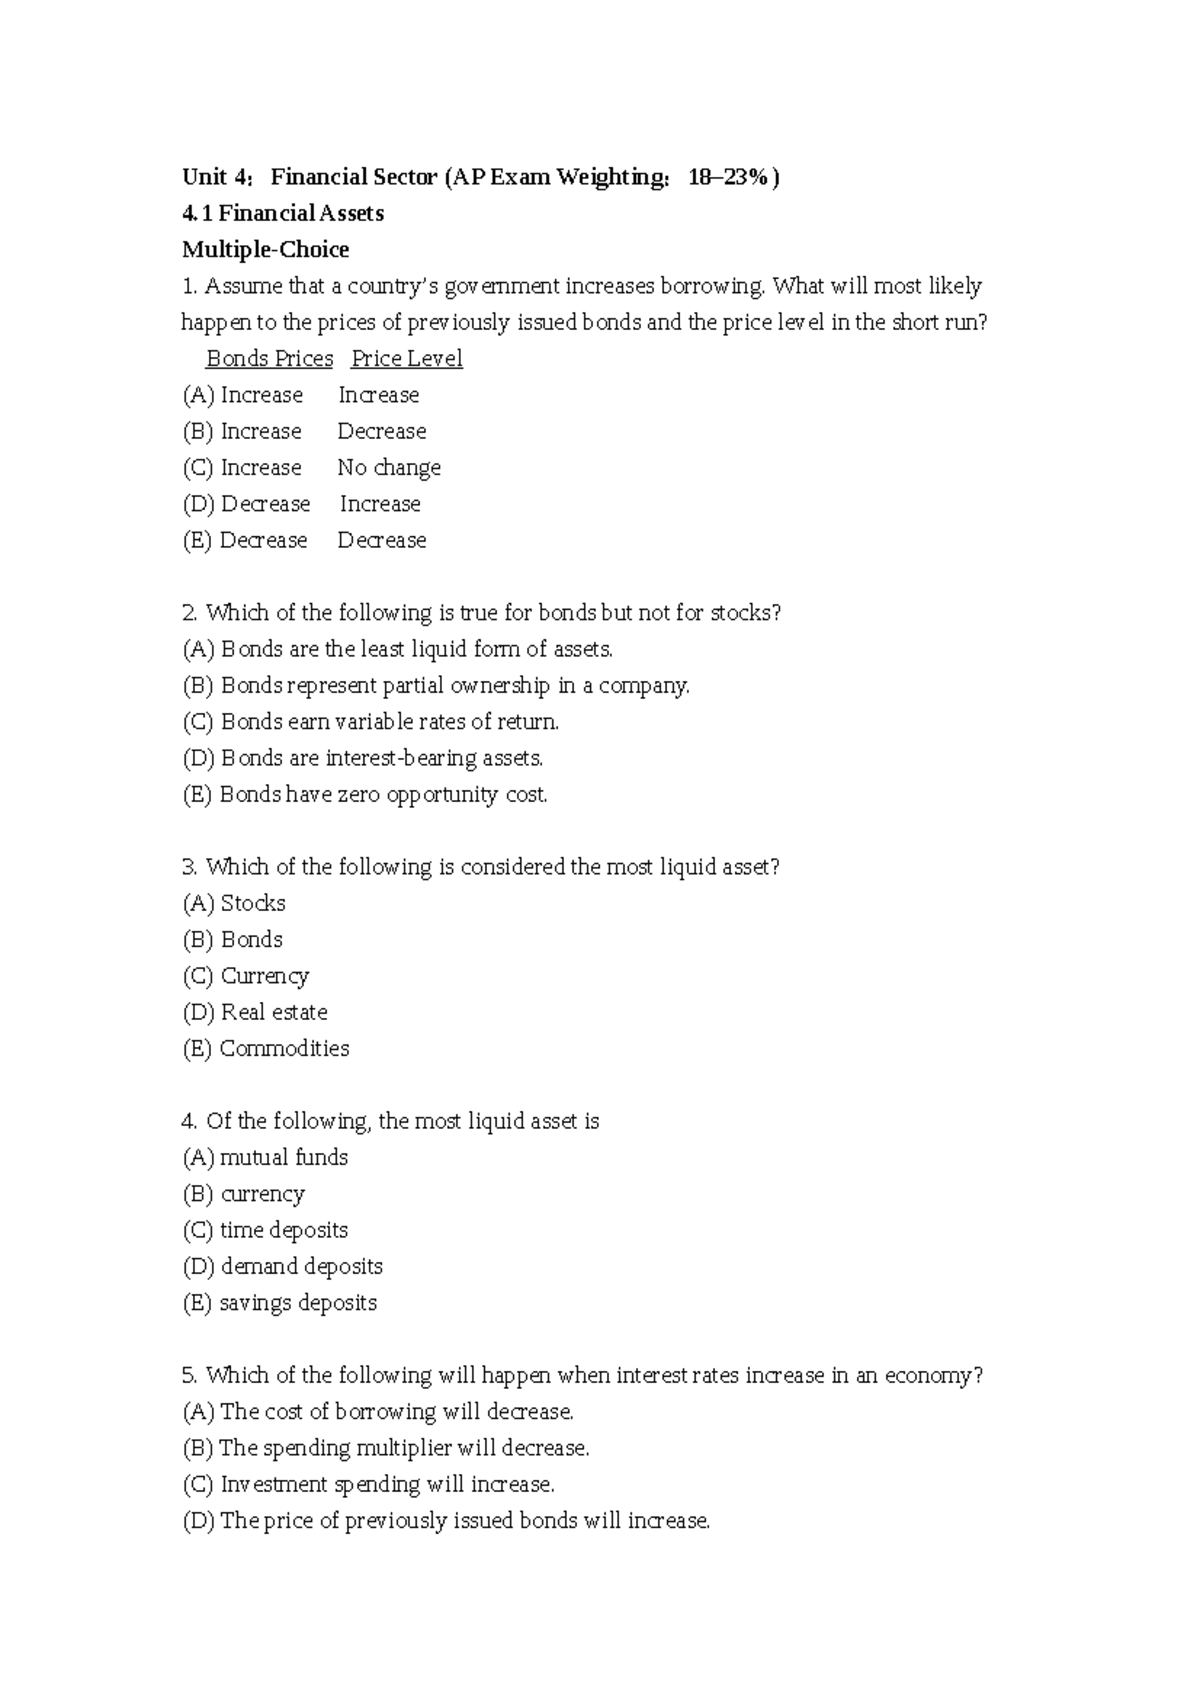
I used the answer key not to memorize answers but to reverse-engineer the College Board's logic. The key tells you which mechanism the question is testing. Sometimes it's straightforward. Sometimes it's a trick question disguised as a straightforward one. The key exposed that pattern for me. Here is a practical scenario I ran into while using answer keys from a previous year. There was a question that showed the Fed conducting an open market sale and then asked what happens to the money supply, interest rates, and GDP. The answer key said money supply decreases, interest rates increase, and GDP decreases. But the tricky part was a follow-up interpretation question that described a scenario where banks were holding excess reserves due to a recessionary fear. In that case, the standard multiplier model breaks down. The answer key didn't cover that edge case, so I had to reason through it myself. The workaround was to remember that if banks hold excess reserves, the actual money multiplier shrinks, which means the Fed's open market sale has a smaller contractionary effect than the textbook formula suggests. That specific nuance never appeared in the main key, but it showed up on the free-response section a few years later. That is the real value of working through these keys. You start seeing where the standard model fails and where the exam expects you to adjust your thinking.
How the Money Multiplier Actually Works (And Where Students Mess Up)
The money multiplier is calculated as 1 divided by the reserve requirement. So if the reserve requirement is 20 percent, the multiplier is 5. That means every dollar of new reserves can theoretically create five dollars of money supply. This is a theoretical maximum. Real life is messier. Banks might not lend out all their excess reserves, and people might hold more cash than they normally would. Both of these behaviors reduce the effective multiplier. A common pitfall on the exam is confusing the change in reserves with the change in the money supply. If the Fed buys $10 billion in bonds, the initial increase in bank reserves is $10 billion. But the total change in the money supply is $10 billion times the multiplier. Students often stop at $10 billion and pick the wrong answer. Another trap is mixing up the reserve requirement with the excess reserve ratio. The formula only uses the required reserve ratio unless the question gives you additional information about how much banks choose to hold in excess.
Get the Full Details

Fed Tools and Their Directional Effects
There are three main monetary policy tools. Open market operations involve the Fed buying or selling government securities. When the Fed buys bonds, it injects reserves into the banking system. When it sells bonds, it drains reserves. This is the most frequently used tool because it is flexible and precise. The discount rate is the interest rate the Fed charges commercial banks for short-term loans. Lowering the discount rate encourages banks to borrow from the Fed, which increases their reserves and lending capacity. Raising it has the opposite effect. This tool is less commonly adjusted because frequent changes signal instability. The Fed prefers to signal policy through open market operations instead. The reserve requirement is the fraction of deposits that banks must hold as reserves and cannot lend out. Lowering the reserve requirement increases the money multiplier and expands lending. Raising it contracts lending. This is the bluntest tool and the least frequently changed. The last time the Fed adjusted the reserve requirement was in 2020, when it was cut to zero during the pandemic to ensure banks had maximum lending capacity.
The directional chain is worth memorizing in both expansionary and contractionary forms. Expansionary: Fed buys bonds, discount rate falls, reserve requirement falls, money supply rises, interest rates fall, investment rises, AD shifts right, GDP rises. Contractionary is the exact opposite at every step.
Free-Response Questions and Common Scoring Patterns
The FRQ section in this unit typically asks students to illustrate a Fed action on a money market graph and then trace the effect on aggregate demand. The money market graph shows the money supply curve shifting right for expansionary policy or left for contractionary policy. The equilibrium interest rate moves accordingly. Then the AD-AS graph shows AD shifting right or left based on the change in investment spending. One thing that catches students off guard is that the exam sometimes asks you to account for the liquidity trap. This happens when interest rates are already near zero and further increases in the money supply do not lower rates any further. In that scenario, the transmission mechanism breaks. Monetary policy becomes ineffective. I encountered a practice FRQ that presented a liquidity trap and asked what the Fed should do instead. The answer key pointed toward fiscal policy as the alternative, since monetary policy loses traction at the zero lower bound. That is a nuanced point that rarely gets taught thoroughly in introductory courses but appears on the exam with reasonable frequency. Another scoring nuance is that the exam sometimes includes a diagram question where you must label axes, curves, and equilibrium points correctly. Missing labels costs points even if the direction of the shift is correct. I learned this the hard way after losing two points on a practice exam simply because I labeled the curves but forgot to label the axes as "Price Level" and "Real GDP."

Limits of This Unit and What the Answer Keys Don't Cover
The answer keys are useful but they have blind spots. They rarely explain the conditions under which the standard multiplier model fails. They do not cover the nuances of the Federal Reserve's balance sheet operations, like quantitative easing, which goes beyond the basic open market operation framework. They also skip over the international dimension of monetary policy, such as how changes in U.S. interest rates affect the exchange rate and net exports. These topics appear on the exam occasionally, and if you only rely on the standard answer key explanations, you may find yourself unprepared for those questions. The best approach is to use the answer key as a starting point. Work through every question, check your reasoning against the key, and then ask yourself what assumptions the key's explanation is built on. When those assumptions break down—excess reserves, liquidity traps, currency substitution—that is where the harder questions live.
Practical Study Sequence
Start by drawing the money market graph from memory. Shift the money supply curve, identify the new interest rate, and write out the chain of effects on investment and aggregate demand. Do this for both expansionary and contractionary policy until you can do it without looking. Then move to the Fed tools and make a table with the tool, the action, the direction of change, and the final effect on GDP. Fill in both sides of the table. After that, work through the answer key questions but do not just check whether you got the right letter. For every question you get wrong, write out the full causal chain in your own words. The goal is not to match the key's answer but to understand why the key's answer is correct. That habit of unpacking the mechanism is what separates students who score a 4 or 5 from those who stall at a 3. One final note. The AP exam occasionally includes questions about the federal funds rate, which is the interest rate banks charge each other for overnight loans. The Fed sets a target for this rate and uses open market operations to keep it within the target range. Understanding the relationship between the federal funds rate and the broader interest rate environment helps with questions that ask about the cost of borrowing across the economy, not just in the interbank market.