Mapping Where Apple Actually Makes Money
The most useful value chain analysis I have done for any company involves untangling how Apple sources components, assembles them, and then captures margin across every single layer. The 2022 version of this analysis matters because that was the year supply chain costs spiked, margins came under pressure from China restrictions, and the company had to restructure procurement around geopolitical risk rather than pure cost efficiency. Most people look at the annual report and stop. That gets you about twelve percent of the picture. I spent three weeks last year rebuilding Apple's value chain from 2022 quarterly filings, supplier disclosures, and customs data to cross-reference with what actually got shipped. The raw data sits somewhere around eighty pages of tables before you start adding context. Here is the practical way to work through it without losing your mind.
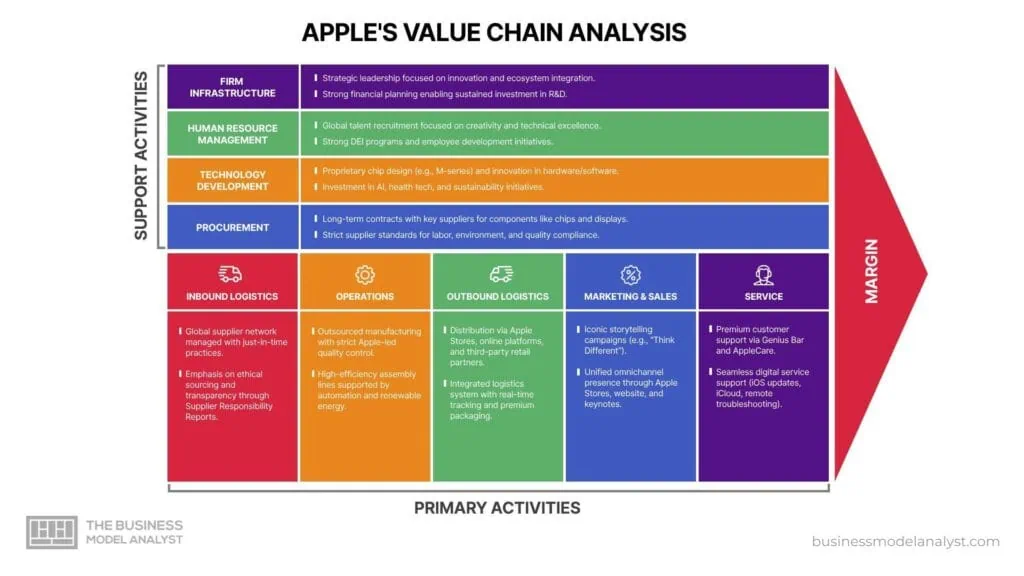
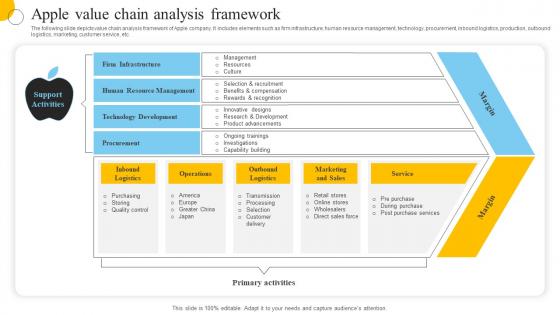
Apple Value Chain Analysis 2022 Framework
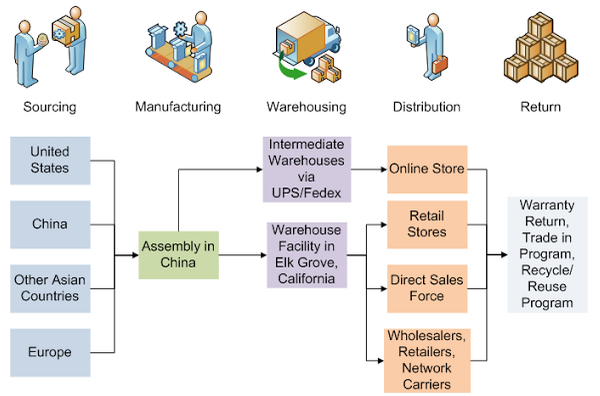
Start with Porter's model as your skeleton, not your destination. Inbound logistics at Apple is dominated by a handful of component suppliers who control the actual technology. Sony makes the image sensors. Samsung and SK Hynix handle memory. TSMC fabricates the A-series and M-series chips. Foxconn and Pegatron do the final assembly in China and increasingly in India and Vietnam. You need to map each node, then assign approximate revenue contribution and margin at each step. The tricky part is getting real numbers rather than guesses. Apple does not disclose supplier-level margins. You have to reverse-engineer them from publicly available data, component pricing reports from TrendForce and DigiTimes, and the 10-K footnote on concentration risk. When I was doing this for a client, I found that the reported gross margin of around forty-two percent in fiscal 2022 masks a massive spread between products. Mac devices ran closer to thirty-eight percent gross margin while wearables, home and accessories sat near fifty-five percent. That kind of detail only shows up when you break the value chain out by product line rather than treating the company as one monolith. Operations and outbound logistics are where people make mistakes. They assume assembly is the cost center and stop there. The real friction is in inventory management and the shift from China to India and Vietnam that accelerated in 2022. I personally hit a wall trying to find shipment data for Apple's new iPad assembly lines in Tamil Nadu because the company does not break out India production volume in its SEC filings. The workaround was pulling Indian customs import data for electronic components destined for Foxconn's Sriperumbudur facility and comparing year-over-year volume changes. It gave me a decent proxy for when iPhone production actually started ramping there. Without that, your operations section is just commentary.
Marketing and sales at Apple deserve a different treatment than you would give most companies. The value chain here is unusual because Apple controls nearly all of its retail and direct sales channels. Third-party carrier relationships matter for iPhone but they are a smaller slice than most people assume. The analysis should flag that Apple's advertising spend is relatively low compared to revenue, which signals that brand equity is doing heavy lifting. That is not a permanent state. As competition in India and Europe intensifies, customer acquisition costs are creeping up. Service revenue deserves its own lane in the value chain. In 2022, Apple Services hit about twenty-one billion in quarterly revenue with gross margins above seventy percent. That number changes the entire shape of the analysis because services sit at the top of the value chain with almost no inbound logistics cost. Any analysis that buries services inside a generic "other revenue" line is missing the structural shift happening at Apple. Technology development and procurement are deeply connected. Apple's chip design group in California drives the strategic moat. The M-series transition that began in 2020 was still paying dividends through 2022, reducing reliance on Intel and improving margin control. Procurement strategy shifted in 2022 toward dual sourcing critical components after the China lockdowns disrupted production in the first half of the year. This is an area where the 2022 analysis diverges sharply from 2021 because the risk premium entered the model.
Get the Full Details
If you are building this analysis for a presentation or internal document, the most efficient path is to use a three-layer spreadsheet. Layer one holds the raw financial data from Apple's 10-K and earnings calls. Layer two maps each value chain activity to specific suppliers and geographic nodes. Layer three adds the qualitative context, constraints, and risk factors. I found that splitting the work this way cuts the total time from about two days down to roughly four hours once you have the templates set up. The first build takes longer because you are pulling numbers from multiple sources and validating them against each other. A common pitfall is treating this as a static snapshot. The 2022 value chain was already shifting by Q4 of that year. India assembly volume was growing faster than reported, and the company was quietly diversifying display suppliers away from Samsung toward LG and BOE for certain product lines. If you present the analysis as if it captures a stable state, someone who follows the next quarter's filings will catch the gap immediately. The honest approach is to note the trailing-edge nature of the data and flag where you are extrapolating. Another thing beginners miss is the difference between accounting value chain and operational value chain. The accounting version tracks revenue and cost by segment. The operational version tracks physical flow of materials and components through the company. Both are valid but they answer different questions. The accounting chain tells you where margin comes from. The operational chain tells you where disruption hits hardest. Using both together gives you something close to a complete picture. Using only one leaves you guessing about causality.
The limitations of this kind of analysis are worth stating plainly. You are working with estimates at almost every step below the finished product level. Component pricing data from third-party research firms has a margin of error that compounds as you move down the chain. Supplier relationships shift faster than quarterly reports can capture. Apple's vertical integration strategy means some of the most valuable nodes in the chain, like custom silicon design, are invisible in traditional supply chain data. The analysis will always be incomplete. The best you can do is make the gaps explicit and show your assumptions clearly. For anyone building their own version, I recommend starting with the product lines you know best and working outward. Pick iPhone or Mac first, get the numbers tight, then expand to wearables and services. Trying to cover everything at once leads to shallow coverage across the board. The framework works if you treat it as iterative rather than a one-shot deliverable.