When Math Actually Pays For Itself
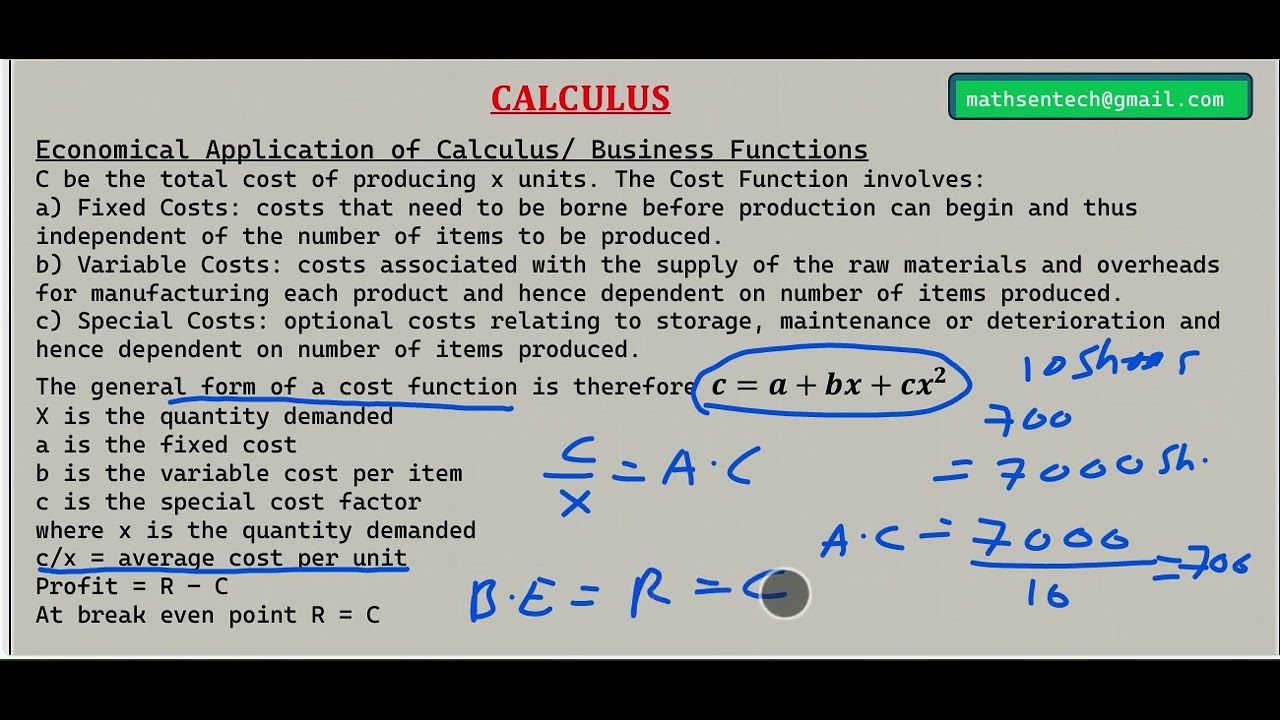
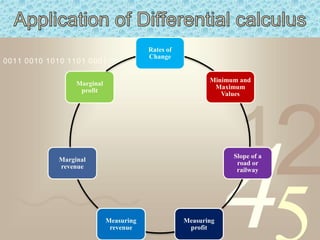
I was three years into running financial models for a mid-size manufacturing firm when I realized most people treat calculus like it lives only in college textbooks. They do not. It shows up when you are trying to figure out whether producing one more unit will actually make you money or bleed you dry. That is not abstract. That is someone's paycheck. The core idea is simple enough that it sounds boring until you try to use it. Marginal cost, marginal revenue, marginal profit. These are just derivatives, which means they measure how a function changes at a single point. If your total cost function is C(x), then C'(x) tells you what it costs to produce one additional unit when you are already making x units. That is it. The entire framework is built on that single concept repeated across revenue, profit, and elasticity. I used to watch analysts plug numbers into spreadsheets and guess at optimal production levels. They would test x equals 100, then 150, then 200, and pick whichever looked best. This takes hours and still misses the actual optimum. Using the derivative approach, you set the marginal revenue equal to the marginal cost and solve for x. One equation. Usually under five minutes if your cost and revenue functions are properly specified. It replaced what was a two-hour iterative process with a fifteen-minute calculation.
The tricky part is getting the functions right. A linear cost function will lie to you. Real cost structures have economies of scale at low volumes, then diseconomies as you push capacity. You need piecewise or polynomial cost functions, and you need data that actually reflects those turning points. I learned this the hard way when a client handed me a cost table that looked perfectly straight across five production levels. The derivative said optimal output was near infinity. It was not. The data simply did not cover the region where costs started climbing again. We ended up fitting a cubic cost function to monthly overhead reports over eighteen months, which captured the U-shape properly. The optimal quantity dropped from "produce everything" to a concrete 847 units per month. That made a real difference on the floor.
Revenue Optimization And Price Elasticity
Revenue is usually R(x) equals price times quantity. If price depends on quantity sold through a demand curve, then revenue becomes a function of one variable. Take the derivative, set it to zero, and you get the revenue-maximizing quantity. From there you can back out the corresponding price. The connection to elasticity is direct. When marginal revenue hits zero, demand is unit elastic. That means a one percent price change produces exactly a one percent quantity change in the opposite direction. Beyond that point, lowering price actually reduces total revenue because the volume gain does not compensate for the lower unit price. Most pricing teams I have worked with miss this. They cut prices whenever competition pressures them without checking whether they are operating on the inelastic portion of the demand curve. That is leaving money on the table, or worse, reducing revenue while still hurting margins. Here is something most business math courses skip. The relationship between marginal revenue and elasticity is R'(x) equals price times one minus one over absolute value of elasticity. This formula is useful because it lets you compute marginal revenue directly from observable market data without needing a perfectly estimated demand function. If you know the current price and you can estimate elasticity from historical sales variation, you already have marginal revenue. That is valuable in markets where demand curves shift frequently and fitting a stable function is unreliable.
Get the Full Details
Integration For Total Quantities
Derivatives give you rates of change. Integration does the reverse, and it shows up in business whenever you need a total from a flow. The most common use is finding total cost from marginal cost. If you know C'(x) for every production level and you know your fixed cost, then the definite integral of C'(x) from zero to your target quantity plus fixed cost gives you total cost. It is exact, not approximate, assuming your marginal cost function is correct. Consumer and producer surplus work the same way. The area between the demand curve and the equilibrium price, integrated over the quantity sold, gives consumer surplus. The area between the equilibrium price and the supply curve gives producer surplus. These are not just textbook exercises. I used consumer surplus estimates when advising a software company on subscription pricing. The model suggested they were pricing roughly thirty percent below what the market would bear for their enterprise tier. The numbers were not perfect, but they pointed in the right direction and justified a price test that ultimately lifted annual revenue by a measurable margin.
Where This Approach Breaks Down
Calculus-based optimization assumes you can write clean functions for cost and revenue. That assumption fails in several common business situations. First, discrete production environments where you cannot produce fractional units and your cost steps jump discretely. Derivatives smooth over those jumps, so the calculus answer can be off by a meaningful amount. Second, markets with network effects or switching costs where demand is not a smooth function of price. Third, any scenario where your cost structure changes abruptly due to contractual commitments, capacity constraints, or regulatory thresholds. When those conditions exist, numerical optimization is more reliable. You test candidate quantities directly using your actual cost and revenue data. It is slower but it does not pretend the world is smooth when it is not. I switched to numerical methods for a logistics client whose transportation costs jumped whenever shipments exceeded truck capacity. The derivative approach kept suggesting we push past truckloads to reach some theoretical optimum. The numerical approach showed the real cost cliff clearly and pointed to a different batch size that saved money without creating overflow problems. Another honest limitation is data quality. Calculus optimization is only as good as the functions you feed it. Garbage functions produce garbage optima, and they look convincing on paper. The best safeguard I found was running sensitivity analysis around the optimum. If moving the quantity by ten percent changes the result dramatically, the model is too fragile to trust. If the profit curve is flat near the top, then small errors in estimation do not matter much, and the calculus answer is close enough for practical purposes.
A Note On Tools
You do not need specialized software for basic calculus optimization. A spreadsheet with a proper cost function and the Solver add-in handles most problems. For higher-dimensional cases involving multiple products or resources, MATLAB, Python with SciPy, or even R works fine. The tool choice does not matter nearly as much as getting the function definitions right. If you are starting out, begin with a single product, a quadratic cost function, and a linear demand curve. Those assumptions are crude, but they let you see the mechanics without drowning in data problems. Once you are comfortable, layer in realism piece by piece. Adding complexity all at once is how models go wrong.