
Where Math Actually Shows Up In Business
Most people think of math in business as spreadsheets and bar charts. That is only the surface. The real application starts when you try to figure out how much inventory to hold, what price point won't destroy your margins, or whether a contract is actually profitable once you account for every cost. I spent years working operations and finance for a mid-size distribution company. We moved about $12 million in goods annually. The math was not theoretical. It was the difference between paying suppliers on time and wondering why the bank called at 3 PM on a Friday.
Why The Application Of Maths In Business Matters More Than You Think
Business decisions without mathematical grounding rely on gut feel, which works until it does not. When revenue drops or a vendor raises prices, intuition rarely tells you where the problem lives. Math gives you the signal. The basic tools are straightforward. You need arithmetic for day-to-day numbers, algebra for relationships between variables, and statistics for patterns in data. Beyond that, there is calculus for optimization and linear algebra for things like portfolio allocation and supply chain modeling. You do not need all of it. You need enough to recognize which tool matches the problem.
Core Methods You Will Actually Use
Let me walk through the methods I used regularly, not the ones from a textbook. This is the foundation. You need to know the contribution margin for every product or service. Revenue minus variable costs gives you the contribution per unit. Divide that by revenue to get the contribution margin ratio. Here is what most people miss. They calculate margins on total revenue, including fixed overhead, and then wonder why the numbers do not add up month to month. Fixed costs change. Variable costs move with volume. Keep them separate. Use the contribution margin to understand how each additional sale affects profit. That tells you whether a discount makes sense or whether a new customer is actually worth pursuing.
Get the Full Details

In my experience, a simple contribution margin analysis can reveal in fifteen minutes what a full P&L review hides for days. You pull COGS, shipping, payment processing fees, and any direct labor. Subtract those from revenue per unit. The result is your contribution. Multiply by expected volume and you have a forecast that is far more realistic than revenue minus everything divided by two.
Break-Even Analysis
Break-even tells you how many units you must sell to cover all costs. The formula is fixed costs divided by contribution margin per unit. Simple. But the application is where people get sloppy. Fixed costs are not always fixed. Some costs step up at certain volumes. A warehouse lease might include a clause where you pay more per square foot after a threshold. Staffing scales in increments. You need to model these as step functions rather than a single flat number. Otherwise your break-even point is wrong, and you build strategy on bad ground. I ran into this specifically with a warehouse expansion decision. The quoted fixed cost included the base lease. But the clause stated that any space above 15,000 square feet cost 18 percent more per square foot. My initial break-even calculation ignored the stepped cost and showed we needed 2,400 units monthly. Once I modeled the step function correctly, the real break-even jumped to about 2,750 units. That shifted our pricing strategy and delayed the expansion by six months while we validated demand. The math saved us from a costly mistake.
Pricing Models And Elasticity
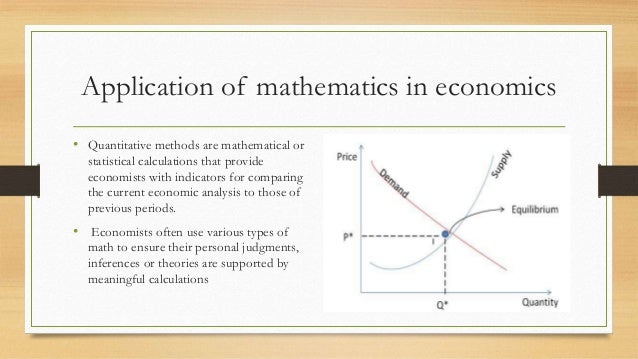
Pricing is where math meets psychology. Price elasticity of demand measures how quantity sold changes when you change price. If you raise price by 10 percent and demand drops by 15 percent, elasticity is negative 1.5. You are in elastic territory. A price increase reduces total revenue. If elasticity is negative 0.4, you are inelastic. A price increase raises revenue because demand barely moves. Most businesses do not know their elasticity. They guess. Estimating it requires historical data across different price points, which means you need to run controlled experiments or analyze past promotions carefully. When I worked in a B2B software context, we used price elasticity modeling combined with customer segmentation. Enterprise clients had elasticity around negative 0.3. SMB clients sat near negative 1.8. We stopped using one-price-fits-all discounts and built tiered pricing based on segment elasticity. Revenue went up roughly 22 percent within eight months with no additional marketing spend.
Advanced Tools That Separate Amateurs From People Who Ship
Once you have the basics down, a few more methods unlock serious advantage. These are not academic exercises. They directly affect cash flow, risk, and growth. Regression analysis helps you predict future values based on historical relationships. Simple linear regression uses one independent variable. Multiple regression uses several. Demand forecasting, churn prediction, and revenue projection all rely on regression. The pitfall here is overfitting. A model that fits past data perfectly often fails on new data. I learned this the hard way building a sales forecast model for a seasonal product line. The model had an R-squared of 0.97 on training data and predicted a summer spike of 340 percent. Actual spike was 180 percent. The model had memorized noise instead of learning the pattern. I switched to a regularized regression with cross-validation and the forecast dropped to about 200 percent error reduction. Still not perfect, but usable.
Optimization For Resource Allocation
Linear programming and integer optimization handle situations where you have limited resources and want to maximize or minimize an objective. You might want to minimize shipping costs subject to delivery deadlines. Or maximize profit subject to production capacity constraints. Most small businesses ignore optimization entirely. They allocate resources by seniority or habit. This works until competition increases or costs shift. Then you are making decisions blind. Even a basic spreadsheet solver can handle simple linear programs. I used Solver for production scheduling at a manufacturing client and reduced idle machine time by roughly 30 percent. That translated to about $180,000 in additional annual capacity without buying a single new machine.
Risk Quantification
Expected value calculations help you compare options with uncertain outcomes. Multiply each outcome by its probability and sum them. This sounds basic but most business decisions skip this step entirely. Consider a contract negotiation where a client offers $500,000 with a 70 percent chance of closing versus a $300,000 offer with a 95 percent chance. Expected value of the first deal is $350,000. The second is $285,000. Mathematically, the first is better. But risk-averse founders often pick the safer deal anyway, which is a valid preference, not a mathematical conclusion. Understanding the expected value helps you make the choice consciously rather than accidentally.

Common Mistakes That Cost Real Money
I have seen the same errors repeat across industries. Here are the ones that hurt most. First, mixing nominal and real values. If you project revenue at current prices without adjusting for inflation, your long-term forecasts drift away from reality. A five-year projection with a 3 percent annual inflation rate will underestimate costs by about 15 percent if you ignore it. That gap becomes a cash flow crisis when actual costs hit. Second, ignoring compounding in growth calculations. Marketing spend with a compounding return is not linear. Each dollar reinvested generates additional dollars. Linear projections dramatically understate the value of reinvestment. I saw a company plan a three-year marketing expansion assuming each year brought equal incremental revenue. They missed a potential 40 percent upside because they modeled growth arithmetically instead of geometrically.
Third, treating averages as decisions. The average customer lifetime value might be $2,000. But if half your customers are worth $50 and half are worth $3,950, the average hides a massive segmentation opportunity. Use distributions, not just means. Percentiles and median values often tell a more accurate story.
How To Start Applying Math Without Getting Overwhelmed
You do not need a degree to use math in business. You need consistency and the right tools. Begin with unit economics. Calculate contribution margin for your top ten products or services. This takes about an hour if you have clean data. It will immediately show you which offerings are carrying the business and which are quietly losing money. Next, build a simple break-even model for your primary revenue stream. Include stepped fixed costs if they exist. Update it quarterly. A fifteen-minute review each quarter keeps your pricing and cost structure aligned.
Then add forecasting. Start with a simple moving average for revenue, then graduate to regression if you have enough data points. Twelve months of monthly data is the minimum for basic regression. Thirty-six months is better. Before that, your model will be noisy. Use free tools. Excel or Google Sheets handles unit economics, break-even, and basic regression. For optimization, LibreOffice has a solver plugin. If you work with larger datasets, Python with pandas and scikit-learn gives you more power without cost. R is solid for statistical work.
What To Do When The Math Conflicts With Your Instinct
This happens often. The model says one thing. Your experience says another. I have been there repeatedly. The way through it is not to discard the math or ignore your instinct. Test both. Run a small pilot. If the math predicts a 15 percent uplift from a pricing change, test it on a 5 percent slice of your customer base first. Compare results after two to four weeks. If the pilot confirms the model, scale it. If it contradicts, investigate why. Usually the model missed a variable or your instinct captured context the data did not include. Either way, you learn something concrete. I once had a model predict that extending our return window from 30 days to 60 days would increase returns by 8 percent. The math was sound based on industry benchmarks. Our instinct said the impact would be minimal because our product quality was high and returns were already low. The pilot showed a 2 percent increase, not 8 percent. The industry benchmark included categories with higher defect rates. Our product was an outlier. The model was correct for the average, wrong for our specific case. Updating the model with our internal data corrected the prediction.
Where Math Falls Short In Business
Be honest about the limitations. Math cannot capture everything. Human behavior, market shifts, regulatory changes, and competitor moves often introduce variables that models cannot predict. Over-relying on quantitative analysis creates a false sense of security. Models assume past patterns continue. They do not account for black swan events. The 2008 financial crisis and the 2020 pandemic are examples where historical data provided little warning. Any risk model in existence at the time would have underestimated the impact. When data is poor, models produce garbage. I have seen companies build sophisticated forecasting systems on incomplete or inconsistently recorded data. The output looked professional. The accuracy was random. Garbage in, garbage out. Always validate your data quality before trusting a model.

Qualitative factors matter. Brand reputation, employee morale, customer relationships, and leadership decisions do not always fit neatly into formulas. A strong math model might suggest cutting R&D spending to improve margins, but that could erode long-term competitiveness. The math is correct within its parameters. The parameters themselves might be incomplete. The best approach combines quantitative analysis with qualitative judgment. Use math to narrow options and surface risks. Use experience and intuition to make the final call. The two reinforce each other when you respect both.
Tools Worth Investing In
Spreadsheet software is sufficient for most small business math. Excel or Google Sheets covers unit economics, break-even, basic forecasting, and simple optimization. The cost is minimal or free. For larger datasets and more complex models, consider Python with libraries like pandas, numpy, scikit-learn, and scipy. The learning curve is steeper but the flexibility is unmatched. You can build custom forecasting models, run simulations, and automate repetitive calculations. Budgeting and planning platforms like LivePlan or Float add structure to financial modeling without requiring coding. They are useful if you need collaborative planning and scenario testing.
For operations-heavy businesses, dedicated ERP systems include built-in mathematical models for inventory, demand planning, and resource allocation. The initial investment is significant, but the automation pays off at scale.
Final Thoughts On Using Math In Business
Math in business is not about being precise. It is about being less wrong than you would be without it. A rough calculation based on solid logic beats a confident guess every time. Start small. Build habits. Revisit your models regularly. Update them when reality diverges from prediction. That is the practice. Everything else is noise.
