How Apr Calculators Actually Work for Mortgages
Most people think APR is just the interest rate plus some fees. It's close but not quite right, and the difference matters when you're comparing two loans that look identical on the surface. I've sat across from borrowers who picked the lower-rate loan only to discover six months later the APR was half a point higher, which translates into thousands over the life of the loan. An APR calculator for mortgages takes your loan amount, interest rate, term, and any prepaid finance charges, then converts everything into a single annualized number. The formula assumes the loan runs its full term. That assumption alone creates a lot of confusion because most people don't actually keep a mortgage for thirty years.
Apr Calculator Mortgage: What It Actually Outputs
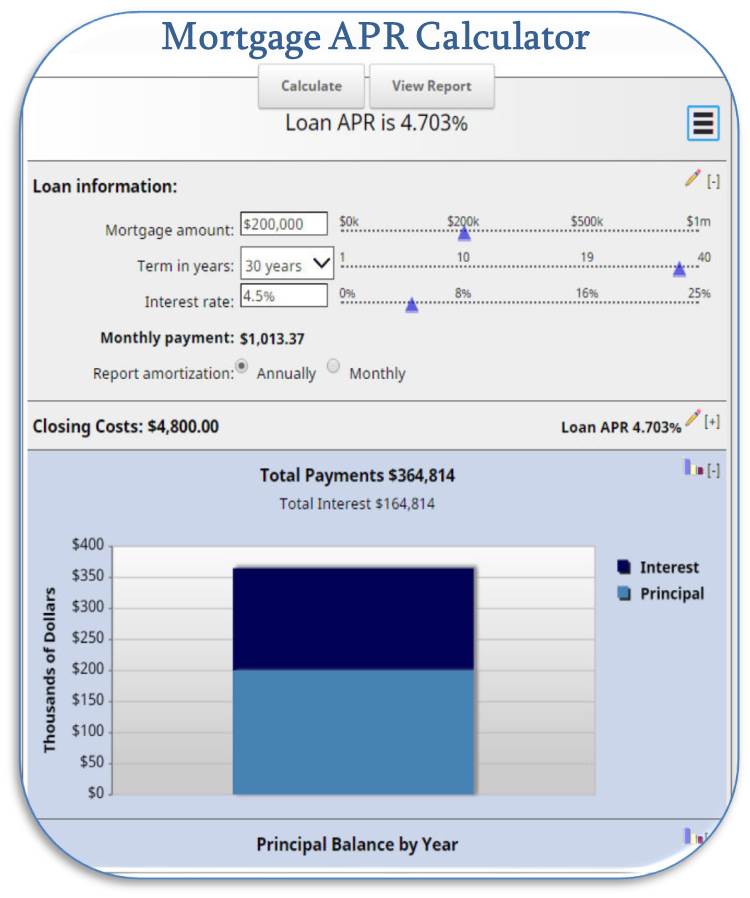
When you plug numbers into a solid Apr Calculator Mortgage tool, you get a percentage that's always higher than the note rate. The gap between those two numbers represents your prepaid costs spread across the loan balance over time. Points, origination fees, some closing costs, and mortgage insurance premiums all feed into that calculation. Broker fees if there are any, too. Here's what most calculators miss or handle poorly. They assume you pay those upfront costs at closing, but in reality some of them roll into the loan balance, which changes the math entirely. I ran into this exact problem when I was evaluating a VA loan where the funding fee was financed rather than paid out of pocket. The calculator showed an APR of 4.12 percent, but the real effective rate considering the funded fee was closer to 4.31. The workaround was simple: I recalculated manually by adding the funding fee to the principal and running a new amortization, which gave me the actual cost number instead of the advertised one. Another thing to watch for. Most free online calculators won't ask whether you're getting a rebate or lender credit. If the lender is giving you a thirty-five hundred dollar credit to offset closing costs, that credit actually lowers your APR, and cheap calculators ignore it entirely. The ones built to federal disclosure standards will include it, but you have to look carefully at what inputs they're asking for.
Steps to Use an Apr Calculator Mortgage Correctly
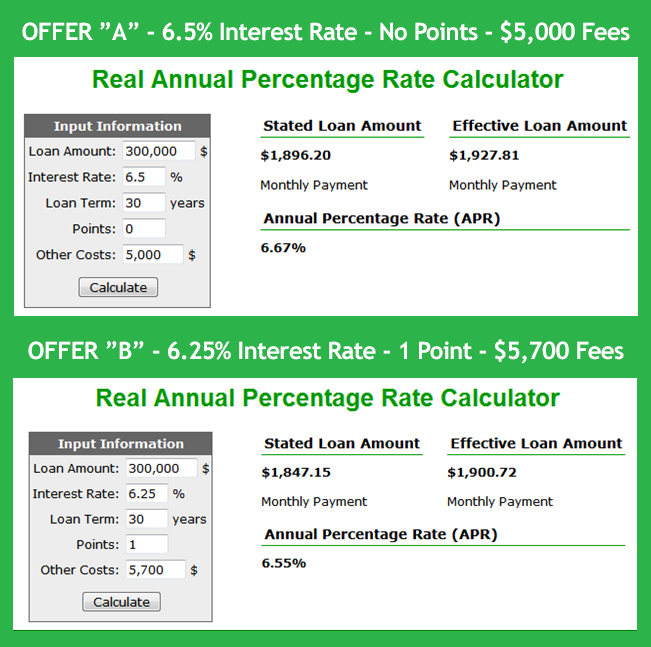
First, gather your Loan Estimate. The numbers you need are all on page one, specifically Box B for the interest rate, Box C for the loan amount, and the section listing origination charges, discount points, and other closing costs. Don't pull numbers from the approval letter or the marketing brochure. Those are rounded or outdated by the time you receive them. Enter the nominal rate exactly as it appears. Some calculators will let you input rate points separately, and you should. A loan at 6.75 percent with one discount point will show a different APR than a loan at 7 percent with zero points even though the monthly payment might be nearly identical. That comparison is exactly where the APR calculator earns its keep. Then add your prepaids. Property taxes, homeowner's insurance, and mortgage interest that you pay at closing don't count toward APR. Only the finance charges do. This trips up a lot of people because the Loan Estimate bundles everything together in the total closing cost line, but the APR calculation excludes those escrow items. If your calculator doesn't make this distinction clear, assume it's including things it shouldn't and the APR will be artificially high.
Get the Full Details
Some tools let you specify whether the loan will be paid off early. If you know you're going to sell or refinance in five years, run the calculation both ways. The standard APR assumes you hold the loan to maturity, so it spreads those upfront costs across thirty years and makes them look smaller. When you recalculate assuming a five-year payoff, those same costs get compressed into a much shorter period, and the effective rate jumps significantly. This is the number that actually matters to your wallet.
When APR Calculators Give You the Wrong Answer
They break down with adjustable-rate mortgages. An ARM's APR is partly a guess about what your rate will be in years four through twenty-nine. The regulator requires calculators to use a formula that assumes the initial teaser rate stays locked forever, which produces an APR that's wildly inaccurate for anything beyond the first adjustment period. I had a borrower last year comparing a 5/1 ARM at 6.25 percent against a thirty-year fixed at 6.875 percent. The calculator showed the ARM with a lower APR, which made it look like the better deal. After the first adjustment, her rate reset to index plus two points, which put her somewhere north of eight percent. The ARM turned out to be the more expensive option despite what the APR suggested. They also mislead on second mortgages and home equity lines. HELOCs don't have a meaningful APR calculation in the same way because draws and repayments happen continuously. Some calculators will still produce a number, but it's essentially decorative and shouldn't be used for comparison. The biggest blind spot is refundable origination fees. If you pay two points in fees and your application gets denied for a reason that triggers a fee refund clause in your contract, those two points never actually cost you anything. The calculator assumes they do. I've seen this matter in jumbo loan programs where lenders charge heavy upfront fees but include refund provisions if underwriting doesn't approve within a certain window. The effective APR in those cases can be half a percentage point lower than the calculator shows.
A Practical Walkthrough
Say you're looking at a $400,000 conventional loan at 6.5 percent over thirty years. Your Loan Estimate shows $6,200 in closing costs, $4,800 of which are finance charges. Points, origination, and underwriting fees make up the bulk of that. Plug those numbers into a reliable APR calculator. You'll get an APR around 6.78 percent. That's your baseline for comparison against other offers. If another lender quotes 6.625 percent with $7,100 in finance charges, their APR might actually come out to 6.91 percent despite the lower headline rate. That's the trap APR is designed to expose. Now run the same numbers with a five-year payoff assumption. The calculator should show a noticeably higher APR because those $4,800 in finance charges are being amortized over sixty months instead of three hundred sixty. In this example it would push the APR up roughly eight to ten basis points depending on the tool you're using. That adjustment tells you which loan is actually cheaper if you're not staying in the house for the long haul.
If you want something you can actually use rather than clicking through yet another web form, the most reliable approach I've found is building a simple spreadsheet with the amortization function built in. You set the monthly payment using the note rate and principal, then solve for the rate that produces the same payment when you subtract the finance charges from the loan amount upfront. It takes about fifteen minutes to set up and then you can run every scenario you want without feeding your financial data into random websites. I maintain one of these for my own reference and share it with clients who want to cross-check what the calculators are giving them.