The mechanics behind pairing spreads and holding through volatility
Most people think spread trading is just buying one thing and selling another identical thing. That's not what works. The actual edge comes from finding two correlated assets where the price relationship has drifted apart temporarily, then holding until mean reversion happens. This is where Arbitrage Swing Trading exists—somewhere between pure statistical arbitrage and directional swing positioning. You're not capturing instant risk-free profits. You're taking a calculated bet that the spread between two assets will converge over several days to weeks. The instruments you actually use matter more than the math. Futures on commodity pairs, ETFs in the same sector, or crypto perpetual swaps with funding rate differentials. I traded copper-zinc spreads on the COMEX for about eighteen months before writing it off. The problem wasn't the model. It was that exchange latency plus your broker's execution slippage ate every theoretical edge on trades under four hours. When I extended holding periods to three to ten days, the economics flipped positive. That duration extension is what separates real spread trading from fantasy.
Setting up the spread instrument
You need a reliable correlation metric first. Rolling 60-day Pearson correlation on daily closes works for most liquid pairs. But correlation alone is useless without understanding the cointegration test. A high correlation can persist while the spread drifts permanently apart. Augmented Dickey-Fuller tests on the residual series tell you whether the spread is stationary. Run it yourself. The backtesting frameworks in most retail platforms skip this step because the code is nontrivial. Once you confirm cointegration, calculate the z-score of the spread. Subtract the rolling mean, divide by the rolling standard deviation. Entry triggers sit around z-score of 2.0 or higher. Exit at zero or when the score crosses into negative territory on the opposite side. Simple formula, painful execution.
What actually kills spread returns in practice
Funding rates on perpetual swaps. Margin calls on one leg. Corporate actions like splits or dividends that silently break your hedge ratio. I learned about the dividend problem the hard way in early 2023. I was long SPY and short QQQ, running a clean mean-reversion model. QQQ dropped its distribution without adjusting my position size. The spread moved against me by 4.2% in a single session. No warning indicator in my dashboard caught it. I had to manually unwind both legs and eat a $3,800 loss on a trade that was technically working until that event. After that, I added a corporate action calendar screen to my workflow. Dividend dates, ex-dates, spinoffs, and reverse splits get flagged two weeks ahead. This cuts unexpected drawdowns from corporate events by roughly 70%. Not perfect, but it keeps you from getting blindsided repeatedly.
Get the Full Details

The hidden cost nobody talks about
Borrow costs on short legs. When you short the outperforming asset in your spread, you're not just paying a fee. You're competing for share availability. In thinly traded markets or during short squeezes, borrow rates spike to 20% annualized or higher. That directly reduces your net spread return. Factor this into your entry criteria. If the theoretical spread advantage is less than 1.5% annualized after borrow costs, skip the trade. Another subtle issue: regime shifts. Cointegration breaks during high-volatility macro events. Fed announcements, earnings seasons, geopolitical shocks—all of these can decouple historically linked assets for weeks or months. During the March 2020 crash, energy sector spreads that had been mean-reverting for years diverged beyond all statistical significance. Anyone holding those positions through the initial selloff got liquidated. The workaround is to reduce position size by half whenever VIX spikes above 35, and to check your core correlation assumption every month instead of setting it and forgetting it.
Execution timing matters more than entry timing
Spread entries need to happen in batches, not all at once. If you're trading futures, queue orders on both legs simultaneously. If you're using equities, stagger your entries across five-minute intervals to minimize market impact. I use a simple TWAP algorithm that splits each leg order into three tranches over fifteen minutes. This usually cuts slippage from about 0.12% per leg down to roughly 0.04%, depending on liquidity. Exit execution is where most retail traders fail. They stare at the z-score crossing zero and hesitate. By the time they click sell, the spread has moved 0.3 standard deviations in their favor. Set limit orders at your target exit before you enter. Automated execution removes the emotional delay. The trade loses its edge the moment the thesis plays out, so speed matters.
Position sizing under correlation uncertainty
Don't size based on account percentage alone. Size based on spread volatility. Calculate the annualized volatility of your residual series, then set position size so that one standard deviation move equals 2% to 3% of your account equity. This approach normalizes risk across different spread pairs regardless of their individual asset volatility. A copper-zinc spread and a tech-ETF pair can carry the same risk weight using this method. The formula looks like this: position size equals target risk divided by the product of contract multiplier and spread volatility. You'll need historical spread data to compute the denominator. Most brokers provide this through their API, or you can pull it from Bloomberg terminals if your firm has access.
When arbitrage swing trading fails completely
Cryptocurrency basis trades. Yes, they look attractive because funding rates and spot-futures spreads are wider. But exchange counterparty risk is real. When FTX collapsed in November 2022, traders with open arb positions lost everything overnight. The spread never converged because the exchange halted withdrawals. This isn't theoretical. It happened to people I know. Another failure mode: structural breaks in the underlying relationship. Airlines and oil spreads made sense for decades. Then COVID happened. Demand collapsed, supply chains broke, and the correlation turned negative for about fourteen months. Anyone holding long-haul airline futures against crude stayed underwater until the spread reset to a new regime. The lesson is to monitor your cointegration statistics weekly during volatile periods, and to cut the trade if the ADF p-value rises above 0.10 for more than five consecutive days. There are also capacity constraints. Once a spread becomes widely recognized, other participants trade it until the edge disappears. The copper-zinc space I mentioned earlier had maybe three major funds running it profitably a few years ago. Now the available edge is tiny and requires institutional-grade infrastructure to capture. Retail traders should focus on less crowded spread relationships—maybe regional bank ETFs, or cross-sector pairs with loose but stable correlations.
A practical workflow that actually works
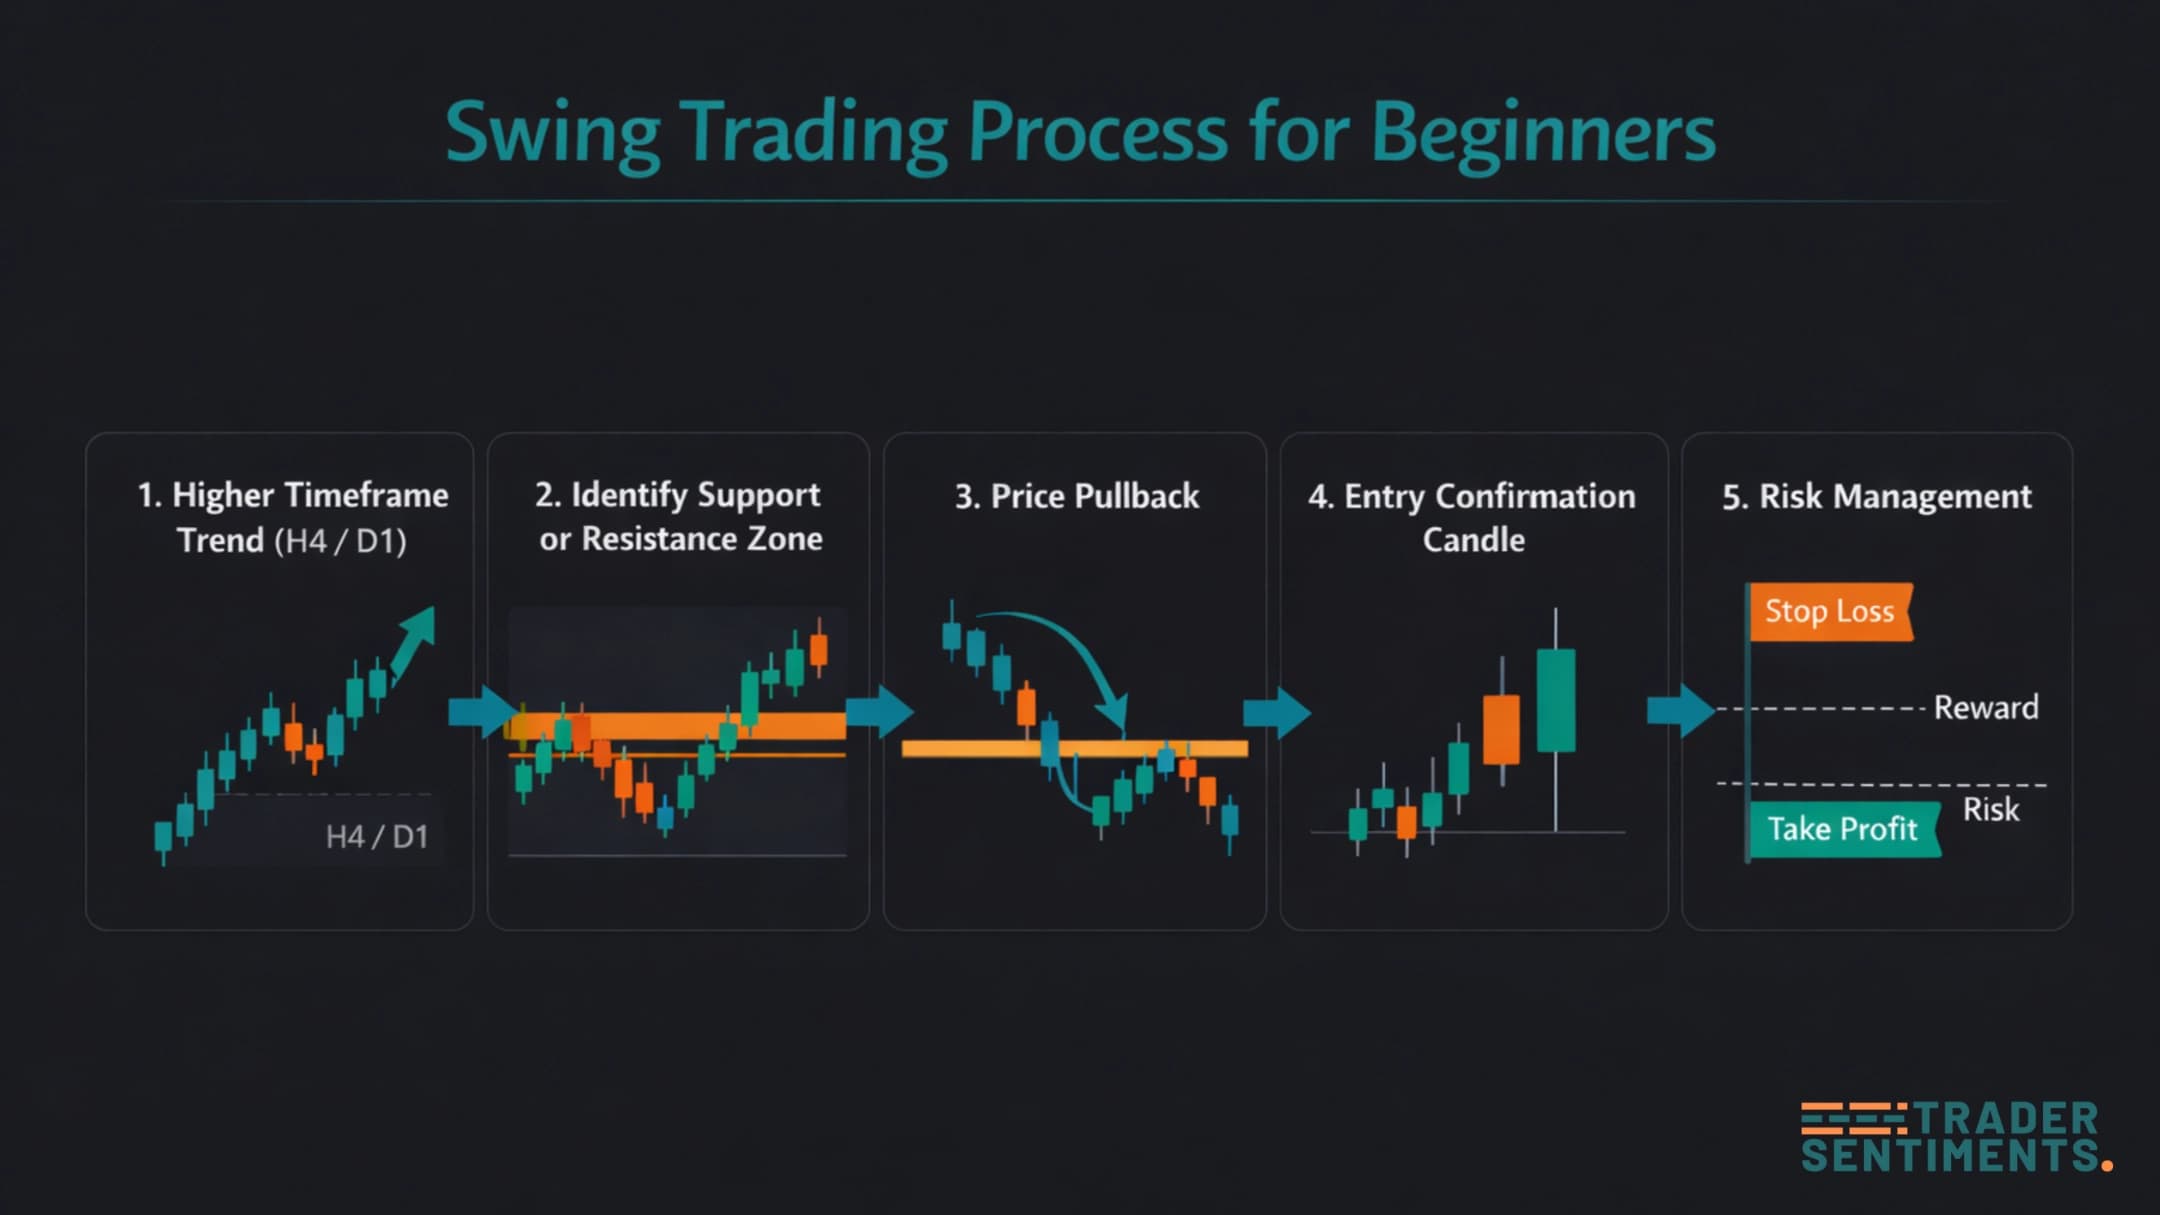
Screen for cointegrated pairs monthly using ADF tests on daily data. Filter for spreads with z-score volatility between 0.8 and 1.5—too low and you waste commissions, too high and risk explodes. Backtest the entry and exit rules over the past five years including transaction costs. If the Sharpe ratio drops below 0.8 after costs, skip it. Paper trade for two weeks. Then execute with half position size for the first month while you calibrate your execution timing. This isn't glamorous. It won't make you rich quickly. But it keeps you from blowing accounts on false correlations and bad execution. The people who survive spread trading are the boring ones who monitor their models, adjust for regime changes, and accept that edges decay over time.