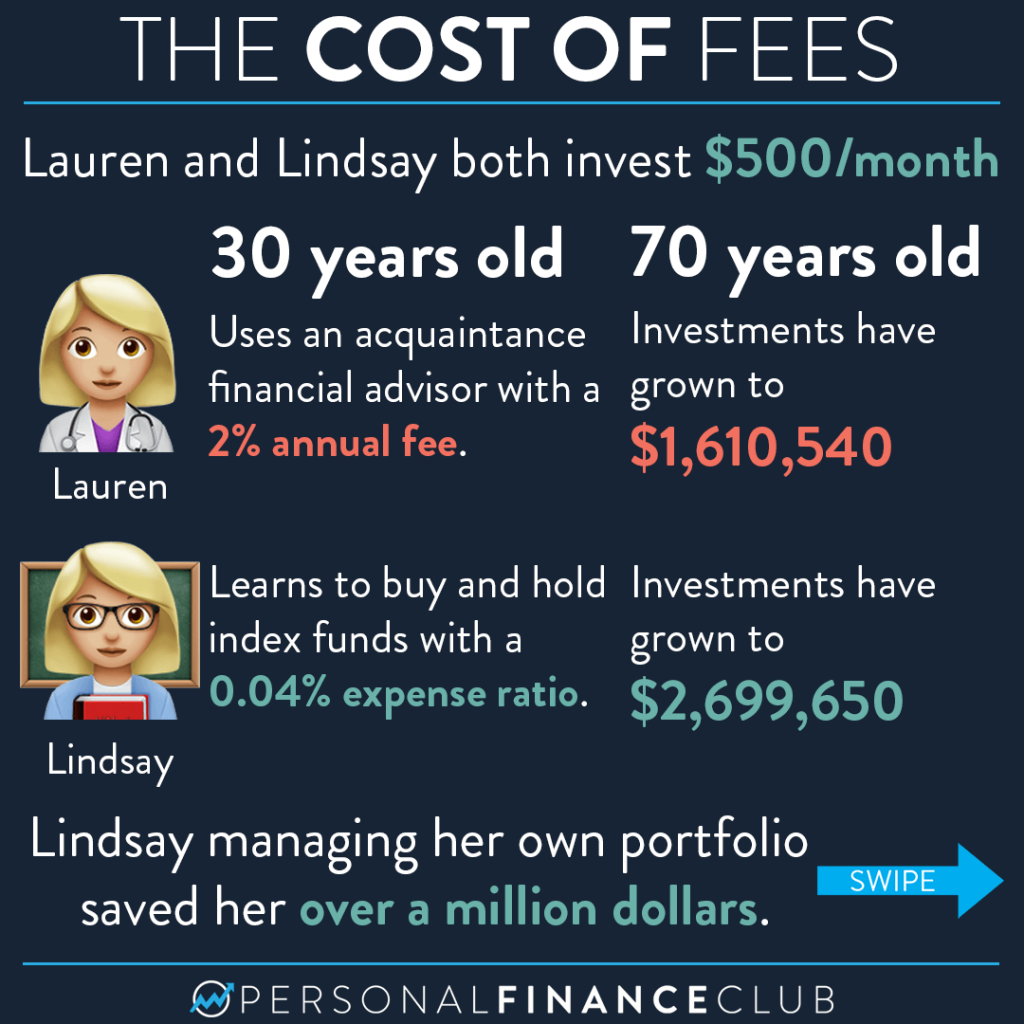
Working with a financial advisor isn't for everyone, but it's also not the scam some people make it out to be
I've sat across from enough advisors over the years to know which ones actually earn their keep and which ones are just riding on client inertia. The money part is straightforward. The relationship part is where most people get confused. Let's start with the actual cost structure because that's what determines whether this is worth your time. Most advisors charge a percentage of assets under management, typically around 1% annually. On a $500,000 portfolio that's $5,000 a year. Some charge flat fees, some do hourly consults, some work on commission and that last category deserves its own warning label.
Are Financial Advisors Worth The Cost
The real question here depends entirely on your situation. If you have under $250,000 in investable assets, the math starts working against you quickly. A 1% fee on $200,000 is $2,000 and you could probably handle basic allocation decisions yourself or use a robo-advisor for a fraction of that cost. If you're at $2 million or more, the fee absolute number sounds big but as a percentage of the services you actually get, it's often reasonable. Tax planning, estate coordination, Roth conversion strategy, social security optimization those are the areas where a competent advisor moves the needle enough to justify the bill. I worked with someone recently who had roughly $1.3 million saved up and was convinced they didn't need an advisor because they "knew enough." They'd been managing their own portfolio through three market cycles and felt confident. Then we started digging into their tax situation and found they were sitting on about $180,000 in short-term capital gains they'd been realizing every year without any offsetting strategy. A single loss harvesting plan and a repositioning of some bond holdings into tax-advantaged accounts would have cut that tax liability by roughly a third. The advisor's fee for the year would have been covered twice over in that one adjustment. But nobody had ever sat down with them and pointed it out. That's the thing people don't always realize. The value isn't in picking stocks. Any decent advisor will tell you that themselves. The value is in the things that happen around the portfolio, the structural decisions that compound over decades and that you tend to overlook when you're not thinking about them systematically.
How to evaluate whether an advisor is actually good
Not all financial advisors are created equal and the industry doesn't do a great job of making that obvious upfront. Here's what I look at when I'm assessing whether someone's worth the money. First, fiduciary status. A fiduciary is legally obligated to put your interests ahead of their own. That sounds like it should be the default, but it's not. Many advisors operate under a suitability standard, which means they can recommend products that are merely suitable for you rather than the best option available. It's a meaningful difference, especially when it comes to insurance products and annuities where commissions can run high. Second, ask about their client profile. If someone's primary clients are retirees with complex estates and you're a 32-year-old starting out, you might not be the right fit. Similarly, if an advisor mostly works with people who have under $100,000 in assets and you're coming in with $800,000, you might get less attention than you'd expect because your account size doesn't generate enough fee revenue for them to justify the hours they'd need to spend with you.
Get the Full Details

Third, look at how they communicate. I had a client whose advisor would send quarterly reports that were basically just performance numbers with a generic newsletter attached. There was no proactive outreach, no life-event check-ins, no tax planning discussion. When that client finally switched, the new advisor caught three separate issues in the first month alone, including a missed required minimum distribution window and a beneficiary designation that hadn't been updated since 2009. That second issue alone could have caused a complete misalignment of their estate plan. The communication pattern matters more than people give it credit for. An advisor who only reaches out when they need you to buy something is a red flag. An advisor who reaches out consistently about things that aren't sales-related is usually someone who actually cares about the relationship on its own terms.
When an advisor is absolutely not worth it
Let me be blunt about the scenarios where hiring an advisor is a waste of money. If your financial life is relatively simple, you have a diversified low-cost portfolio, you're not going through major life events, and you're disciplined about saving and staying the course, you can probably do fine on your own or with a low-cost digital platform. The additional return an advisor generates rarely exceeds 1-2% annually even in the best cases, and after fees that margin gets thin fast. Another scenario where it's not worth it is when you're drawn to advisors who promise outsized returns or stock picks. That's not advisory work, that's gambling with a fee attached. A legitimate financial advisor doesn't try to beat the market, they try to make sure you don't destroy your own plan through emotional decisions, tax inefficiency, or structural oversights. There's also the personality factor. I've seen people sit through annual reviews with advisors they tolerated rather than trusted, continuing to pay fees because they felt awkward about switching. That's not a good outcome for either party. If you don't feel comfortable being direct with your advisor about your concerns, the arrangement probably won't work well regardless of their technical competence.
Alternatives worth considering
Hybrid models exist now where you get access to a human advisor for periodic planning sessions combined with a low-cost investment platform for day-to-day management. These typically run between 0.5% and 0.75% of assets rather than the full 1%. For someone in the middle income range who wants guidance without full-service pricing, this is often the sweet spot. Certified Financial Planner professionals who charge hourly or on a flat-fee basis are another option. You can bring them specific questions, get a plan laid out, and then implement it yourself. It's not as hands-off but it's also not as expensive as ongoing asset-based fees. A comprehensive financial plan from an hourly CFP typically runs between $1,500 and $3,000 depending on complexity. At the very bottom of the spectrum, there are reputable robo-advisors like Betterment, Wealthfront, and Schwab Intelligent Portfolios that manage everything automatically for around 0.25% annually. They handle rebalancing, tax loss harvesting, and asset allocation. They don't handle tax strategy, estate planning, or behavioral coaching, but they handle the mechanical investing part well and cheaply.

The honest answer about whether an advisor is worth the cost is that it depends on how complicated your financial life is and how much peace of mind you value. If you're a busy professional making good money but to think through tax implications, beneficiary designations, and withdrawal strategies year after year, the fee is probably justified. If you're someone who enjoys learning about investing and has the discipline to stay consistent, you might find that the money you save in fees compounds faster than any advice could compensate you.