The Real Math Behind Hiring Someone to Manage Your Money
Most people asking this question already know what they want to hear. They're searching for permission to either spend the money or avoid it. The actual answer depends entirely on your income level, your tax situation, and whether you enjoy staring at spreadsheets at 11pm on a Tuesday. I've sat across from financial planners and I've been the one giving advice to people who didn't want to be advised. The fee structures alone will determine whether the relationship works. A flat annual retainer of $2,000 to $5,000 makes sense if you have a complex tax situation with multiple income streams, rental properties, or equity compensation. A percentage-based fee of 1% to 2% of assets under management only makes sense if you have more than $200,000 to $300,000 invested. Below that threshold, you're paying more in fees than the planner is likely to save you.
Are Financial Planners Worth The Money
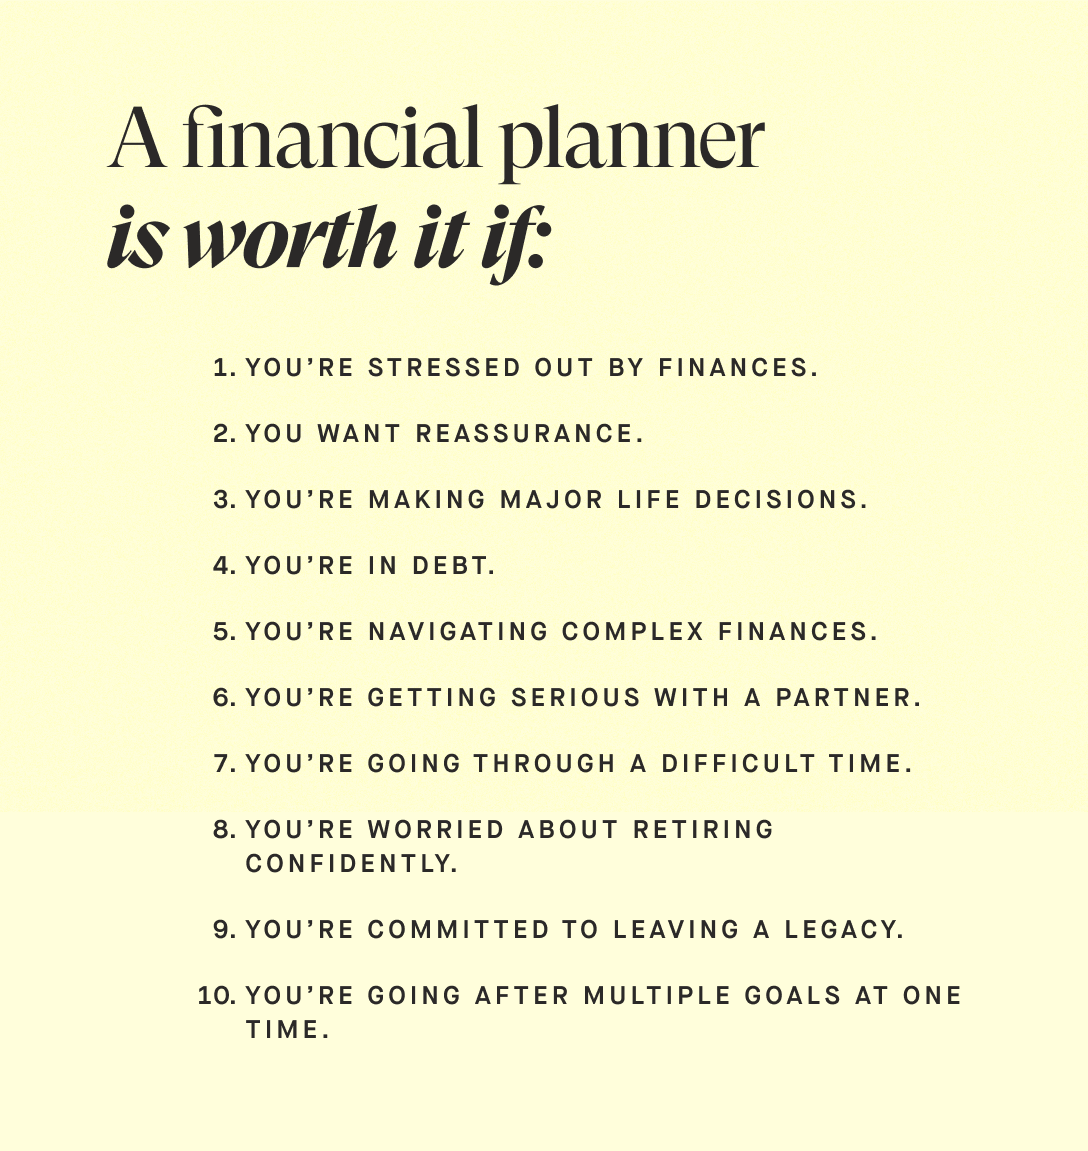
It depends on what category you fall into. Here's how I break it down when someone asks me directly. The simple household. Two incomes, one mortgage, maybe some 401(k)s and a modest brokerage account. A planner might help you optimize tax strategy and catch mistakes you'd otherwise miss, but the fee eats into returns noticeably. I worked with a couple in their late forties who had roughly $180,000 in investable assets and were paying $3,500 a year for planning. Over ten years, that's $35,000 gone before any market growth. They could have hired a CPA for half that to handle their taxes and used a low-cost robo-advisor for the rest. Their financial life wasn't complex enough to justify the premium. The complex household. Business owners, people with stock options, inheritance coming in, multiple properties, maybe a special needs child requiring a trust. This is where a planner earns their fee within the first year alone. I had a client who was rolling over a $400,000 401(k) from a previous employer. The advisor at his old firm pushed him toward an annuity with an 8% surrender charge and annual fees of 2.5%. A proper planner caught that in the first meeting and redirected him into a tax-advantaged rollover into an IRA. That one intervention saved him roughly $12,000 in immediate fees and $10,000+ in ongoing drag. That's the kind of thing that justifies the engagement.
The counter-intuitive part nobody tells you is that the biggest value a planner provides isn't picking investments. It's behavioral coaching. The average investor buys high and sells low during market panic. I've watched clients talk themselves out of selling during the March 2020 crash because the planner literally wouldn't let them sign the paperwork for seventy-two hours. That delay prevented real losses. The planner's job in those moments is to be the adult in the room when you're being irrational. There's also the tax optimization angle that most beginners completely overlook. A good planner will coordinate with your CPA on Roth conversions, tax-loss harvesting, and asset location strategies. Asset location means putting bonds in tax-deferred accounts and equities in taxable accounts. It sounds minor but it can add 0.3% to 0.5% to your after-tax returns annually. Over twenty years on a $500,000 portfolio, that's an extra $15,000 to $30,000 sitting in your account doing nothing special. It just happens because someone thought about where each asset lives. Now here's where it falls apart. The fiduciary distinction matters enormously. Not all financial planners are fiduciaries. Some are brokers operating under a suitability standard, which means they only have to recommend products that are suitable for you, not necessarily the best or cheapest option available. A broker-recommended annuity might pay them a commission of $5,000 to $15,000 upfront while costing you in fees for decades. I've seen this happen repeatedly. Always ask upfront: are you a fiduciary? If they hesitate, walk away.
Get the Full Details

Another failure mode is the planner who takes your money and does nothing. I know this sounds extreme but it's common enough. You hand over $300,000, they put it in a bland portfolio of index funds, and charge you 1% a year for watching paint dry. Meanwhile, you could have done the same thing yourself through Vanguard or Fidelity for 0.03% in fees. The planner added zero value. The relationship survived on inertia and your reluctance to pull the trigger on switching. If you do decide to hire someone, here's what I'd actually do in the first meeting. Bring your last three years of tax returns, a list of every account you own with current balances, your employer's benefit documents, and a written list of your goals with specific numbers and dates. If the planner spends the entire first session talking about products instead of asking about your situation, that's a red flag. A competent planner should be able to identify at least one significant issue within the first thirty minutes just from listening. The alternative path exists and it's worth being honest about. For households with under $150,000 in investable assets and straightforward tax situations, a one-time consultation with a fee-only planner for $500 to $1,500 might be the most efficient use of money. You get a professional review of your setup, someone points out the actual problems, and then you implement the fixes yourself. It's not ideal but it's far better than signing up for a retainer you'll outgrow or paying percentage fees on an account that's too small to support them.
The bottom line is that financial planners are a tool, not a solution. They save time, prevent costly mistakes, and keep you from making emotional decisions during market volatility. But they also cost money, and some of them aren't worth that money. The people who get genuine value are the ones with complex situations who would otherwise make expensive errors, or the ones who need someone to tell them no when they're about to do something foolish with their retirement savings.