Understanding the Arizona NCCI Classification System
The Arizona NCCI Classification Codes Manual is the reference document that insurance carriers and agents use to determine how workers' compensation premiums are calculated for businesses operating in the state. It contains hundreds of classification codes, each tied to specific job duties and risk levels. The manual itself is maintained by the National Council on Compensation Insurance, which provides the framework, but Arizona adopts its own version with state-specific modifications and rating adjustments. I spent about three years dealing with classification code disputes for small contractors in Phoenix. The hardest part wasn't finding the right code in the manual. It was convincing an underwriter that a plumbing company doing both residential service calls and new construction should be split across two different codes rather than folded into a single higher-rated bucket. One common mistake people make is assuming a business description alone determines the code. It doesn't. The actual work being performed, broken down by payroll percentage, is what matters.
How to Read the Arizona NCCI Classification Codes Manual
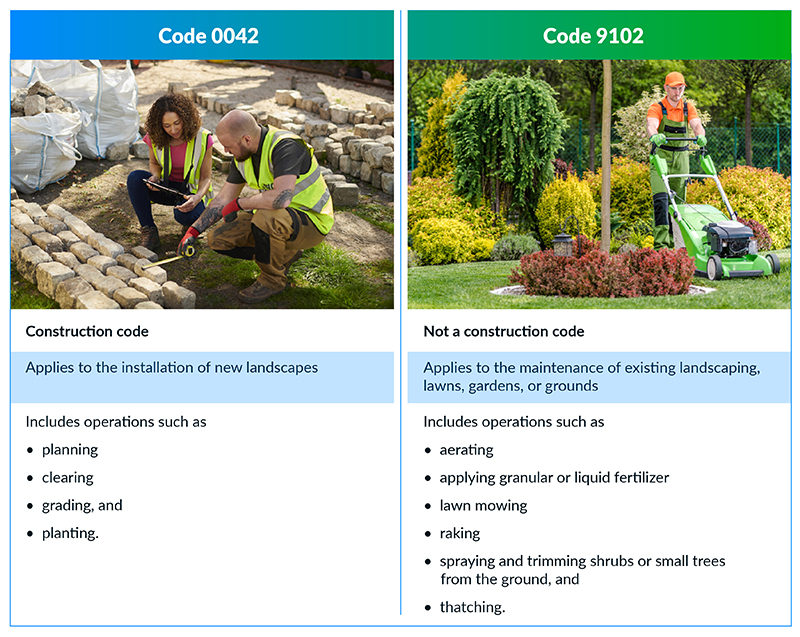
The manual is organized by code number, description, and rate. Each classification includes a narrative explanation of what types of operations are covered. The descriptions can be vague on purpose because they need to accommodate thousands of different business models. When you open it, don't start with your company name. Start by identifying the primary line of work. If you run a roofing company, for example, you might see code 8809 for roofing contractors and code 3851 for carpentry work. If your crew does both new roof installation and repair work on existing structures, those are handled differently for rating purposes. Here's the part most people gloss over. The manual includes exclusion and inclusion notes under each code. These notes tell you exactly what is NOT covered by a given classification. I ran into a situation last year where a landscaping company was coded under 0519, which covers general landscaping operations, but their actual work included tree removal with crane operations. The exclusion note under 0519 specifically calls out tree work involving heavy machinery, and that pushes you into a completely different rating tier. The premium difference between those two codes was roughly forty percent. That's not a rounding error. That's the difference between a profitable contract and a loss.
Where to Find and Download the Manual
The Arizona NCCI Classification Codes Manual is available through the NCCI website at ncci.com. You need to create a free account to access the full document. The download is typically a PDF that runs around eight hundred pages depending on the edition year. There's also a mobile app called NCCI ProDesk that lets you search classifications on the go, which saves time when you're on a job site and need to verify a code before quoting a job. The desktop version of ProDesk is more powerful but requires a paid subscription. If you're an agent or broker, you'll likely already have access through your carrier's rating platform. Most carriers pull NCCI data directly into their quoting systems, so you rarely need to look at the manual yourself unless you're disputing a code assignment. Independent business owners usually access it directly. The download page is straightforward. Pick the current edition, agree to the terms, and the PDF goes straight to your browser. No special software is required to read it, though having a PDF reader with search functionality makes a huge difference when you're looking up a specific code number.
Get the Full Details
Common Pitfalls That Cost Businesses Money
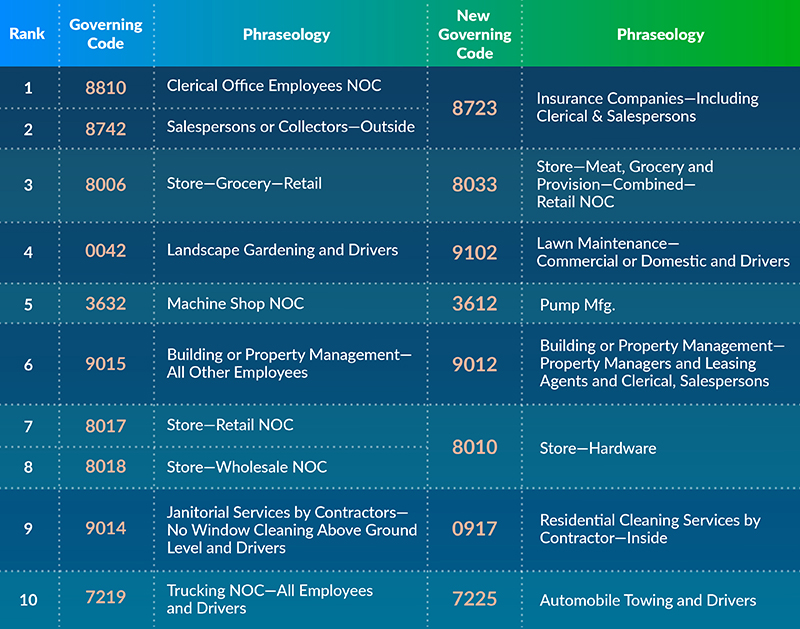
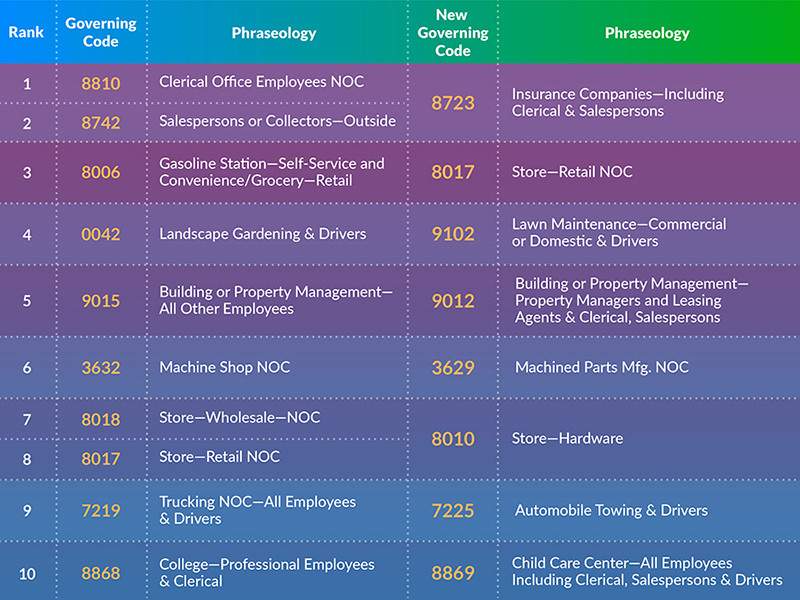
One of the most expensive mistakes I've seen is misclassifying employees based on job title rather than actual duties. A company might call someone a "maintenance worker" and put them under a lower-rated code, but if that person is actually doing roofing or demolition work even ten percent of the time, the audit will catch it. And when it gets caught, you're not just paying the difference on that payroll. You're paying it retroactively, and the auditor doesn't negotiate. Another issue is the assumed rate. NCCI publishes an assumed rate for each classification code, which is basically the expected loss cost before any experience modifier is applied. If your business has a strong safety record and low claims history, your experience modifier can bring your premium well below the assumed rate. But if you're in a high-risk classification and you've had a couple of claims, the assumed rate plus a poor experience mod can make your workers' comp premium astronomical. I had a client with a mod of 1.45 on a code that already carried a high base rate. His premium was nearly double what his competitors in the same trade were paying. The fix wasn't changing his business. It was properly splitting his payroll across multiple codes so the high-risk work wasn't all lumped together. There's also the issue of codes that seem like they should apply but actually don't. Code 8810 is the clerical office employee classification, and it has the lowest rate in the manual. A lot of business owners try to put anyone who spends even a small amount of time at a desk into 8810. But NCCI requires that at least ninety percent of that employee's duties be office work for the code to apply. If your office manager also answers phones on job sites, drives equipment, or handles inventory, the code assignment changes. This is one of those rules that sounds reasonable until you've already been audited and told your entire office payroll needs to be reclassified at a higher rate.
When the Manual Doesn't Give You an Answer
Sometimes you'll encounter a business operation that doesn't fit neatly into any existing classification. This happens more often than you'd think, especially with newer industries or companies that blend multiple trades. In those cases, NCCI provides a process called a class code request, where you submit a detailed description of your operations and the association will assign an appropriate code or combine multiple codes. The turnaround time is usually thirty to forty-five business days, and you need to provide substantial documentation including payroll breakdowns and job descriptions. During that waiting period, your policy gets rated on a provisional basis, which means you'll pay a higher estimate and potentially get a refund later if the assigned code comes out lower. I recommend having a backup plan for the provisional period. If you're quoted a premium based on a placeholder code and your cash flow is tight, you can ask your carrier about alternative rating options. Some carriers allow you to use a manual rate with no modifications during the request process, which might be cheaper than the provisional assignment depending on your experience history. It's not a permanent solution, but it can ease the immediate financial pressure while you wait for the official classification. There are also cases where NCCI classifications completely miss the mark for certain operations. The manual hasn't kept pace with changes in how some industries operate. For instance, solar panel installation doesn't have a dedicated code that captures the unique risk profile of the work. It often falls under electrical contractor codes or roofing codes, neither of which accurately reflects the actual exposure. When that happens, you're stuck choosing between two imperfect options, and the audit trail will show both choices as defensible depending on who's arguing the point. This is one area where having a good relationships with your carrier's underwriting department matters more than anything else in the manual.
Practical Steps for Getting Your Code Right the First Time
Start by listing every job function your employees perform throughout the year. Don't estimate. Write down the actual tasks with approximate time percentages. Then cross-reference each task with the NCCI code descriptions and their exclusion notes. Pay special attention to any code that requires a minimum percentage of payroll to qualify. If your payroll distribution changes seasonally, you'll need to account for that during the audit, not after. I've seen businesses lose thousands because they didn't track seasonal variations in their employee duties, and the auditor had to reconstruct the year from incomplete records. Keep your documentation organized in a way that an auditor can follow without asking questions. A simple spreadsheet with employee names, job titles, primary and secondary duties, and payroll percentages by quarter is usually enough. When you submit this during an audit, it cuts the review time from a few days down to maybe an hour. Auditors appreciate it when the paperwork is clear because it reduces their workload, and there's no guarantee they'll treat you more favorably, but it does prevent them from defaulting to the highest-rated code when something is ambiguous. If you're working with an insurance agent or broker, make sure they understand your business well enough to classify it correctly from the start. A lot of agents use quick lookup tools that give you the most obvious code, which is often wrong for complex operations. Ask them to walk through the classification with you and explain why each code applies. If they can't reference specific sections of the manual, find someone who can. The initial premium calculation sets the tone for your entire policy year, and correcting it later is always more expensive than getting it right upfront.
One final thing that most people don't consider. The classification code you're assigned affects more than just your workers' compensation premium. It can influence your eligibility for certain safety programs, your ranking with state regulatory agencies, and even how customers perceive your company when they request proof of insurance. A code that suggests higher risk might make some general contractors hesitate before hiring you for a project, even if your safety record is clean. This is a side effect that nobody mentions in the manual, but it's real enough that I've had clients change their business structure specifically to land under a less intimidating classification. It's not something to take lightly.