How ARM Loan Calculations Actually Work
The core formula behind any adjustable rate mortgage calculator is the same standard amortization equation used for fixed loans, except you re-calculate the payment at every adjustment date. You take the remaining principal balance, divide it by the number of payments left, and add the monthly interest based on the current rate. That's it. The difference from a fixed-rate calculation is purely that you repeat this process every time the rate changes instead of running it once and forgetting about it. Most online calculators you'll find do one of two things: they show you the payment at the initial teaser rate, or they run a multi-year projection across all adjustment periods. The second type is what actually matters for decision-making. The first type will mislead you into thinking your payment is $1,400 when it's going to be closer to $1,850 within three years. Here's what the calculation looks like step by step. Let's say you have a $350,000 loan at a 5/1 ARM with an initial rate of 6.25%. Your first 60 months use the standard amortization formula:
M = P × [r(1+r)^n] / [(1+r)^n - 1] Where P is the principal, r is the monthly rate (0.0625 / 12 = 0.0052083), and n is the total number of payments (360 for a 30-year term). That gives you a monthly payment of approximately $2,154.28 for the first five years. After that, the rate adjusts based on the index plus margin. If the index is SOFR at 4.5% and your margin is 2.75%, your new rate becomes 7.25%. You re-run the formula with the remaining balance and remaining term. I went through this manually for a client last year who had a 7/1 ARM with a 2% annual cap and a 5% lifetime cap. The calculator showed her payment increasing by about $180 per month after the first adjustment. But here's what the typical calculator misses: the payment cap. Her contract had a 7.5% payment cap between adjustments, which meant even though the full amortization at the new rate would have been $2,320, she was only required to pay $2,154 × 1.075 = $2,315.85. The $38 shortfall got added to the principal as negative amortization. Over three adjustment periods, that compounded into an extra $2,100 in principal that most people never notice until they're sitting at a balance significantly higher than what they expected.
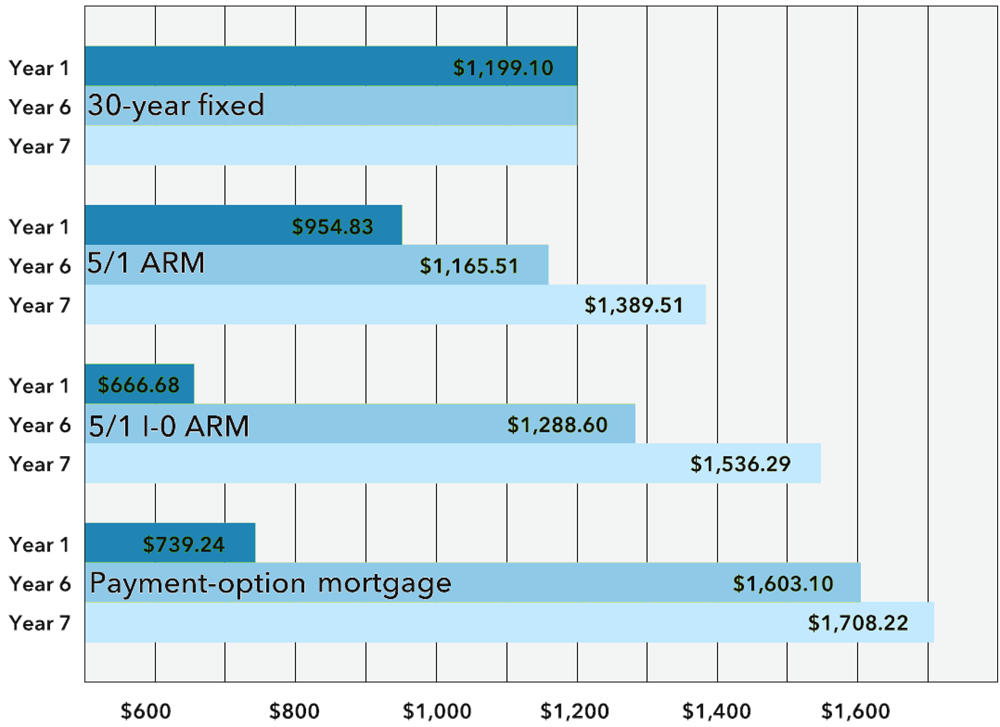
This is the single biggest pitfall with ARM calculations. Almost every free online calculator ignores payment caps and shows you the full amortizing payment at each adjustment. You'll see a clean projection that looks manageable. In practice, if your payment cap kicks in, your loan balance grows and your future payments grow faster because you're paying down less principal each month. Run the numbers both ways—with and without payment cap effects—and compare the end balance after year five. The gap is usually between $3,000 and $12,000 depending on how much the rate moves. Another thing nobody warns you about is the difference between the option ARM calculator and a standard one. If your loan has payment option ARM features, where you can choose to pay interest-only, minimum payment, or the full amortizing amount, the calculator needs to handle three separate scenarios. Most tools only show the full amortization path. When I was modeling a case for a borrower who kept selecting the minimum payment option during the reset period, the projected payoff balance at year seven was 23% higher than the original loan amount. The calculator had to account for the fact that each minimum payment period was adding to the balance, which then got amortized over a shrinking remaining term.
Get the Full Details

What Most Calculators Get Wrong
The adjustment frequency matters more than people realize. A 5/1 ARM adjusts once per year after year five. A 6/1 ARM adjusts once per year after year six. But there are also 5/6 ARMs, where the first adjustment happens at six months, then annually after that. Most calculators don't support the 5/6 structure at all. You'll plug in the wrong adjustment schedule and get completely inaccurate projections for the early years, which is exactly when the rate movement has the most impact on your cash flow. Index selection is another hidden variable. Some calculators let you pick between one-year Treasury, CMT, or SOFR. The difference between these indices at any given time can be 0.25% to 0.75%, which translates to $50 to $150 per month on a $300,000 loan. If the calculator defaults to one index but your actual loan is tied to another, every number in the projection is slightly wrong. Check your loan estimate documents to confirm which index your loan uses before trusting any calculation. The margin is usually fixed at origination, but some lenders adjust it under certain conditions. It's rare, but it happens. If your loan agreement has a margin adjustment clause tied to credit score drops or loan-to-value changes, no generic calculator will account for that. You'd need to build a custom spreadsheet that pulls your margin from the note and applies it manually at each reset.
A Practical Workflow That Actually Works
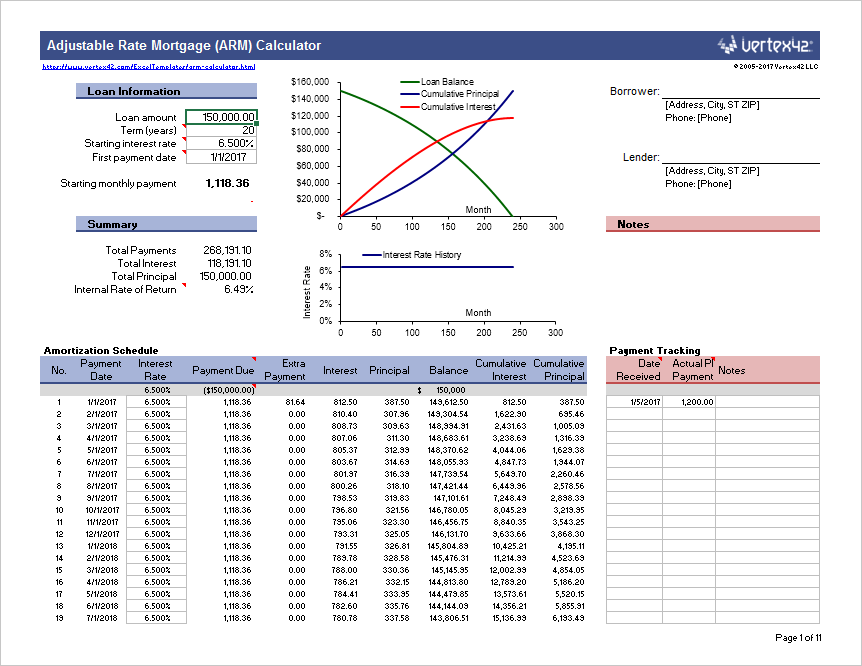
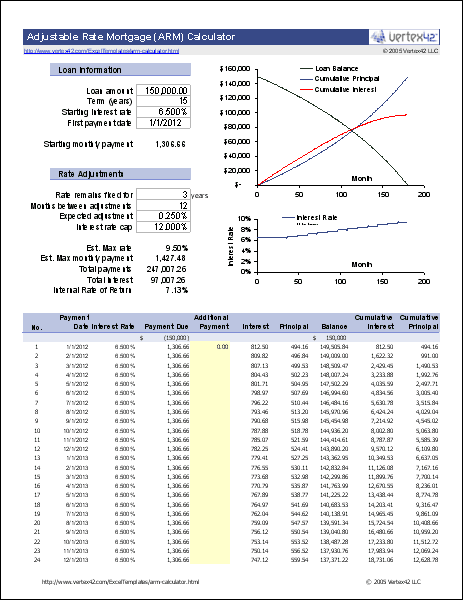
Don't rely on a single online calculator. Build your own in a spreadsheet with these columns: adjustment date, index value at reset, rate (index + margin), capped rate (apply periodic and lifetime caps), new monthly payment, payment cap if applicable, principal balance at start of period, principal paid during period, principal added if payment cap triggered, and ending balance. Copy the row down for each adjustment period. When I built this for the client I mentioned earlier, the spreadsheet took about 20 minutes to set up properly. Once it was done, comparing scenarios—what if the index jumps 1%, what if it stays flat, what if there's a recession and the index drops—gave her a clear picture of her exposure. The typical online calculator gave her one number at the teaser rate and another at the fully indexed rate. The middle ground, where most real-world resets actually land, was invisible to her. If you want a downloadable tool, the Federal Housing Finance Agency publishes ARM simulation spreadsheets on their website that handle multiple index options and cap structures. They're not the prettiest interface in the world, but they're accurate and reflect actual regulatory requirements. The Department of Housing and Urban Development also has a similar tool. Neither of them advertises themselves as Arm Loan Calculator products, but they'll give you results that align with what your lender's system would produce.
When ARM Calculators Completely Fail
Here's the blunt truth: no calculator can accurately model your ARM payment if your loan includes a teaser rate that's significantly below the fully indexed rate. The teaser is a marketing construct, not a contractual rate. It might last 3, 6, or 12 months, and then the rate snaps to something closer to fully indexed. Standard calculators often treat the teaser rate as the starting point and adjust from there, but the actual jump on day one of the reset period can be much larger than the periodic cap allows because the teaser creates a gap that isn't part of the normal index-plus-margin structure. Your lender's disclosure documents will show this, but a generic calculator won't. Also, if your loan has a hybrid ARM—like a 3/1 ARM where the first three years are fixed at one rate and then it becomes a 1/1 ARM—the calculator needs to handle two different adjustment schedules in sequence. Very few free tools support this. You'd need to run two separate calculations and manually bridge them at the transition point. The biggest limitation, though, is that all these calculations assume the index moves in predictable ways. It doesn't. If rates spike unpredictably, your payment could jump to the lifetime cap faster than any projection shows. The calculator gives you a range based on historical index behavior, but it can't account for black swan rate events. When that happened in 2022, a lot of people who'd only looked at the baseline projection were caught completely off guard.

If you're trying to decide between an ARM and a fixed-rate loan, the calculation is straightforward but only if you use realistic assumptions for the index forecast. Picking the middle-of-the-road index value from today and projecting it forward for ten years will give you a number that sounds reasonable but means nothing. Look at where the index has actually been over the past ten years, factor in where it's headed based on Fed guidance, and run the calculator under at least three scenarios: rates stay flat, rates go up 2%, and rates go up 4%. The worst case is the one that matters.