Chile's Great Economic Experiment Under Pinochet
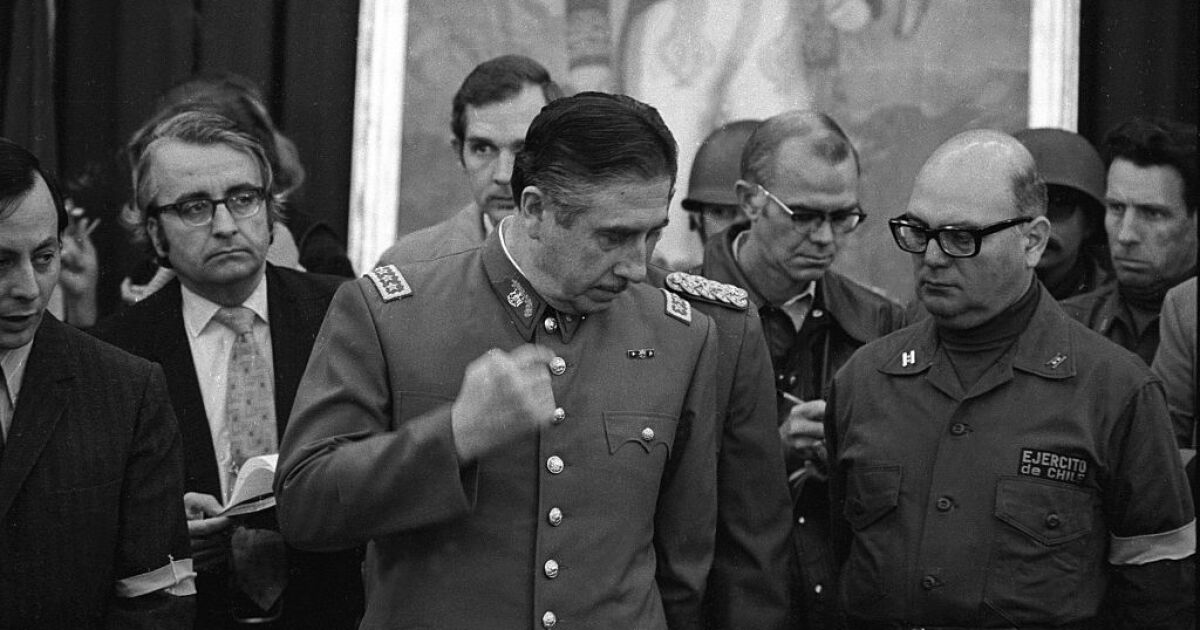
The military junta that took power in Chile on September 11, 1973 didn't just restructure the government. Within two years, they completely rebuilt the economy using a framework that most economists still argue about today. The so-called Chicago Boys, a group of Chilean economists educated at the University of Chicago under Milton Friedman's influence, designed the core of what came to be known as the Augusto Pinochet Economic Policies. What followed was one of the most aggressive free-market experiments in modern history, and understanding how it actually worked requires looking past the usual talking points. The policy shift didn't happen overnight. After the coup, President Pinochet initially relied on more traditional authoritarian economic measures. Things turned around in 1975 when the Chicago Boys gained real influence inside the government. The first major move was a sharp currency devaluation followed by a fixed exchange rate regime. They pegged the peso to the US dollar to kill hyperinflation, which had been running above 600 percent annually under the Allende government. That alone cut inflation dramatically within the first year. Then came the structural changes. Tariffs were flattened from a wall of rates that went as high as 375 percent down to a uniform 10 percent. State-owned enterprises were privatized in bulk. The copper industry, which had been nationalized by Allende, stayed under state control through Codelco — one of the few major industries not touched. The pension system was completely overhauled, replacing a pay-as-you-go model with individual capitalization accounts managed by private AFPs. Trade liberalization happened fast, almost all at once rather than gradually.
I spent a lot of time working through the original Chilean central bank documents and IMF reports from that era when I was researching how quickly these policies could actually move through an authoritarian system. One thing that comes up repeatedly and catches people off guard is that the timing and sequence mattered enormously. The initial shock therapy approach in 1975 caused a brutal recession where GDP dropped nearly 13 percent and unemployment spiked to around 25 percent. But the recovery that followed was real. By 1979, Chile had the highest per capita income growth rate in Latin America for several consecutive years. The question that still separates serious analysts from casual commentators is whether that growth would have happened anyway, or whether the policy design itself was the primary driver.
How It Actually Functioned in Practice
The key mechanism behind these policies was the conversion rate system paired with aggressive fiscal adjustment. Government spending was cut hard. The deficit went from roughly 7 percent of GDP down to near balance. That fiscal discipline, enforced without any democratic check, is what made the monetary stabilization credible. Other countries tried similar strategies — Argentina in the early 1990s, Ecuador later on — but they lacked the same combination of an authoritarian government that could push through unpopular measures and a central bank with real independence backed by a fixed anchor. The financial liberalization piece is where things get complicated. Interest rates were freed, credit controls were removed, and capital account liberalization happened fairly quickly. This produced a massive credit boom in the early 1980s. Local banks and finance houses, many owned by families closely tied to the regime, lent aggressively in dollars while borrowing domestically. When the US Federal Reserve raised rates sharply in 1981 and the copper price collapsed, the whole structure came unstuck. The 1982-83 crisis wiped out about 15 percent of GDP. Multiple banks failed. The government had to intervene and re-nationalize the banking system. The fix involved a targeted deposit guarantee and restructuring that cost roughly 20 percent of GDP — a number that surprised even the policymakers themselves. Here's something most summaries gloss over: the social cost dimension. Labor union rights were suppressed, minimum wage laws were weakened, and layoffs happened with virtually no legal recourse. The poverty rate, which had fallen under Allende, jumped back up during the crisis years. Gini coefficient data shows inequality actually increased significantly during the Pinochet years, despite overall GDP growth. So you had growth with distribution that got worse, not better. That pattern repeats in other dictatorship-led development cases and it's worth keeping in mind if you're evaluating this as a model.
Get the Full Details

Common Misunderstandings and What the Data Actually Shows
One persistent myth is that Pinochet's policies eliminated poverty. They didn't. Poverty fell from around 45 percent in 1970 to roughly 38 percent by 1980, then spiked back above 40 percent after the 1982 crisis. It wasn't until the 1990s, under the democratic governments that followed, that poverty dropped below 20 percent. Growth during the 1970s was real but concentrated. The top income quintile captured a disproportionately large share of the gains. Another misleading claim is that Chile became a free-market paradise. The state remained heavily involved through Codelco copper revenues, which funded large portions of the budget and later social programs. There were price bands on copper exports, strategic tariffs that were reintroduced in certain sectors, and significant state direction of investment through development agencies. The economy was market-oriented, yes, but calling it laissez-faire misses important nuances. When I've walked people through the empirical literature on this, the most productive approach is to separate the policy evaluation into distinct periods. The stabilization phase of 1975-1981 showed genuine macroeconomic success. The crisis and recovery of 1982-1990 showed both the strengths and the vulnerabilities of the model. The democratic continuation from 1990 onward, where the basic framework was preserved but modified with social spending increases and more gradual liberalization, is actually where the most sustainable improvements in living standards occurred. Pinning all the credit or blame on the 1973-1990 period alone gives you an incomplete picture.
Limitations of the Model and Where It Broke Down
The Pinochet Economic Policies worked as long as copper prices stayed reasonably high and external conditions were favorable. The moment those conditions shifted, the rigidity of the system became a liability. The fixed exchange rate that had anchored inflation also meant that when terms of trade deteriorated, there was no automatic adjustment mechanism. The government tried a devaluation in 1982 and it triggered the full-blown crisis instead of preventing one. The institutional foundation was another constraint. Authoritarian governance allowed rapid decision-making but eliminated feedback mechanisms. When the Central Bank governor, José Pinera, and Finance Minister Sergio de Castro wanted to respond to the emerging banking crisis, there was no congress to negotiate with, no press to scrutinize decisions, and no electorate to hold anyone accountable. That sounds efficient until you need course corrections. The 1982 intervention was delayed and half-measured because the political structure didn't allow for honest public assessment of what was going wrong. If you're studying this for practical purposes — whether academic research, policy analysis, or comparative government work — the most useful takeaway isn't a simple verdict of success or failure. It's that the Chilean case demonstrates how effectively market-oriented reforms can be implemented without democratic constraints, and simultaneously how vulnerable that implementation is to external shocks when institutional safeguards are absent. The policies themselves are documented in detail through the Banco Central de Chile archives, IMF country reports from the 1970s and 1980s, and the work of researchers like Carlos Massad and Juan Carlos Valdes at the Universidad Catolica. The raw data is accessible if you know where to look.