What You Actually Need to Know Before Signing One
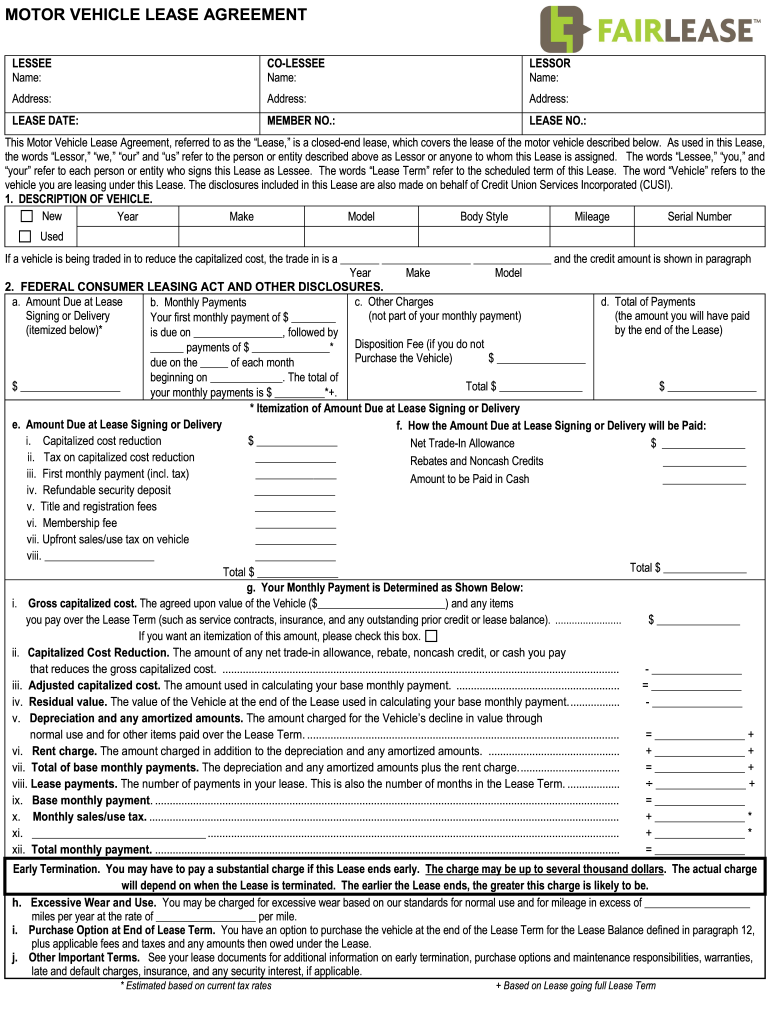
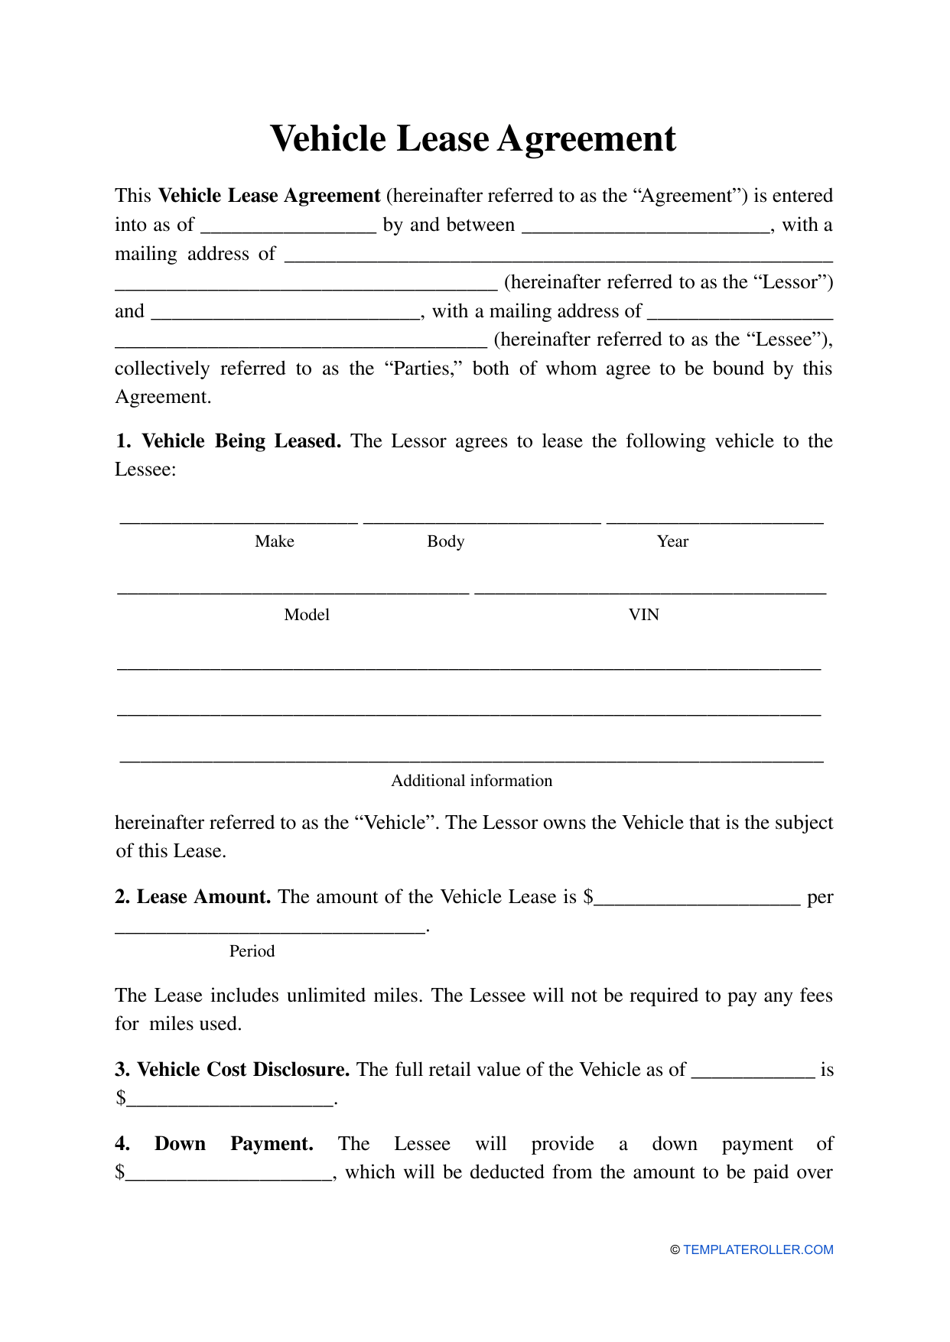
Most people treat a lease like a long-term rental and walk into it completely unprepared for how the financial mechanics actually work. The lease amount you pay each month is driven by the vehicle's depreciation during the term plus a finance charge, not by the full sticker price. That means understanding residual value is the single most important thing you can do before even looking at cars. If the residual is set too low by the lender, your payments will be artificially high. I've seen leases where the money factor was converted to an interest rate equivalent of 8.5% while the borrower thought they were getting "low rates."A standard Auto Lease Agreement is a three-party contract between you, the leasing company, and usually the dealer. It specifies the capitalized cost, the residual value, the money factor, the lease term in months, and the mileage allowance. The document also includes the early termination clause, wear-and-use standards, and disposition fee requirements. Most people skip reading those last three sections and then get hit with charges they didn't expect at turn-in. Here's the practical workflow. You start by negotiating the capitalized cost the same way you would negotiate a purchase price. Dealers often leave money on the table here because they know lessees focus on the monthly payment instead of the gross capitalized cost. Once that number is locked, the leasing company sets the residual based on their internal guides, typically ALG or DMS data for your specific market. You then calculate the deferred gross acquisition fee, add any taxes, and divide by the term length. Simple on paper. I ran into a specific problem last year with a lessee who had a gap between what the dealer called the "adjusted capital cost" and what actually appeared on the contract. The dealer had rolled an optional aftermarket package into the cap cost but the leasing company's residual calculation didn't account for it, which depressed the residual by about 4%. That translated to roughly thirty dollars a month over 36 months. The workaround was pulling the original Monroney sticker showing the factory-installed versus dealer-added equipment, cross-referencing it with the lease acquisition order, and filing a correction request with the lessor's operations department. It took fourteen business days to resolve but saved the customer about one thousand dollars over the life of the lease.
The Parts People Always Misunderstand
The money factor is not an interest rate. Multiply it by 2400 to get the approximate annual percentage rate. A money factor of .00125 equals about 3% APR. That conversion isn't advertised because it makes the deal look less attractive than "low monthly payments" suggests. Mileage overage charges are where leases bleed money. The standard rate is two to three cents per mile, but some contracts go as high as five cents. If you drive more than fifteen thousand miles a year regularly, negotiate the allowance upfront or budget the overage into your decision. Crossing 18k miles on a 12k allowance at three cents per mile costs you four hundred and fifty dollars at turn-in. That's not a penalty, it's a contractual obligation. Disposition fees are another hidden cost. Most leasing companies charge between five hundred and seven hundred dollars when you return the vehicle. Some will waive it if you lease another car from the same brand within sixty to ninety days. I always tell people to confirm the waiver policy before signing because the salesperson will rarely volunteer it.
Early Termination Is Expensive and Usually Inescapable
If you need to exit a lease early, the buyout amount is calculated using the remaining payments plus the residual value, often with an early termination penalty layered on top. Some contracts use the remaining payment method, which means you owe almost everything left on the lease. Others use the adjusted lease balance method, which can be slightly better but still leaves you owing significant money. The only realistic exit routes are a lease swap through a reputable marketplace, a transfer to someone with good credit, or paying off the difference if the car's market value exceeds the lease payoff amount. That last option only works if you can sell or trade the vehicle quickly. Wear-and-use standards are defined in the agreement but rarely explained in detail at signing. Normal wear typically allows for tire tread down to two sixty-fourths, minor stone chips under one inch, and small scratches that don't penetrate the clear coat. Anything beyond that gets charged. I once handled a turn-in where the inspector flagged a nine-inch scratch on a door panel that the customer had repaired with a touch-up pen before returning the car. The repair made it worse, not better, and the charge ended up being eight hundred and fifty dollars for panel respray. The fix would have been leaving it alone and accepting the normal wear exemption.
Get the Full Details
What to Check Before You Sign
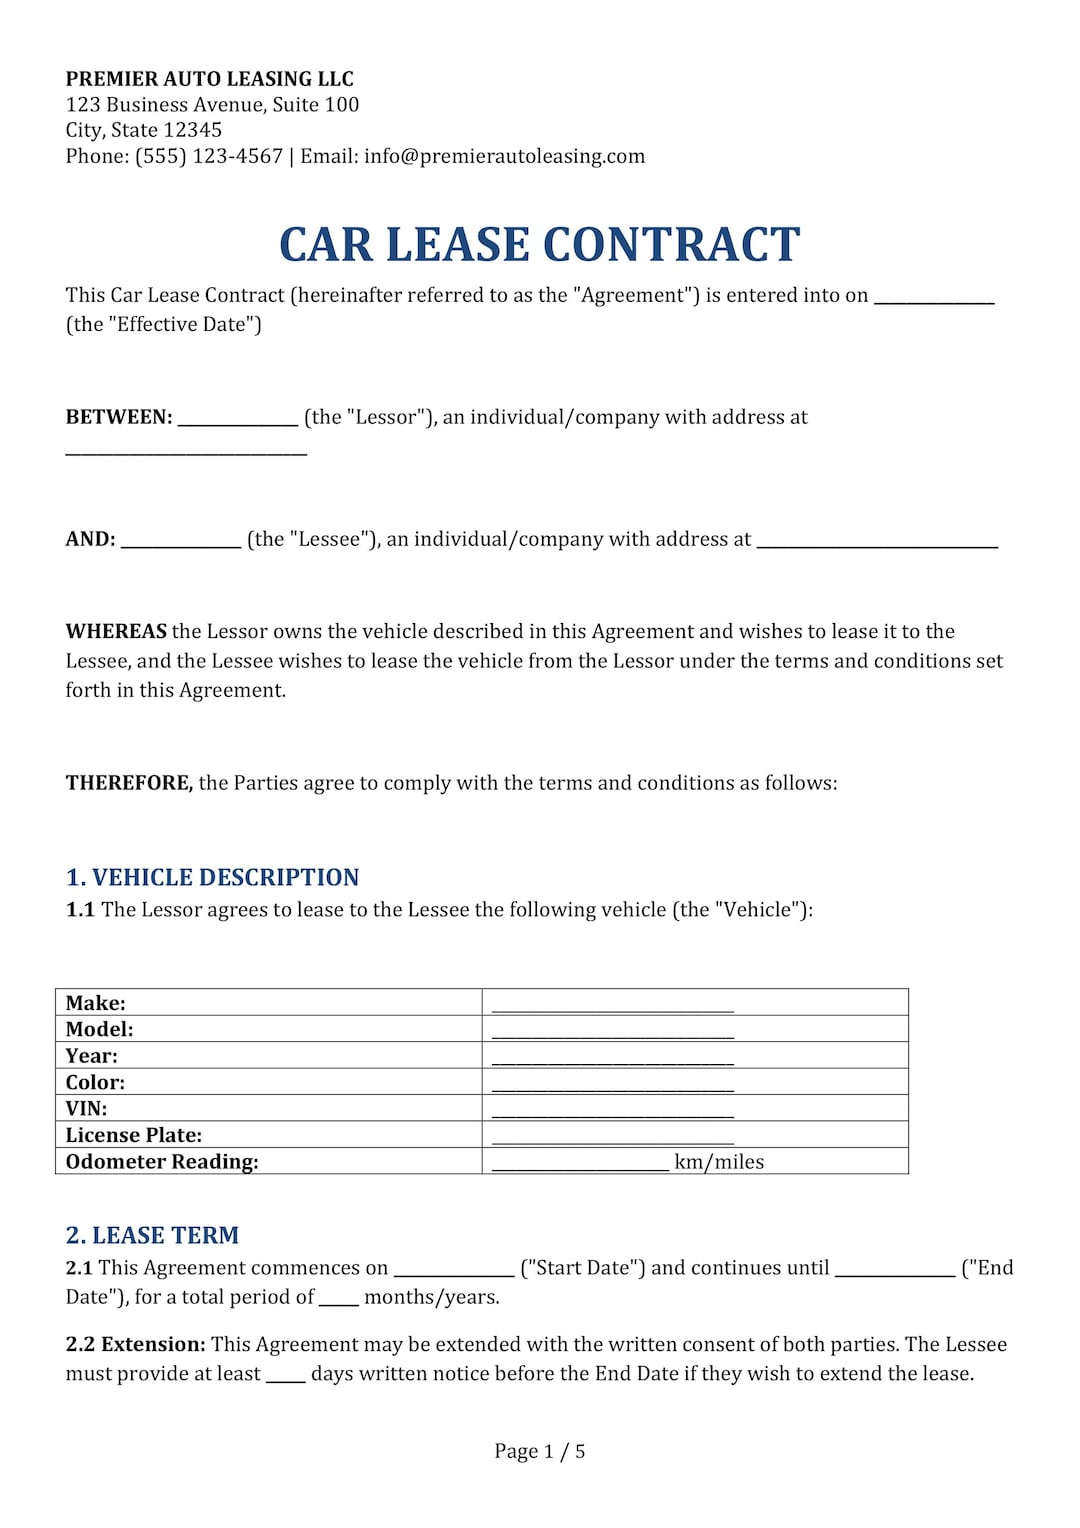
Verify the capitalized cost matches the agreed price exactly. Confirm the residual value is listed and check it against current ALG residuals for your zip code and trim. Make sure the mileage allowance matches your actual annual driving pattern. Review the early termination clause and calculate what an exit would cost at the twenty-four-month mark versus the thirty-six-month mark. Ask for a copy of the full lease agreement before you leave the dealership and read it at home. Dealers are required to provide it, and they won't rush you through this step if you insist. Down payments and security deposits on leases are not refunds. If you put two thousand dollars down and the car gets totaled in month three, that money is gone. It went toward your first few payments. Some states limit how much you can pay upfront at signing to a first month's payment, a security deposit, and unavoidable fees. Know your state's regulations so the dealer doesn't pile on excessive cash due at signing. The biggest mistake I see is people optimizing for the lowest monthly payment without looking at the total cost. A lease with a lower payment might have a worse residual, a higher money factor, or a shorter term that rebuilds equity nowhere. Run the numbers on total cost over the full term including taxes, fees, and expected overages before you commit.