How Auto Liability Limits Actually Work (And Why The Worksheet Matters)
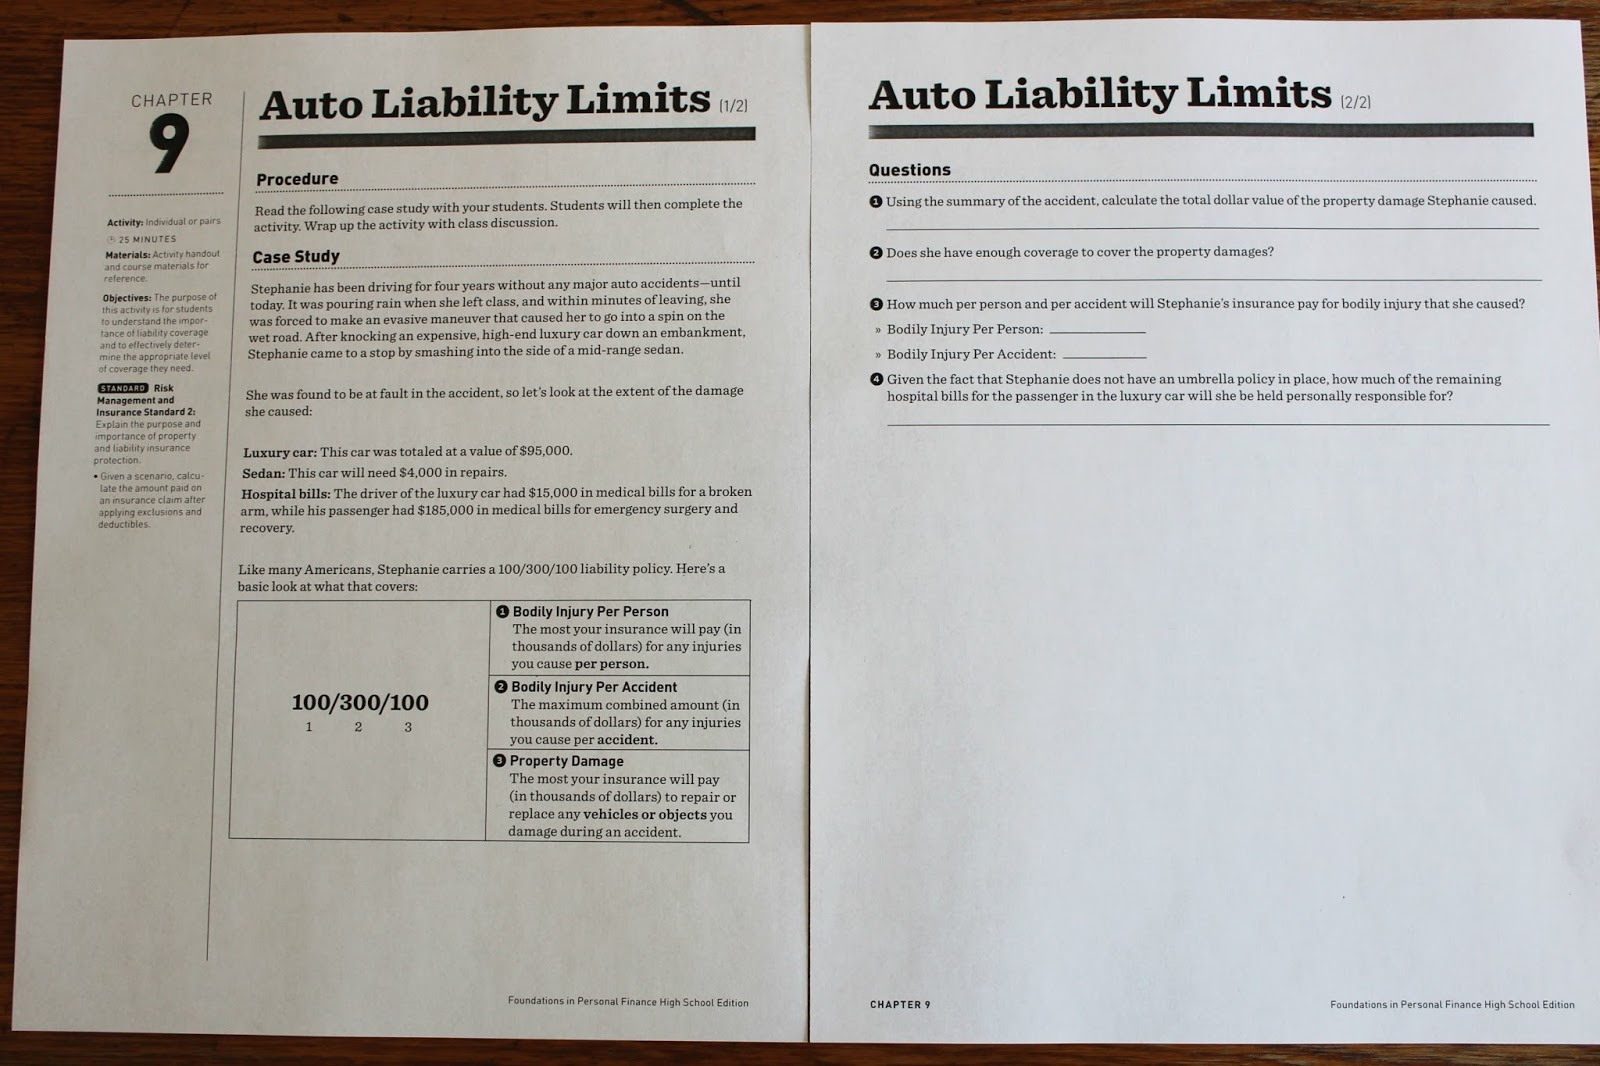
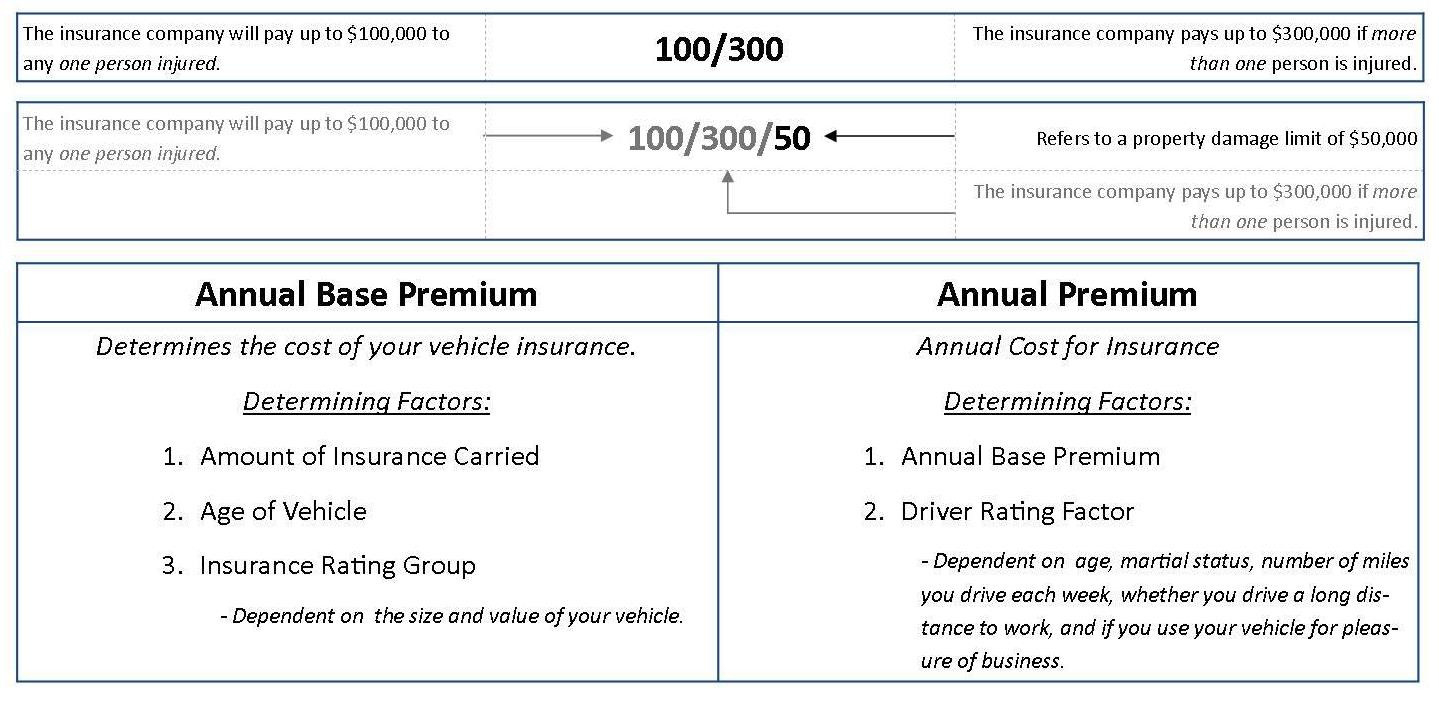
You get hit by someone who barely has the state minimum limits. That conversation usually happens three weeks after the crash, when the other driver's insurance company tells you their policy maxed out at $25,000 per person. At that point you wish you'd looked at Auto Liability Limits Worksheet Answers before buying your own policy. The worksheet breaks down into three numbers — bodily injury per person, bodily injury per accident, and property damage per accident — written as something like 100/300/100. That first number is the maximum the insurer pays for one injured person. The second is the total ceiling for everyone hurt in the crash. The third covers only damage to other people's property. I keep my original auto liability limits worksheet from 2008 somewhere. Back then the recommended floor was 100/300/100. Nobody argued with it. Today the same worksheet would probably start at 250/500/100 if you're in an urban area. The math behind it hasn't changed, but the medical bills have doubled in most states.
The Formula Behind The Numbers
Start with your state's minimum requirements, which you can find on your DMV or insurance department website. Then work through three variables: your assets, your income stream, and your risk exposure. Assets determine your umbrella need. If you own a home and have retirement accounts, $25,000 in bodily injury coverage is almost never enough. A single severe injury claim easily exceeds that. I had a client once who carried 50/100/25 and got sued after a T-bone collision where the other driver needed spinal fusion surgery. The claim settled at $142,000. She lost her savings because her limits were exhausted. Income matters because future earnings loss is a standard damage category. If you make six figures, a claimant's attorney will factor in lost wages up to your retirement age, which inflates the settlement value. Higher limits protect against that calculation.
Risk exposure is the trickiest variable. People who commute long distances, drive in dense cities, or frequently transport passengers should lean toward higher limits. Someone who drives ten minutes to work in a rural town can probably get away with lower coverage, but that's still a gamble.
Get the Full Details
How To Fill Out The Worksheet Correctly
Get your state minimums first. Then determine your total insurable assets — home equity, vehicles, investment accounts, but not your primary residence homestead exemption unless your state protects it fully. Multiply your asset total by 1.5 to 2. That gives you a rough bodily injury per person target. For the per-accident limit, multiply the per-person number by three. This accounts for multiple claimants and future earning capacity arguments. The property damage limit is usually the same across the board — $100,000 is standard for most drivers. $25,000 is the bare state minimum in some places and it is insufficient for a modern collision involving two newer vehicles. Here is the part that trips people up: the difference between combined single limit and split limit policies. A CSL of $300,000 covers bodily injury and property damage from a single pool. Split limits divide that pool. With 100/300/100 you might have $100,000 available for one injured person, but only $200,000 left for the remaining accident costs after one claim hits the first limit. That gap matters when multiple people are hurt.
I ran into a specific edge case last year where the worksheet calculation failed. A client had no traditional assets — no home, no significant savings — but they worked as an independent contractor with irregular high-income years. The standard worksheet pushed them toward minimums based on asset count. I switched the method and calculated based on income stabilization instead. We landed on 150/300/50 because their future earning potential was the real threat to their finances. Standard Auto Liability Limits Worksheet Answers would have left them exposed.
Where The Worksheet Fails You
It does not account for uninsured motorist coverage, which is a separate but equally important limit calculation. Many people fill out the worksheet, pick their liability numbers, and forget to bump their UM coverage to match. That mismatch shows up exactly when you need it most — when the at-fault driver has no insurance. The worksheet also assumes your driving risk is static. It does not adjust for teenage drivers, commercial use, or out-of-state travel frequency. If any of those apply, add at least 50 percent to your bodily injury limits above what the worksheet recommends. Another limitation: state-specific tort structures. In fault-based states the worksheet works as described. In no-fault states you need to layer personal injury protection on top, and the liability limits serve a different purpose — they protect against lawsuits that exceed your PIP threshold. The worksheet alone won't guide you there.
Practical Recommendation
If you are doing this yourself, use the worksheet as a starting point, not a final answer. Run the numbers through an insurance agent's quoting tool to see the premium difference between 100/300/100 and 250/500/100. In most cases the premium increase is between $40 and $120 per year. That is a small amount for coverage that could protect your entire financial profile. Download a blank worksheet from your state's insurance department or any major insurer's website. Fill it out with current figures, not assumptions. Revisit it every three years or after any major life change — marriage, home purchase, new job, child in the car. The numbers shift faster than people expect.