How to Actually Use an Auto Loan Refinance Calculator Without Wasting Your Time
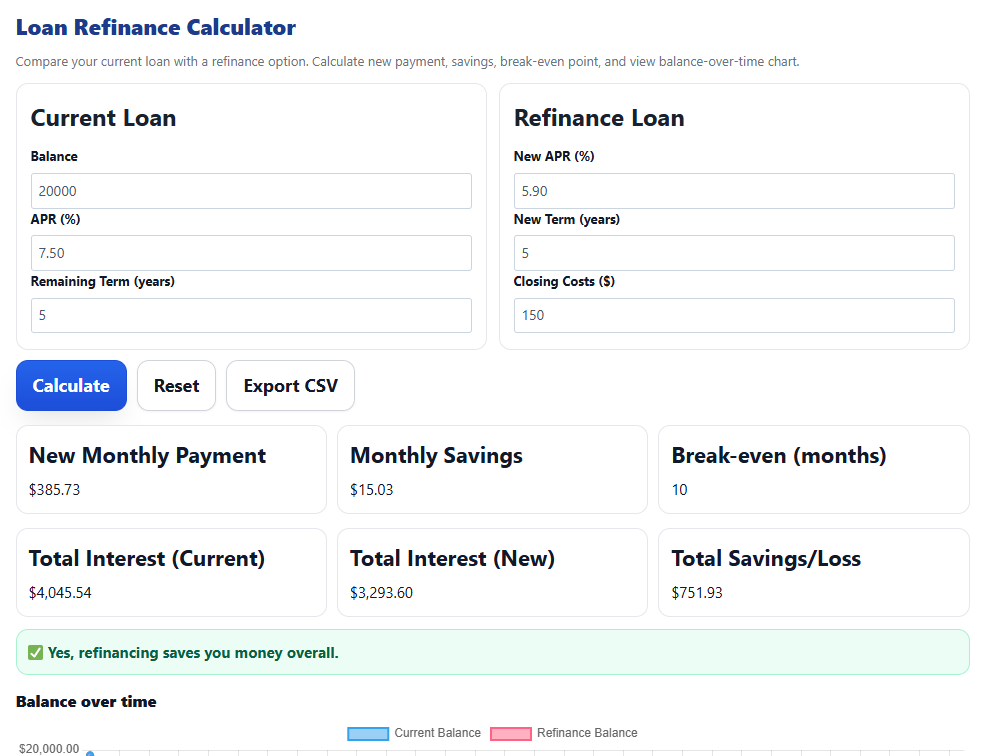
An auto loan refinance calculator takes your current loan details and shows you what your payment would look like at a new interest rate. That's the simple version. The complicated part is making sure the numbers it gives you actually match what a lender will offer, because they almost never do on the first try. Here's the basic method. You need four things: your remaining principal balance, your current interest rate, how many months are left on your loan, and the new rate a lender is offering. Plug those into the calculator and it spits out a new monthly payment plus the total interest you'd pay over the remaining term. Some calculators also show the break-even point, which is how many months it takes for your monthly savings to cover the refinancing fees. Skip the break-even analysis and you'll miss the entire point of refinancing.
Using an Auto Loan Refinance Calculator Correctly
The most common mistake I see is people entering their original loan amount instead of their current remaining balance. If you borrowed $30,000 two years ago but have already paid down $12,000, your remaining balance is $18,000. Put $30,000 in the calculator and the output is completely meaningless. Another frequent error is ignoring the loan term. Lenders will often reset your term back to 60 or 72 months when you refinance, even if you only had 24 months left on your old loan. That means your new payment might look lower, but you're paying interest for years longer. Always check whether the calculator accounts for a renewed term or a shortened one. I ran into a specific problem last year where a borrower showed me a refinance quote that looked great on paper. Her old loan had 18 months remaining at 7.2 percent. The new rate was 5.1 percent. The calculator showed she'd save about $85 a month. But when I dug into the fine print, the lender was rolling her $495 origination fee into the new loan balance instead of charging it upfront. That added roughly $400 to her principal, which ate up half her first year of savings. The workaround was straightforward: I recalculated with the fee added to the new loan balance and the break-even point jumped from 6 months to nearly 18 months. She walked away from the deal. Not every calculator lets you input fees separately, so if yours doesn't, add the fee to the new loan amount manually before you trust the result. There are a few things most people miss about how these calculators work under the hood. First, they assume a fixed-rate loan with a standard amortization schedule. If your current loan is an adjustable-rate product or has a balloon payment, the output is garbage. Second, most calculators don't account for prepayment penalties. Some lenders charge a fee if you pay off a loan within the first few years, and that can completely erase your refinancing benefit. Third, the daily interest calculation matters more than people realize. If your current loan compounds daily rather than monthly, your actual remaining balance might be slightly different from what the calculator assumes, and that shifts your payment by a few dollars here and there.
The real limit of any Auto Loan Refinance Calculator is that it's a projection tool, not a guarantee. Lenders will run their own underwriting, check your credit score at the time of application, and adjust the rate based on factors the calculator can't know. A rate you see quoted today might not be available next week. Credit score changes between now and application day can shift your rate by half a point or more. And if you've missed any payments in the last 12 months, most online calculators won't reflect the penalty that rate adjustment brings. If you're trying to decide whether refinancing makes sense, run the numbers through the calculator, then call at least three lenders and get actual quotes. The difference between a projected estimate and a real offer is usually where people find out they were off by $30 to $60 a month. That's enough to change the decision. Also keep in mind that if your remaining term is under 12 months, refinancing rarely makes financial sense no matter what the calculator says. The fees alone will outpace the interest savings. In that scenario, just pay off the existing loan and move on. One more thing that isn't obvious. If you're underwater on your loan, meaning you owe more than the car is worth, most lenders won't refinance you at all. The calculator might still give you a number, but it won't translate into an actual offer. You'd need to refinance through a program that allows negative equity rollover, and those rates are typically higher than standard refinancing anyway. So the calculator answer and the real-world answer diverge significantly in that case.
Get the Full Details