How Auto Refi Calculator Actually Works in Practice
The auto refi calculator is a tool you'll find on lender websites and financial blogs that estimates your new monthly payment and total interest savings when you refinance your car loan. Most of them look identical on the surface — five input boxes, a calculate button, and a results table. The problem is that the output they give you is often wrong enough to mislead you. I've spent years watching people make refinancing decisions based on numbers that didn't account for real-world fees, negative equity roll-ins, or the way their existing loan amortization was structured. Here's how the basic math works before you even open one. You take your current loan balance, subtract any payoff fees, add the new loan amount if you're rolling costs in, then plug everything into the standard amortization formula. The new monthly payment is (New Principal × Monthly Rate) / (1 - (1 + Monthly Rate)^(-Remaining Months)). That's it. It's not magic. A decent Auto Refi Calculator automates this so you don't have to do it by hand, but knowing the formula matters because most online tools skip steps that change the result by hundreds of dollars.
Using an Auto Refi Calculator Correctly
I keep a spreadsheet for every refinancing I evaluate now. When I was just starting out, I relied entirely on the calculators lenders provided on their landing pages. Big mistake. The ones on lender sites are designed to make the refinance look better than it actually is. They don't include origination fees, prepayment penalties on your current loan, or the possibility that your credit score at application time could be lower than what you used in the estimate. Here's what I do instead. First, pull your current loan payoff statement from your lender. Don't use the balance shown in your online portal — it's usually a day or two behind, and some lenders add daily accrual adjustments that change the actual payoff number. The payoff statement has the exact amount you owe today, including any accrued interest and fees. That's your starting point. Next, get rate quotes from at least three lenders. I mean actual quotes with the interest rate locked in writing, not the teaser rate on the homepage. The rate you see advertised is almost never the rate you'll qualify for unless you have exceptional credit and a short loan term already. When I was refinancing my own vehicle a few years back, the calculator on BankA's site showed me a payment of $312 per month at 4.2%. The actual quote came back at 6.8% because my debt-to-income ratio was higher than I'd estimated. The difference between those two rates was $47 a month — $2,350 over a five-year loan. That gap wiped out any meaningful savings from refinancing.
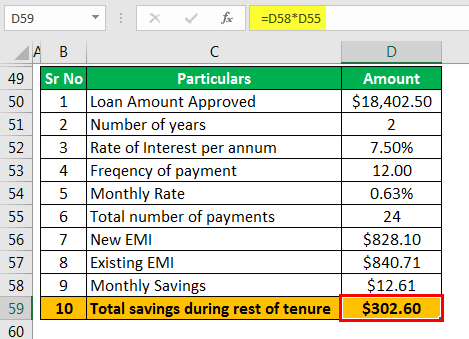
Input your current loan details accurately. Balance, remaining term, interest rate, and monthly payment. Then input the new loan offer details. Compare the two side by side. But here's where most people miss the critical part — you have to factor in closing costs. Origination fees, title transfer fees, lien recording fees. These typically run $200 to $600 total. If your monthly savings are only $30, you're looking at a 8-to-20-month break-even period before you actually start saving money. The calculator won't tell you this unless you manually add those costs in. One specific edge case that trips people up constantly: rolling negative equity into your new loan. Say you owe $18,000 on your current car loan but the car is only worth $15,000. You're $3,000 underwater. Some lenders will let you refinance anyway by adding that $3,000 to your new loan balance. The calculator might show you a lower monthly payment because the new interest rate is lower, but you're now paying interest on a larger principal over a longer term. I ran this scenario for a client last year — the calculator showed $28 in monthly savings. Over the life of the loan, she paid $1,840 more in total interest because the principal was inflated and the term stretched from 36 months to 60. The refi saved her nothing. It made things worse. Another thing calculators rarely account for properly is the reset of your amortization clock. When you refinance a 36-month loan with 24 months remaining into a new 60-month loan, you're extending your total debt obligation significantly. Even at a lower rate, the total interest paid can exceed what you would have paid keeping the original loan. The monthly payment drops, sure, but so does your equity buildup. This is counter-intuitive for most people who focus only on the payment reduction and ignore the total cost picture.
Get the Full Details
The real limitation of any Auto Refi Calculator is that it operates on assumptions. It assumes your credit score hasn't changed since you applied. It assumes no prepayment penalties exist on your current loan. It assumes the car's value hasn't dropped further. It assumes you'll keep the new loan for the full term. When any of those assumptions breaks, the numbers fall apart. I've seen people refinance based on a calculator estimate, then discover their current loan had a 2% prepayment penalty that erased the entire benefit. Or they found out the lender required a minimum credit score that they no longer met after a recent credit inquiry spiked their utilization. If you want a reliable estimate, use a calculator as a first step, not the final word. Get your actual payoff figure, collect real rate quotes, add in all fees, and run the numbers through the amortization formula yourself. The calculation takes about 15 minutes once you have the documents. The lender calculators save you maybe 5 minutes and give you a number that could be off by $50 to $150 per month depending on how they handle fee inclusion and rate assumptions. That margin of error is enough to make a bad decision look good. There are also situations where refinancing simply isn't viable. If your remaining loan term is under 12 months, the savings from a lower rate rarely justify the closing costs. If your credit score has dropped since you took out the original loan, you may not qualify for a better rate. If your vehicle is older than 10 years or has over 120,000 miles, most lenders won't refinance it at all, or they'll offer rates higher than your current loan. I don't recommend running a calculator for these scenarios — you're just going to waste time. Check eligibility criteria with the lender first before you invest any effort.
The bottom line is that these calculators are useful for ballpark estimates but dangerous if treated as definitive. They're screening tools, not decision tools. Use them to identify whether refinancing is worth pursuing, then do the detailed math with actual numbers from your loan documents and real quotes. That's the only way the result will match what actually happens when you sign the paperwork.