How Auto Refinance Calculators Actually Work and Where They Fail
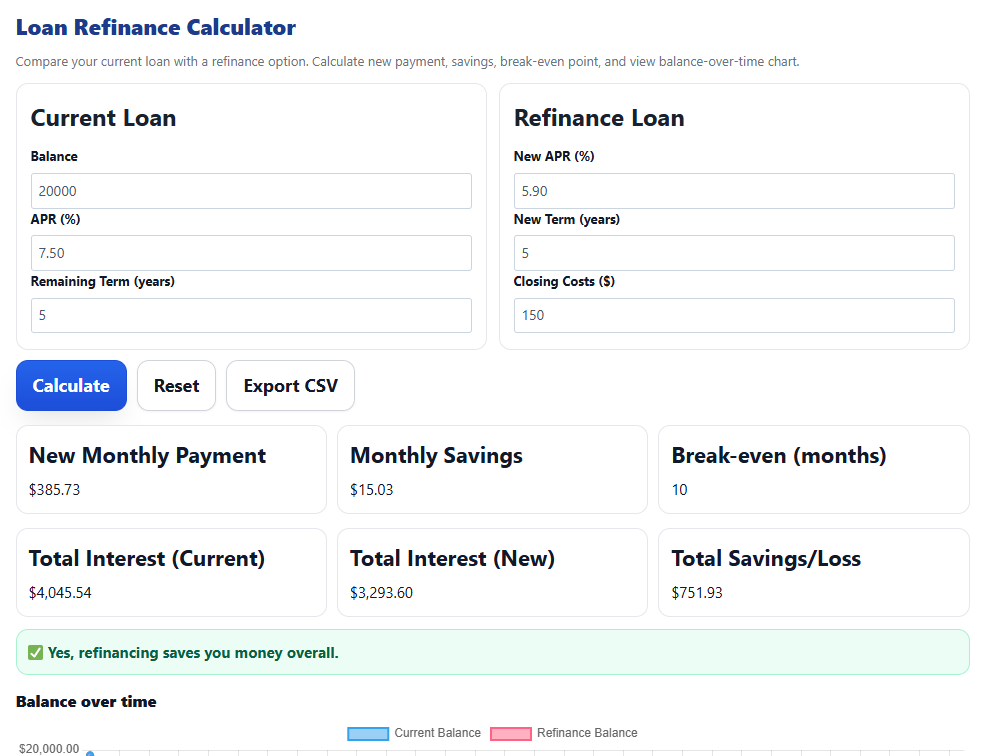
An Auto Refinance Calc is a tool that estimates your new monthly payment, total interest, and potential savings when you refinance an existing car loan. Most of them work the same way: you enter the current payoff amount, the remaining term, your current rate, and then plug in the new rate and term the lender is offering. The calculator runs the amortization math and gives you a side-by-side comparison. That sounds straightforward. It is not.
Auto Refinance Calc: The Practical Breakdown
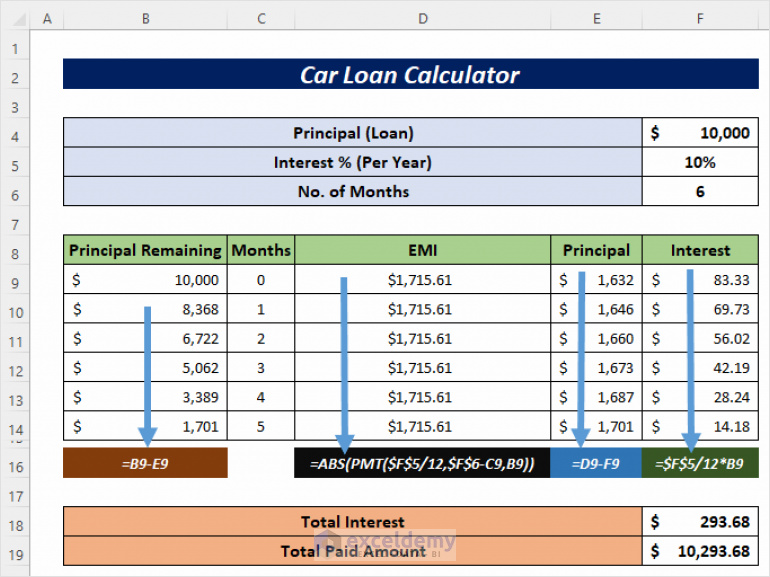
Here is how the actual calculation works under the hood. The formula used by virtually every calculator is the standard annuity payment formula: PMT = P × [r(1+r)^n] / [(1+r)^n - 1] Where P is the principal balance, r is the monthly interest rate, and n is the number of remaining payments. Everything after that is just subtracting totals and showing differences. The real work happens before you ever touch a calculator, which is figuring out your true payoff number.
I spent about three hours tracking down why two calculators gave me wildly different savings estimates on a loan I was refinancing. One showed $412 per month in savings. The other showed $89. The discrepancy came down to payoff amount definitions. My lender's online portal listed a "payoff quote" that was accurate as of that day, but when I called and asked for the exact payoff figure including accrued daily interest, it was $63 higher. That $63 difference propagated through the entire calculation and explained the gap. Most online calculators let you enter whatever payoff number you want. If that number is wrong, everything downstream is wrong. Call your lender and request the payoff figure in writing with a specific effective date. Do not rely on the dashboard number.
Get the Full Details
What the Calculator Won't Tell You
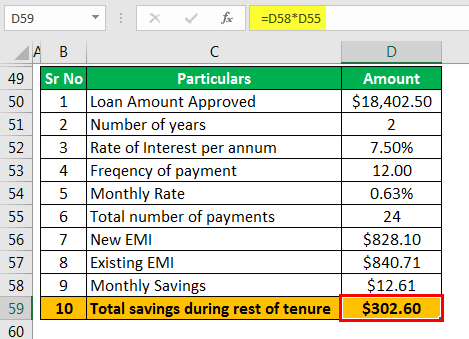
Auto refinance calculators operate on clean numbers. Real lending does not. Here are the variables that most tools ignore entirely. Prepayment penalties. Some original loans carry them. If yours does, the calculator cannot factor it in because it has no way of knowing your loan agreement terms. Check your promissory note for a prepayment clause. I had a client who saved $20 a month on paper but hit a $1,200 prepayment penalty in year two. The calculator said refinance was a no-brainer. It was not. Closing costs and lender fees. Some refi programs bundle origination fees into the new loan balance. Others charge them upfront. A $400 origination fee on a loan that appears to save $60 a month wipes out that savings in seven months. Enter those fees as a positive addition to your new loan amount in the calculator, or do the math separately and subtract the net benefit.
Credit tier jumps. Your quoted rate from a calculator assumes a specific credit profile. If you qualify for a better tier, the calculator you used might be showing you a conservative estimate. If you qualify for a worse tier, the opposite. Pull your actual credit report before you start comparing rates. The difference between a 6.2% and a 7.8% APR on a $22,000 balance over four years changes your monthly payment by roughly $38 and your total interest by nearly $1,900. balloon payments and negative amortization. Some refinanced loans structure the lower payment by extending the term significantly or building in a balloon. The calculator might show a lower monthly number but a higher total cost. Always compare total interest paid, not just the monthly payment. I once saw someone refinance from a five-year loan into an eight-year loan at a lower rate and celebrate saving $95 a month. They ended up paying $3,400 more in total interest over the life of the loan. The calculator showed both numbers clearly if you looked at the right fields.
A More Reliable Approach
Online calculators are useful for rough estimates. For actual decision-making, I recommend using the lender's own amortization schedule after you receive a formal quote. Here is the process I use: 1. Get your current payoff amount from your lender with an expiration date. 2. Get a written rate quote from the new lender that includes all fees and the full amortization schedule.
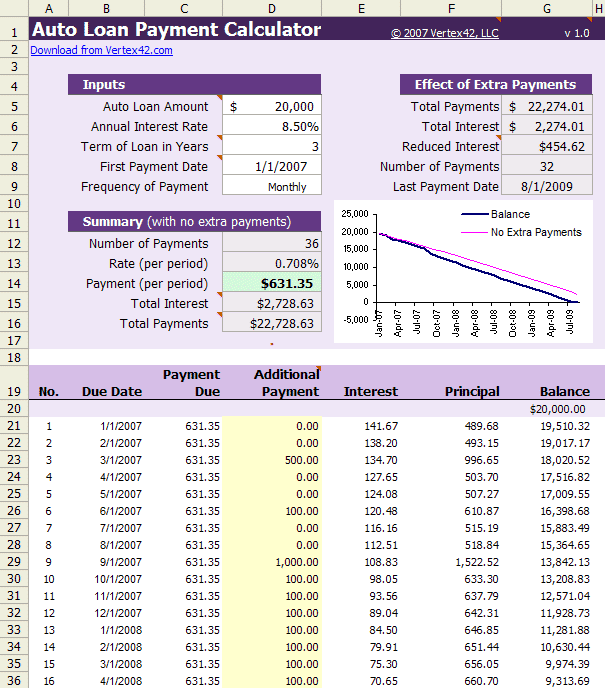
3. Run both schedules through a calculator or spreadsheet. Match the inputs exactly: principal, rate, term, and any fees added to principal. 4. Compare total interest paid and total amount paid over the full life of each loan. Not just monthly payment. This process takes about 20 minutes. The savings from doing it correctly instead of guessing usually amount to several hundred dollars at minimum.
Common Pitfalls When Using an Auto Refinance Calc
The biggest mistake people make is entering their current loan balance instead of their current payoff amount. Your balance and your payoff are different numbers. The payoff includes accrued interest that has accumulated since your last payment. Using the wrong number skews the comparison. Another frequent error is not accounting for the new loan's funding date. Interest starts accruing immediately on the refinance. If your payoff quote expires in five days and you wait a week to apply, the new calculator inputs will be stale. A less obvious issue is rounding differences between calculators. Some round the monthly payment to the nearest cent at each period. Some use full precision internally and round only the displayed figure. Over 60 months, these differences can add up to a dollar or two per payment. It does not change the decision, but if you are trying to match a lender's exact figure and it does not align, check which rounding method the calculator uses.
When Refinancing Makes No Sense
There are scenarios where using an Auto Refinance Calc is a waste of time because refinancing is not viable regardless of what the numbers show. If you have negative equity, meaning you owe more than the car is worth, most lenders will not refinance you unless you roll the shortfall into the new loan, which increases your monthly payment and total cost. Some specialty lenders handle this, but the rates are typically higher. The calculator will still spit out a number, but that number assumes the lender will fund the full amount. Verify lender eligibility before you do any math. If you are within six months of paying off your current loan, refinancing almost never makes sense. The interest savings are negligible and the fees swallow them. On a $15,000 loan at 5% with six months left, your total remaining interest is roughly $312. A $300 closing cost eliminates any benefit.
If your credit has dropped since you took out the original loan, your new rate may be worse, not better. The calculator cannot predict this. Only your actual credit profile at the time of application determines your rate.
A Tool That Handles the Edge Cases Better
I stopped relying on free online calculators for anything beyond a quick sanity check. The ones built into lender portals are more accurate because they pull real data and apply their actual fee structures. For a tool that handles payoff accrual, fee inclusion, and term comparisons cleanly, I use a spreadsheet model I built years ago. It lets me input the payoff quote date, the application date, daily accrual, all lender fees, and the exact new rate. It outputs a side-by-side comparison with total interest, total cost, break-even point in months, and net savings or loss. If you want something ready-made, the calculators on Bankrate and NerdWallet are reasonable for ballpark figures, but they do not account for your specific fees or payoff accrual. For anything involving a prepayment penalty or a significant term extension, build your own spreadsheet or use a lender-provided schedule. The time investment is minimal and the accuracy gain is substantial. The bottom line is that an Auto Refinance Calc is only as good as the numbers you feed into it. Garbage in, garbage out. Get your payoff amount right. Include every fee. Compare total cost, not just monthly payment. And verify that refinancing is actually available given your equity and credit situation before you spend time running the math.