How an Auto Refinance Calculator Actually Works in Practice
A lot of people treat these calculators like they're magic boxes that spit out a decision for you. They're not. They're arithmetic engines. You feed them numbers, they return numbers. The whole thing boils down to comparing your current payment structure against a new loan offer with different terms. That's it. What happens next is where people make mistakes. Here's how I approach it. Pull up your current loan statement — not the app summary, the actual monthly statement showing principal balance, interest rate, remaining term, and payment amount. Then get the new rate quote you're considering. Run both through the calculator side by side. Don't trust the first result you see. Run it twice with slightly different assumptions to see how sensitive the output is to changes in rate or term length.
Using an Auto Refinance Calculator Correctly
The calculator needs five inputs at minimum: current loan balance, current interest rate, remaining months on your loan, the new offered rate, and the new loan term. Most calculators will also let you plug in prepayment penalties, origination fees, and closing costs. If yours doesn't ask about fees, it's giving you an incomplete picture. Let me give you a specific scenario that trips people up. I was helping someone compare a refinance offer last year. The calculator showed a lower monthly payment and a savings of about four hundred dollars per month. Sounded great. But the new loan was thirty-six months instead of twenty-four remaining on the original. When I added up total interest paid over the full life of each loan, the refinance actually cost more by roughly eight hundred dollars because extending the term dumped a lot of interest into later payments. The calculator told the truth, but the truth it told was misleading without looking at total cost, not just monthly payment. This is the counter-intuitive part most beginner guides skip. A lower monthly payment does not equal savings. It often equals more total interest. The calculator will show you both numbers if you enter everything correctly, but you have to know to look at the total interest figure. Most people stop reading at "new payment: $287/month." They celebrate and sign the paperwork. Don't do that.
Another thing nobody talks about enough: prepayment penalties on your existing loan. Some lenders charge a fee if you pay off a chunk of your balance early. It's usually calculated as a percentage of the remaining balance or a set number of months of interest. If your current loan has one, the calculator won't know unless you tell it. I've seen people miss a two thousand dollar prepayment penalty because their calculator didn't have a field for it, and the refinance deal looked profitable until the first payment statement arrived. Here's what most people don't realize about how these calculators model your situation. They assume you'll make every payment on time, every month, for the entire loan term. They don't account for the possibility that you'll pay extra toward principal or that you'll miss a payment and get hit with late fees. The calculation is theoretical. Your actual results may diverge. There's also the issue of credit score changes between when you check rates and when you actually lock a refinance. Calculators use the rate you type in. If you shop around and your score drops because of hard inquiries, your actual rate could be higher than what the calculator showed. It's a small effect in most cases, maybe a quarter to half a percent, but it matters when you're trying to decide between two marginal offers.
Get the Full Details
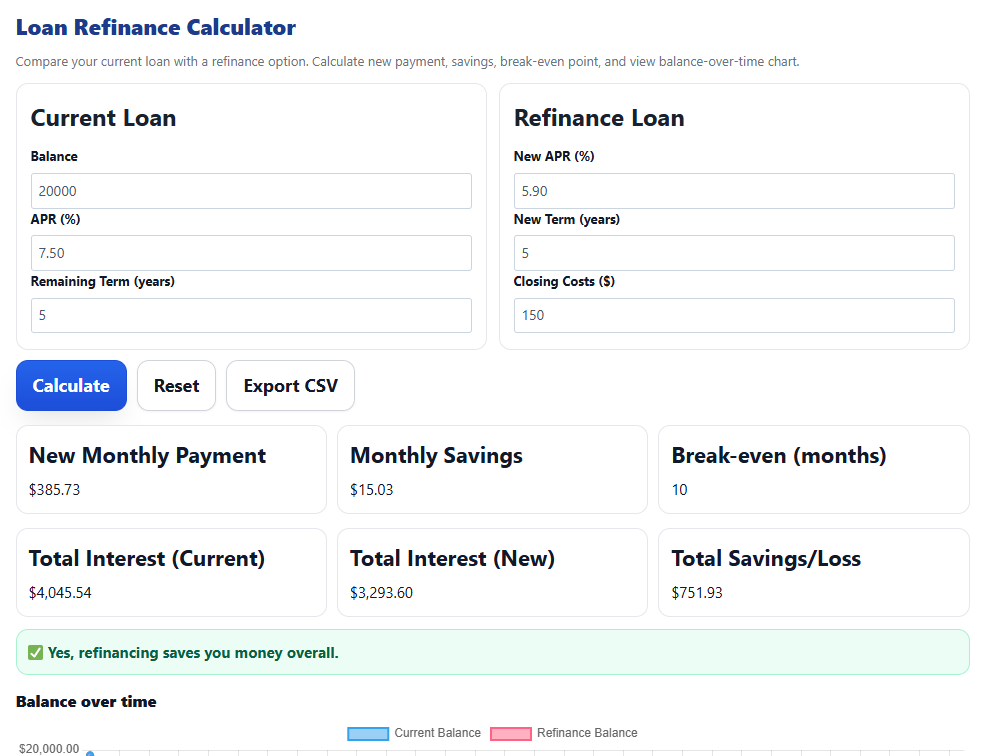
Workaround for the edge case I mentioned: After my friend's experience, I started doing a manual spreadsheet calculation alongside the calculator results. I'd lay out the amortization schedule for both loans month by month, including any fees upfront. This takes about twelve minutes and catches scenarios where the calculator's summary numbers hide the real cost. If you're serious about getting this right, build the schedule yourself rather than relying on the calculator's summary output alone. There are definitely situations where a calculator gives you useful direction and situations where it's basically noise. If your current rate is below four percent and your credit profile hasn't changed, the calculator might show a negligible difference between your current loan and available refinance offers. In that case, the math says "don't bother," and the calculator is accurate. Running it anyway wastes time and might give you a false sense that a decision needs to be made. Conversely, if you're in the market for a longer-term loan to reduce monthly obligations, or your credit has improved significantly since you took out the original loan, the calculator becomes much more useful. The numbers diverge enough that you can actually see a path forward. The tool shines when there's a real gap between your current terms and what's available now.
One more practical note on timing. Most lenders let you check rates with a soft credit pull before you commit to anything. This is free and doesn't affect your score. Do this first. Run the numbers through the Auto Refinance Calculator with the rates you get back. Only then should you proceed with a hard inquiry and formal application. I've watched people skip straight to the application and waste a hard pull on an offer that didn't pan out once the calculator numbers were actually examined. The calculator itself is free to use and usually available on lender websites or independent financial sites. Some charge nothing. Others want you to fill out a lead form before they show results. That's a sales tactic, not a barrier to entry. Keep that in mind when you're browsing. I'll stop here. The tool works when you use it correctly. It misleads when you read only the headline numbers. The difference between those two outcomes is usually about five minutes of looking at total interest cost and checking for fees that the calculator might not surface on its own.