How to Actually Use an Auto Refinance Estimator Without Getting Fooled
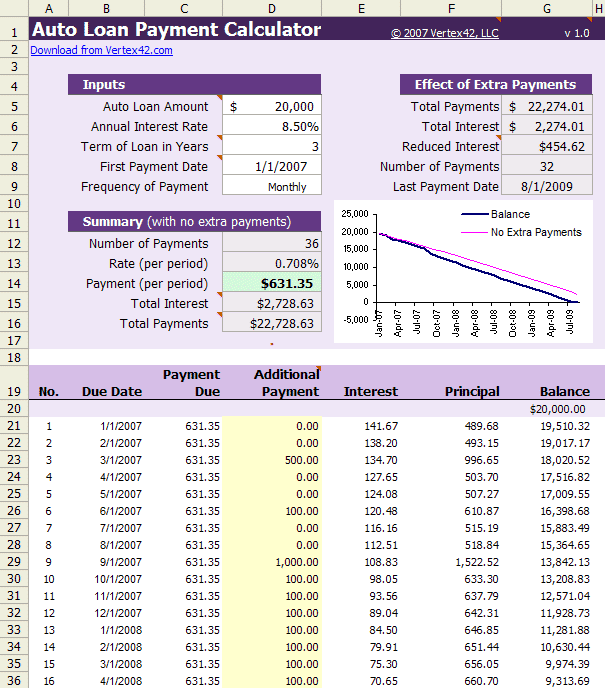
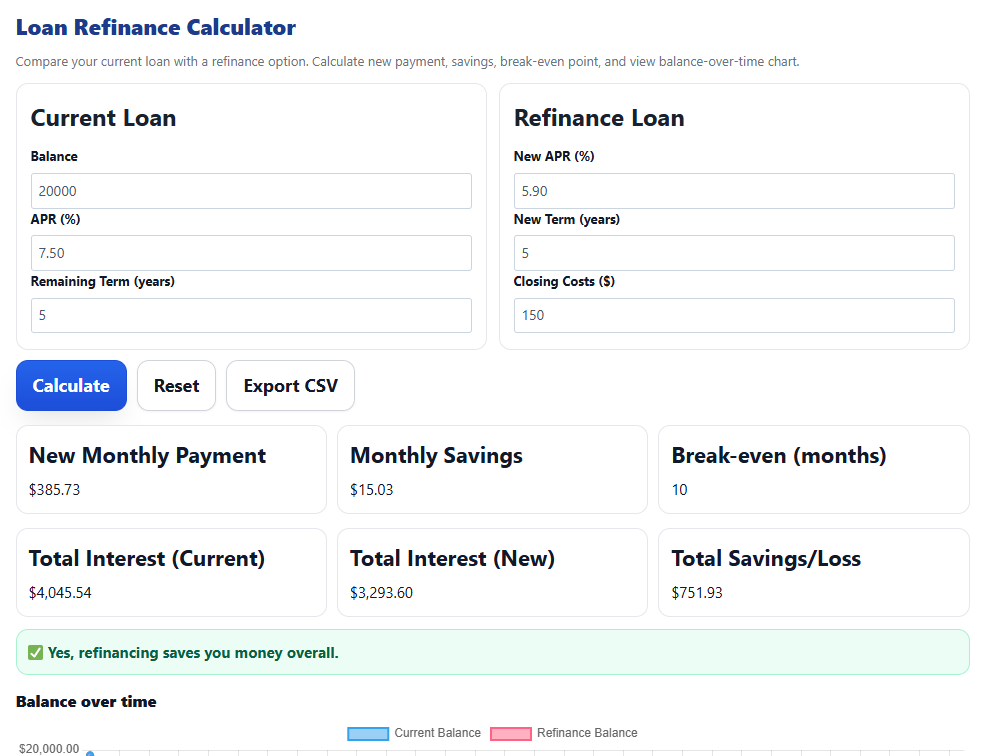
Most people treat auto refinance calculators like magic 8-balls. They punch in numbers, get a monthly payment, and decide whether to refinance based on that single figure. That's not how it works in practice. An Auto Refinance Estimator is just a tool that models what your loan could look like under different terms, and the difference between a useful estimate and a misleading one comes down to how carefully you feed it data. An auto refinance estimator takes three main inputs: your current loan balance, your current interest rate, and your remaining term. It then compares that against new loan offers—typically a lower rate, a different term length—to show you the projected new payment, total interest paid over the life of the new loan, and total savings. Some estimators also factor in closing costs or origination fees, but not all of them do, and that omission matters more than most people realize. I've seen too many folks click "refi" based on a calculator showing $45 in monthly savings without checking whether the estimator included fee assumptions. One lender's "no fees" offer might actually bake a $295 origination charge into the rate. Another might advertise a rate that's only available to borrowers with 800+ credit scores. The estimator doesn't know that. You have to.
Getting Accurate Numbers Out of the Tool
Start with your payoff amount, not your original loan balance. If you borrowed $28,000 three years ago, your current principal is probably closer to $19,400 depending on how much you've paid down and whether you rolled taxes and fees into the loan. Check your latest statement or call your lender and ask for the exact payoff figure. The estimator will round this number differently depending on whether you're using a generic online calculator or one from a specific refinancing lender. For the interest rate portion, pull your current rate from your loan documents. Not the APR. The note rate. APR includes fees and other costs that the refinance calculator won't account for when it's comparing rates side by side. Using APR instead of your actual interest rate throws off the comparison by roughly 0.25 to 0.5 percent, which sounds small until you're looking at a $20,000 balance over four years. There's a specific edge case that catches a lot of people. If you're underwater on your current loan—meaning you owe more than the car is worth—most standard estimators will either give you a result or silently fail. I ran into this last year with a client who owed $14,200 on a car valued at roughly $11,800. The online estimator spat out a clean new payment of $312, which looked attractive compared to her current $410. But no lender would refinance that gap. The workaround was to calculate her equity position first, determine whether she could roll negative equity into the new loan (which most won't do without a large down payment), and only then run the refinance numbers. She ended up waiting six months, making extra principal payments, and then refinancing once she had $1,500 in equity. The new rate dropped from 7.9% to 5.4%, and her payment went from $410 to $338—not as dramatic as the first estimator suggested, but still meaningful.
What the Estimator Isn't Telling You
The biggest gap in most auto refinance estimators is that they don't account for prepayment penalties on your existing loan. Some lenders still charge these, usually structured as a percentage of the remaining balance or a flat fee if you pay off the loan within the first two to three years. If your current loan has one, that cost gets wiped out by refinancing, and the estimator won't subtract it from your projected savings unless you enter it manually. Another thing that's rarely modeled: the impact of extending your loan term. A lower rate stretched over a longer period might drop your monthly payment by $60, but you could end up paying thousands more in total interest over the full life of the loan. An estimator that shows only the new monthly payment without the total cost breakdown is giving you an incomplete picture. Look for tools that show total interest paid across both scenarios, or calculate it yourself using the formula: Total interest = (new monthly payment × new term in months) original loan amount minus any fees.
Get the Full Details

Credit score changes also matter. If your score has improved since you took out the original loan, you'll qualify for better rates. But if it dropped—even by a small amount—you might see a rate increase that erases the benefit of refinancing. Most estimators assume your current credit profile stays constant, which is a reasonable assumption if your score hasn't changed recently, but not if you've had recent delinquencies, new hard inquiries, or major account closures.
When an Auto Refinance Estimator Actually Helps
The tool is most useful in three scenarios: when rates have dropped significantly since you locked your current loan, when you've improved your credit profile enough to qualify for a better tier, or when you want to shorten your term and pay off the loan faster without increasing your monthly burden. It's less useful if you're near the end of your loan term—refinancing with two years or less remaining rarely makes sense because the interest savings are too small to offset any fees involved. I recommend running the numbers through at least two different estimators before making a decision. One from a major lender, one from an independent comparison site. If they agree within $10 or so on your projected payment, you're in a reasonable position to move forward. If they diverge significantly, that's a sign to dig into why—one of them is likely excluding costs or using different assumptions.
Download and Access
If you want a reliable Auto Refinance Estimator to work with, there aren't many standalone downloadable tools that are worth the effort. Most people are better served by using the calculators built into lender websites or comparison platforms, since those reflect current market rates in real time. The ones you find as spreadsheets or apps tend to become outdated quickly and don't pull live rate data. That said, a well-structured Excel template can be useful for side-by-side comparisons if you already have multiple quotes in hand and want to model different scenarios without re-entering data each time. The bottom line is that an auto refinance estimator is a starting point, not a decision tool. It gives you a directional answer, but the actual decision requires checking your current payoff amount, your credit score, any existing loan penalties, and the total cost of the new loan—not just the monthly payment. Take the time to verify those numbers before you commit, and you'll avoid the common pitfalls that make refinancing feel like a gamble instead of a straightforward financial move.