Understanding What Average Mortgage Length Actually Means
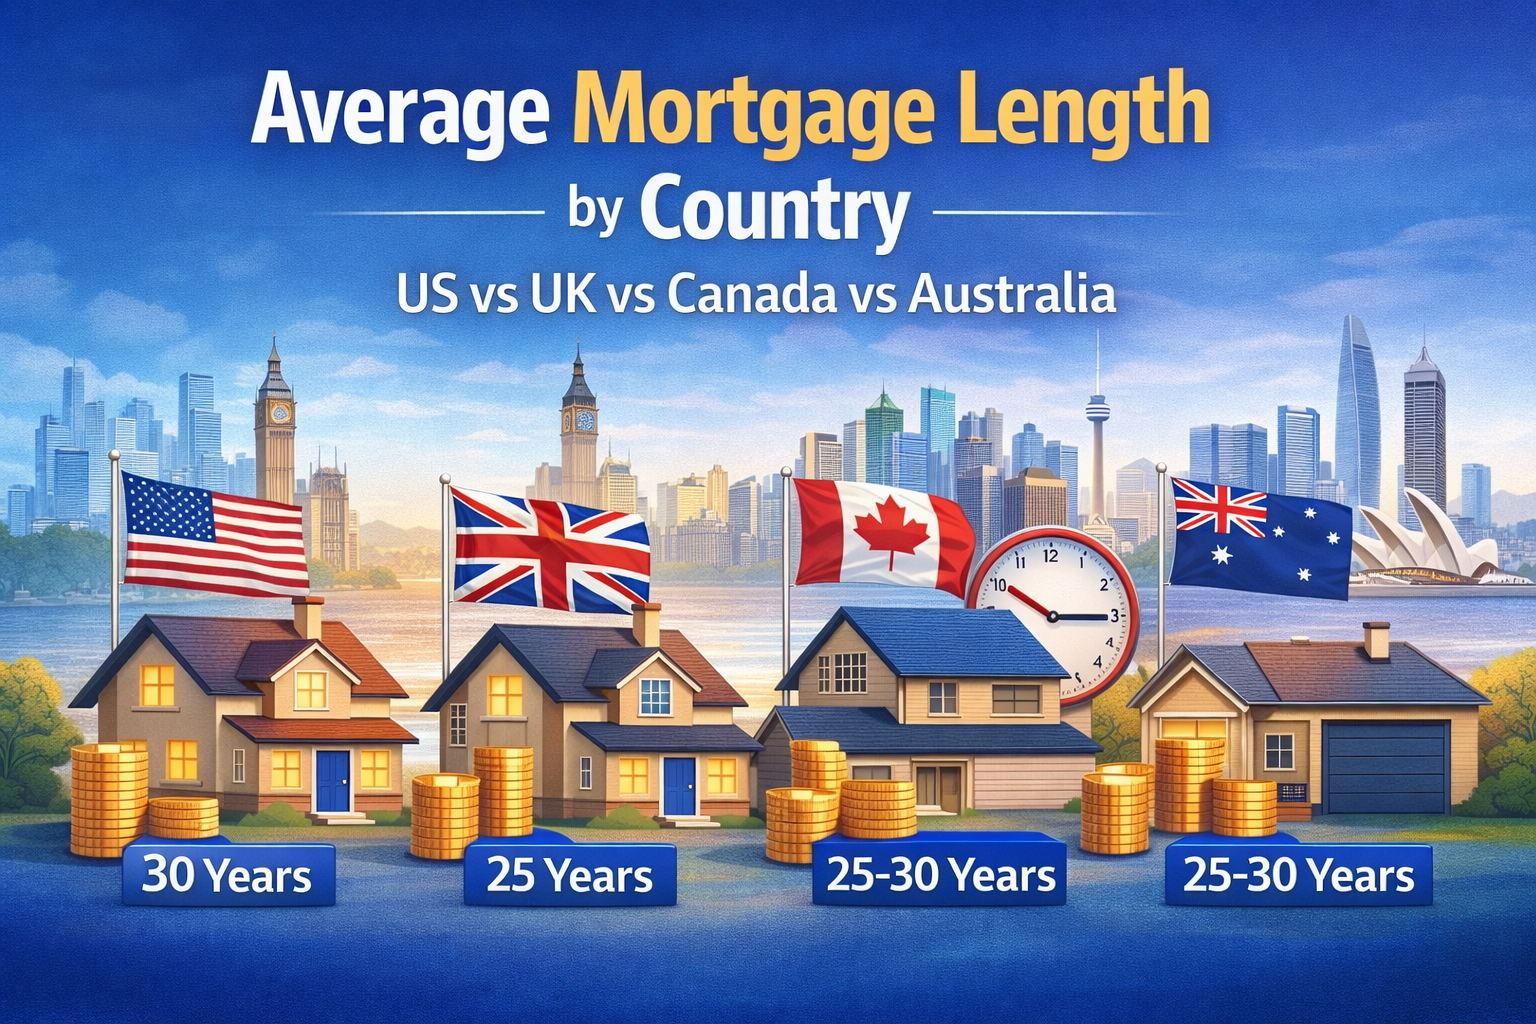
The average mortgage length in the United States sits around 30 years for newly originated loans, though that number has been drifting slightly downward over the past decade as more borrowers opt for 15-year terms when they can qualify. What matters far more than the advertised term, though, is the actual average time it takes people to pay off their mortgages end to end, which runs closer to 10 to 12 years before refinancing or selling interrupts the schedule. I spent years working mortgage underwriting and servicing, and one thing that always came up in conversations with borrowers was confusion about what the loan term actually meant versus how long they would realistically carry the debt. People sign a 30-year note and then sell the house five years later without fully grasping that the amortization schedule was calculated on the assumption they would hold the loan for three decades. That mismatch between expectation and reality is where a lot of financial stress comes from.
How Average Mortgage Length Impacts Your Total Cost
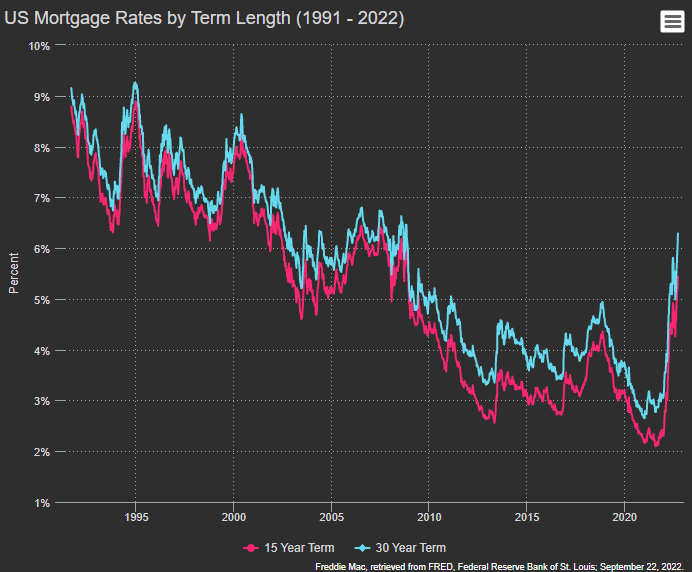
The core mechanic here is simple but easy to overlook: a 30-year mortgage at 6.5% interest on a $300,000 loan costs roughly $363,000 in total interest over the life of the loan, while a 15-year mortgage at 5.75% on the same amount costs about $139,000 in interest. The monthly payment on the 15-year is significantly higher, which is why many borrowers default to the longer term, but the interest differential is massive. You are essentially paying 2.6 times more in interest by choosing the 30-year path. Here is something most calculators do not make clear: the majority of your interest in a 30-year mortgage is front-loaded. In the first five years, you might pay $65,000 to $70,000 in interest while only reducing your principal by $20,000 to $25,000. That is the single biggest trap I saw borrowers walk into repeatedly. They assumed early payments were building equity at a reasonable rate, and they were not. The first decade of a 30-year loan is mostly interest, and if you plan to sell or refinance within that window, the longer term offers almost no advantage over a shorter one except for keeping your monthly payment lower. I had a client once who refinanced from a 30-year into another 30-year because she could not afford her payments after a job change. She did not realize she was restarting the amortization clock almost entirely. She was five years into her original loan, had paid down maybe $30,000 in principal, and the new loan wiped that progress nearly clean because the first years of the new loan again went almost entirely to interest. It took her another eight years to get back to the equity position she would have had if she had just kept the original loan and cut expenses elsewhere instead. That is a realistic, unglamorous example of how average mortgage length interacts with life events in ways that are not obvious on paper.
Practical Ways to Shorten Your Mortgage Term
The most straightforward method is to switch to a 15-year mortgage if your income supports the higher payment. But there are several partial strategies that work just as well for people who need the lower monthly outflow of a 30-year loan. Bi-weekly payments are one option where you pay half your monthly amount every two weeks instead of the full amount once a month. Because there are 26 bi-weekly periods in a year, you end up making 13 full payments instead of 12. On a 30-year loan at 6.5%, this can shave roughly five to six years off the payoff period and save $30,000 to $40,000 in interest depending on the loan size. Many servicers offer this automatically, but you can also set it up yourself by dividing your monthly payment by two and scheduling the payment every fourteen days. Rounding up to the nearest hundred is another low-effort approach. If your payment is $1,847, you round to $2,000. That extra $153 per month goes entirely to principal after the first year, and over time it compounds meaningfully. It is not dramatic, but it is sustainable because the adjustment is small enough that most people do not notice it in their budget.
Get the Full Details
Extra principal-only payments are the most flexible route. Any lump sum you throw at the loan — a tax refund, a bonus, inheritance money — reduces the balance directly and recalculates the remaining amortization. Most modern servicers allow this without penalty, but you need to confirm that the lender does not charge a prepayment penalty and that your extra payment is explicitly applied to principal rather than being held as escrow or applied to the next monthly installment. I have seen both happen, and neither is helpful if you intended to pay down the balance faster.
When a Longer Mortgage Length Makes Sense
Thirty-year mortgages are not a bad product. They are a tool, and like any tool, they have appropriate use cases. If you are in your thirties or forties with a moderate income and you expect your earnings to rise over the next decade, a 30-year loan gives you the breathing room to invest the difference elsewhere. The opportunity cost of locking extra cash into home equity at 6.5% is real if you could earn a higher return in a diversified investment portfolio. That comparison is the honest way to evaluate whether a longer term is working for you or against you. There is also the cash flow stability argument. A 30-year fixed mortgage locks your housing payment for three decades, which is rare in personal finance. Rent increases, car payments, and credit card minimums all creep upward over time. A fixed mortgage payment does not. That predictability has tangible value for household budgeting, especially in volatile economic environments where income disruption is a realistic possibility. I worked with a borrower in his early fifties who chose a 30-year over a 15-year because he had just started a business and income was unpredictable. He knew the interest cost would be higher, but the lower payment gave him a cushion that saved him from having to draw down retirement accounts during a slow quarter. He ended up paying off the loan in eleven years by making accelerated payments once the business stabilized. The longer original term bought him optionality, and that optionality turned out to be worth more than the extra interest cost.
Common Pitfalls Around Mortgage Length
One mistake I see constantly is borrowers focusing exclusively on the monthly payment without reading the loan estimate details. Lenders are required to disclose the loan term, interest rate, total interest cost, and estimated payoff date, but most people glance at the payment number and move on. If you only look at the payment, you might accept a 30-year loan when a 20-year would cost you only $75 more per month and save you $40,000 in interest. The $75 difference is often negligible in a household budget but the interest savings are not. Another pitfall is assuming that refinancing to a shorter term is always the right move. A 30-year to 15-year refinance resets closing costs, extends the time until the loan is paid off from the refinance date, and may require a higher credit score or debt-to-income ratio than you currently meet. I had a situation where a borrower refinanced from a 30-year at 7% into a 15-year at 5.5%, only to discover that the closing costs of approximately $4,500 plus the loss of equity from resetting the amortization meant she would not break even for six years. She then lost her job nine months later and had to refinance back to a 30-year under worse conditions. The move looked good on a calculator but failed in practice because the timeline and risk factors were not accounted for. Escrow shortages are a quieter issue connected to mortgage length. Longer-term loans mean more years of property tax and insurance fluctuations, and Servicers adjust escrow payments annually based on current costs. If your taxes rise by $200 a year, your monthly payment goes up by about $17. Over thirty years, those adjustments compound, and the payment you qualified for originally is no longer accurate. This is normal, but it is easy to miss if you are not reviewing your annual escrow statements carefully.
The Real Average Is Not What You Think
If you are looking at average mortgage length as a planning figure for your own finances, the number you should keep in mind is not 30 years. It is somewhere between 7 and 12 years of actual ownership before the property is sold or refinanced. The median homeowner in the US stays in a home for about nine years, and that reality should shape how you evaluate any mortgage decision. A 30-year loan is structured on an assumption that rarely holds, which means your actual interest cost will be lower than the full amortization schedule suggests, but so will your equity buildup during the early years if you sell sooner than expected. The most useful thing you can do is run the numbers for your specific situation using your actual expected timeline, not the full loan term. Plug in the interest rate, the monthly payment, your expected ownership period, and any extra payments you plan to make. The result will be closer to reality than the standard calculator output, which assumes you hold the loan to maturity. That adjusted view is what actually matters when you are deciding between a 15-year and a 30-year, or when you are figuring out whether an extra payment strategy is worth the effort. Average Mortgage Length is a useful reference point, but it is not a destiny. The term you choose, the payments you make above the minimum, and the length of time you actually own the property are the variables that determine your real outcome. Everything else is noise.