What You Actually Get When You Pull a Background Check Credit History
A background check that includes credit history is standard practice in hiring, tenant screening, and lending. The consumer report you receive shows payment behavior, outstanding balances, account age, and public records like bankruptcies. It does not show your actual credit score unless you pull that separately. The FICO or VantageScore number lives on a different track. You will see the data points that built that number, but not the number itself from a standard background check package. Here is the workflow most people skip and then regret. Start by determining your permissible purpose. Under the FCRA, you cannot pull a consumer report for just any reason. Employment screening requires a covered purpose. Tenant screening requires a covered purpose. A casual curiosity request is not covered and can expose you to liability. Register with a Consumer Reporting Agency. Equifax, Experian, and TransUnion all offer screening services, but they also sell to resellers. If you go through a third-party vendor like Checkr, GoodHire, or HireRight, make sure they are an FCRA-compliant consumer reporting agency or are using one as their source. The paper trail matters more than you think when someone disputes a decision.
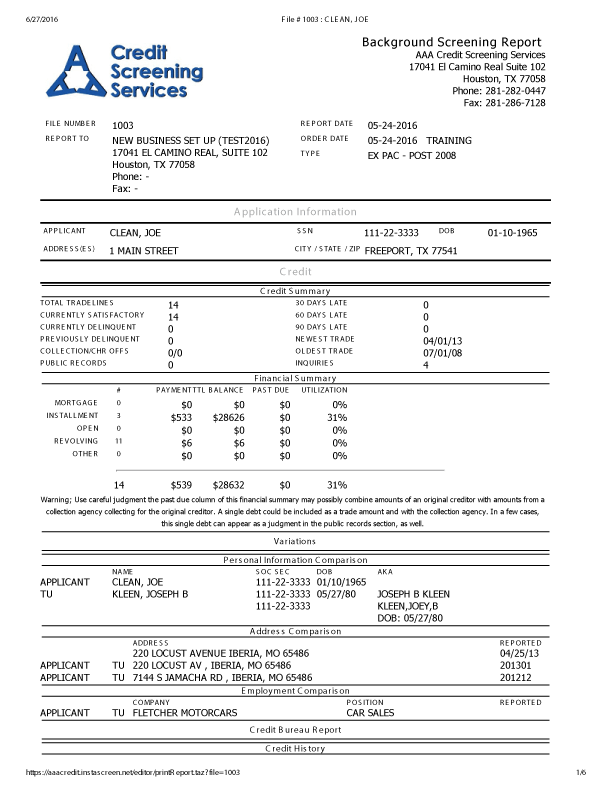
Collect the candidate or tenant's full legal name, current address history, and date of birth at minimum. A missing middle initial will cost you nothing upfront but will cost you time when the match comes back low-confidence. Some agencies require a SSN for pure credit-based screening. Ten-minute turnaround is realistic for clean identities. Expect two to three business days if you have addresses that don't line up cleanly or if the person has a common name like James Smith or Maria Garcia with multiple possible matches. Once the report is ready, review it before taking any adverse action. The report will list tradelines, delinquencies, collections, and public records. Look for stale data. A collection paid in 2018 should drop off after seven years from the date of first delinquency. If it is still there, dispute it. If you decide to move forward with an adverse action based on the report, the FCRA requires a specific sequence. First, give the person a pre-adverse action notice that includes a copy of the report and a summary of their rights. Wait a reasonable period. Then issue the final adverse action notice. Skipping the pre-adverse step is one of the most common legal mistakes I see. The lawsuit risk goes from nuisance to serious very quickly.
I ran a tenant screening last year where the applicant had two identical collections from the same medical provider, same dollar amount, same date reported. The consumer reporting agency's merge logic treated them as one tradeline because the creditor code matched, but the underlying accounts were separate lines of credit the person held. I caught it because I cross-referenced the original creditor numbers rather than trusting the merged view. Had I approved based on the merged data, I would have been one dispute away from a failed reference check. The workaround was to request the underlying account detail from the CRA and then ask the applicant for documentation showing which account the second collection belonged to. Most applicants do not have that readily available. It takes time. But it saved me from approving a tenant who actually had twice the collection exposure I thought.
Get the Full Details
What the Report Actually Contains and Where It Falls Short
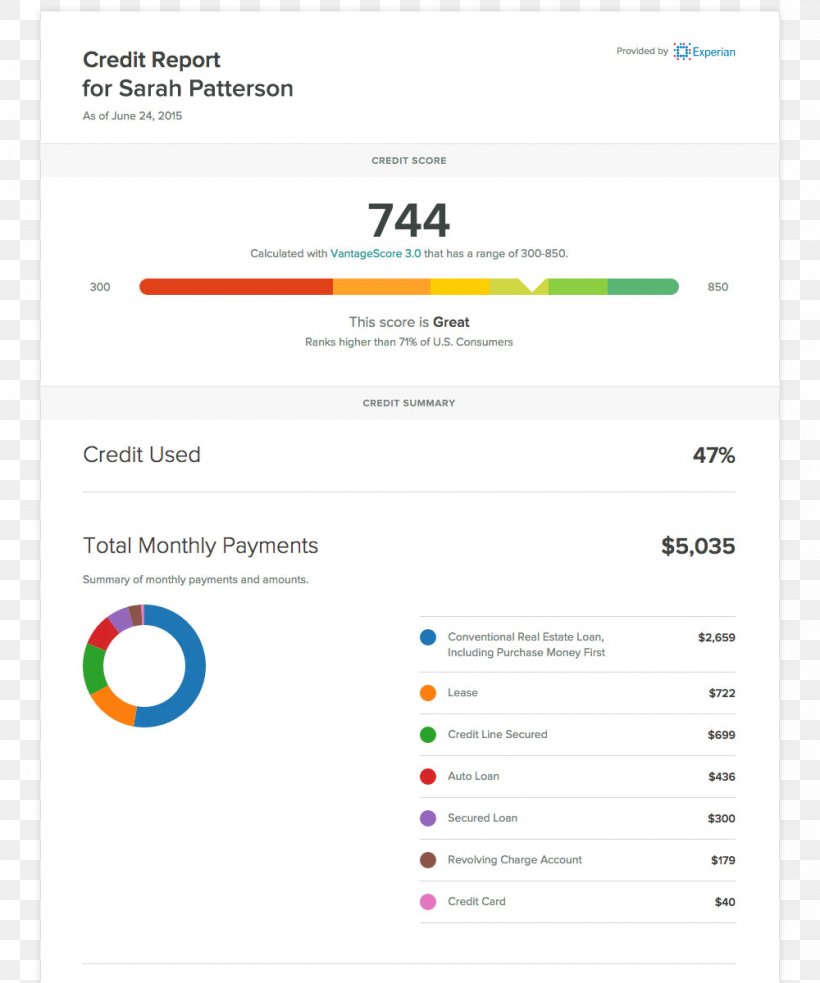
A standard employment background check with credit history typically returns a credit-based insurance score or a responsibility score if you are screening for positions of trust. It does not return your FICO number. Some employers misunderstand this and think the score they see is a traditional credit score. It is not. The metrics are different. One measures credit risk. The other measures how responsibly someone manages financial obligations as part of a broader background. You will see closed accounts. You will see open accounts. You will see inquiry history, though hard inquiries are less relevant for most screening purposes. You will see bankruptcy filings, tax liens, and civil judgments depending on the state. California and New York restrict what landlords and employers can see compared to states with fewer limitations. The biggest gap most people hit is the lag time. Creditors report to bureaus on different cycles. Some report monthly. Others report quarterly or on their own internal schedules. A late payment today might not appear on a consumer report for 30 to 60 days. That delay means a report you pull on Monday might look clean even though the person missed a payment last week. If your hiring or leasing decision depends on real-time accuracy, factor that lag into your process. Do not treat a clean report as a guarantee. Treat it as a snapshot from a data stream that is always slightly behind reality.
Another nuance is the difference between rescreening and fresh checks. If you use a subscription model with a CRA for ongoing monitoring, the cost per check drops significantly. A single one-off background check with credit history runs anywhere from fifteen to thirty-five dollars depending on the vendor and depth. Monthly subscriptions for high-volume screeners can bring that down to eight to twelve dollars per report. The tradeoff is that subscription data can be stale if the person's profile changes between pulls. I recommend a fresh pull for final decisions and a subscription model for ongoing watch-list screening. State law variation is where this gets messy. Massachusetts prohibits employers from asking about credit history during the initial hiring process in most cases. Illinois has strict requirements around notice and consent. New York City bans credit checks for most employers entirely. If you operate in multiple jurisdictions, your compliance team needs to know which rules apply to which candidate before you order any reports. A single noncompliant pull in NYC can trigger statutory damages that exceed the cost of the entire screening program.
When Credit History Does Not Belong in a Background Check
Not every role warrants a credit check. A retail associate, a software engineer, and a warehouse worker typically do not need financial transparency in the same way a CFO or a cash-handling employee does. The EEOC has issued guidance warning that blanket credit checks can create disparate impact against protected classes. That does not mean credit checks are illegal. It means you need a job-related justification and you need to apply the check consistently across similar roles. If you are a small landlord screening tenants, credit history is more relevant because rent payment is a financial obligation. But even then, consider whether you actually need a full credit report or whether a credit score check or a rental-specific screening service is sufficient. Some vendors offer tenant-only products that focus on evictions and payment history rather than full consumer credit. Those often surface faster and raise fewer EEOC concerns while still giving you the signal you need. The core takeaway is that Background Check Credit History is a tool, not a verdict. The data is imperfect by design. It lags. It merges inconsistently. It varies by state. It requires procedural compliance to use legally. Pull it carefully, review it before acting, and document your process so you can defend it if someone pushes back.