Why You Probably Need One of These
Most mortgage calculators work forward. You type in a loan amount, interest rate, and term, and they spit out your monthly payment. That works fine if you know how much house you can buy. But in practice, most people already know their payment limit before they look at listings. They've been burned by HOA fees, property taxes, or insurance surprises. The forward calculator doesn't account for that friction. A Backwards Mortgage Calculator flips the direction. You enter your maximum comfortable monthly payment, the interest rate you expect, and the amortization period. The tool tells you what principal you can actually borrow. It sounds trivial. It isn't.
How the Backwards Mortgage Calculator Actually Works
The math underneath is straightforward. Standard mortgage payment formula rearranged for present value: P = M × [ (1 - (1 + r)^(-n)) / r ] Where P is the principal you can afford, M is your target monthly payment, r is the monthly interest rate (annual rate divided by 12), and n is the total number of payments. That's it. No magic. But here's where it gets messy in real life.
The tool only gives you the principal portion. It doesn't include property tax, homeowners insurance, PMI, or HOA fees. If you enter $2,400 as your target payment and the calculator says you can borrow $380,000, you'll still be underwater the moment closing costs and escrow hit. I learned this the hard way in 2019 helping a friend who was buying their first home in Colorado. We ran the numbers through a backward calculator, got a comfortable principal estimate, and then the lender's actual qualification threw us a curveball: debt-to-income ratio combined with the property tax assessment in that county pushed the effective payment above what she could sustain. The workaround was to back out the estimated escrow components from her target payment first, then feed the remainder into the calculator. Property tax alone in that area was eating about $340 a month. Once I subtracted that along with an estimated $95 for insurance and roughly $60 for PMI at the time, the actual borrowable principal dropped to about $320,000 instead of the $380,000 the calculator initially suggested.
Get the Full Details
Common Pitfalls That Catch People Off Guard
First, interest rate selection. People tend to plug in the rate they see on a headline ad — 5.875%, something clean and appealing. The actual rate you qualify for will be different based on credit score, loan type, and point shopping. A quarter-point difference on a 30-year loan changes your purchasing power by roughly 3 to 4 percent of the principal. Use a range. Run the calculator at your expected rate, then again at rate plus 0.5 percent. That spread tells you your real risk buffer. Second, amortization period assumptions. A lot of people assume 30 years because that's what they've heard of. But if you're looking at a 15-year product, the same monthly payment supports roughly 60 to 65 percent of the principal compared to a 30-year term at the same rate. Not half. About two-thirds. The compounding effect of a shorter term is significant but people routinely overlook it when comparing options backward. Third, the balloon payment trap. Some reverse mortgage products or interest-only periods distort the calculation entirely. A backwards calculator assuming full amortization over 30 years will give you a number that looks healthy until you realize the principal never actually reduces for the first seven years. If you're evaluating an ARM with an initial fixed period followed by a adjustment, run separate calculations for the fixed period payment versus the fully adjusted payment. The difference can be enough to disqualify you at refinance time.
When It Fails Completely
The calculator breaks down when your financial situation involves variable income. Commission-based earners, self-employed contractors, and seasonal workers can't meaningfully pin a single monthly payment number to their qualification. The tool will give you a figure, but lenders will underwrite against your average or worst-case month, not your best. I had a client who was a freelance graphic designer showing $4,200 in monthly capacity through the backwards calculator. The lender's automated underwriting system looked at two years of tax returns, found income volatility exceeding 40 percent year-over-year, and dropped his qualifying principal by nearly a third. The tool wasn't wrong. The input was just unrealistic for how lenders actually evaluate him. Another scenario where it fails: cash-out refinances with aggressive home value projections. If you're using the calculator to determine how much you can pull out of existing equity, and the underlying home value is based on an optimistic appraisal rather than a conservative market comp, the whole calculation rests on a wobbly foundation. Run the calculator with a 10 percent downward adjustment to your estimated home value before proceeding. It will feel uncomfortable. It will also save you from overleveraging.
Practical Setup
If you want to build your own, a spreadsheet gets you there in about twenty minutes. Column A: your target payment. Column B: annual interest rate. Column C: amortization in years. Column D: the formula =B2/12 for monthly rate. Column E: =C2*12 for total payments. Column F: =PV(D2,E2,-A2,0,0) for the affordable principal. That's the core. Format the cells as currency and percentages, add a couple of scenario rows with different rates, and you have something functional. For a downloadable option, a simple HTML page with three input fields and a JavaScript PV function works better than most paid tools I've seen. The key is making sure the output clearly labels what the number includes and what it excludes. Most free online versions don't do this. They present a principal figure without any disclaimer about escrow, taxes, or insurance, which means users treat it as a hard ceiling rather than a starting point.
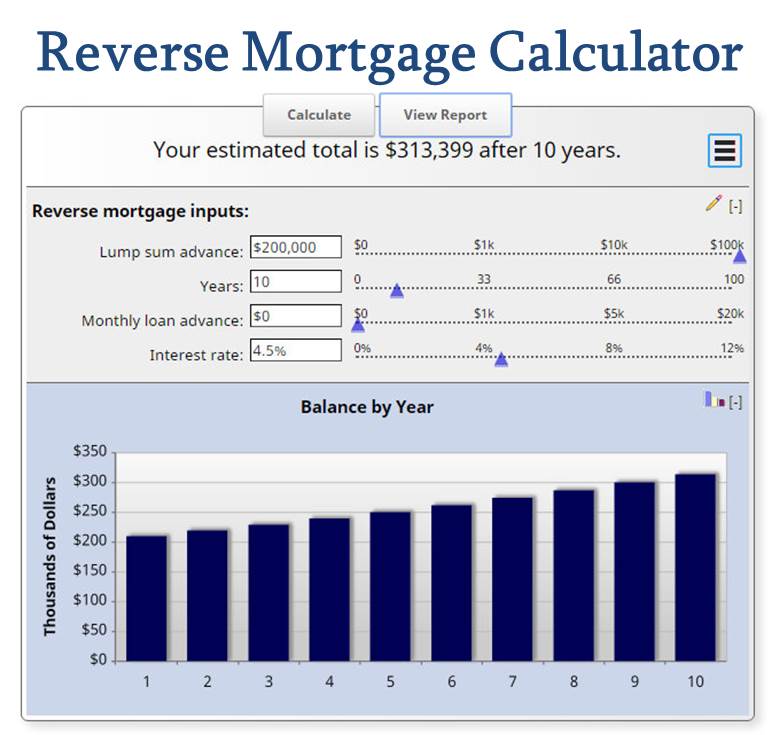
Using the Backwards Mortgage Calculator Effectively
Run it before you talk to a lender, not after. The sequence matters. If you go to a lender first, they'll give you a pre-approval amount that includes their own margin for error and their risk tolerance. That number might be higher or lower than what your personal budget actually supports. The calculator gives you your own number first. Then you compare. The gap between the two tells you something useful about where you stand. Also run it with your actual credit score in mind. I've seen too many people use a textbook 6.5 percent rate when their FICO is in the mid-640s, which typically lands them at 7.1 or 7.2 at current market conditions. That point difference on a 30-year $350,000 loan changes the monthly payment by about $45. Running the backwards calculation at the wrong rate makes you think you can afford a property you can't actually service at your real rate. The tool is useful, but it's a planning instrument, not a underwriting document. Use it to narrow your search range. Use it to understand rate sensitivity. Don't treat the output as anything closer to a commitment than it actually is.